


Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Hedge Fund Due Diligence: A Practical Guide
Hedge fund due diligence is the disciplined process of deciding whether a fund is understandable, investable, operationally sound, and suitable for an investor’s mandate. It combines investment analysis with independent verification of the people, controls, legal structure, custody, valuation, service providers, and reporting that sit behind the return stream.
A strong review does more than collect a completed questionnaire. It turns each important claim into an evidence request, assigns a qualified reviewer, records unresolved issues, and gives the investment committee a decision trail. The same structure then becomes the baseline for ongoing monitoring after capital is committed.
Hedge funds can use flexible strategies, leverage, short selling, derivatives, and less liquid assets. The Investor.gov hedge fund guide emphasizes understanding strategy risk, valuation, fees, redemption limits, and manager background before investing. This guide turns those questions into a practical diligence workflow. It is educational information, not investment, legal, tax, or regulatory advice.
In this guide:
- What is hedge fund due diligence?
- Why does hedge fund due diligence matter?
- What should hedge fund due diligence cover?
- What red flags should stop or pause an investment?
- How do you run a hedge fund due diligence process?
- Which questions should the diligence team ask?
- How should ongoing due diligence work?
- How can Process Street support due diligence?
- Hedge fund due diligence FAQs
What is hedge fund due diligence?
Hedge fund due diligence is a decision process, not a document request. The investor starts with a mandate and a set of risks that matter, tests the fund’s claims against evidence, resolves contradictions, and records why the opportunity should be approved, declined, or approved with conditions.
The work normally has two connected tracks. Investment due diligence evaluates the strategy, edge, portfolio construction, historical behavior, liquidity, leverage, capacity, and fit with the investor’s portfolio. Operational due diligence evaluates whether the manager’s organization and control environment can safeguard assets, value the portfolio, produce reliable records, manage conflicts, recover from disruption, and keep operating under pressure.
The core question is not whether the fund has a policy. It is whether people, systems, service providers, and evidence show that the policy operates in practice.
Both tracks should reach the investment committee together. A compelling strategy does not cure weak custody or valuation controls. A polished control environment does not make an unsuitable strategy investable. The final decision needs a joined-up view of return potential, downside behavior, operational resilience, legal terms, and the investor’s ability to monitor the position.
Why does hedge fund due diligence matter?
Private funds do not offer the same standardized disclosure and liquidity profile as registered retail funds. Information may be negotiated, strategy exposures may change, valuations may involve judgment, and redemption rights may be restricted. That makes the quality of the investor’s own investigation especially important.
Private offerings can provide less standardized disclosure than registered offerings. The Investor.gov private placement bulletin advises investors to obtain the information they need, test whether claims are reasonable, understand conflicts, and treat inadequate answers as a warning. A disciplined hedge fund review turns that principle into assigned verification work.
- Suitability: confirm that the strategy, liquidity, leverage, complexity, and loss profile fit the investor’s mandate.
- Integrity: verify the manager, key people, track record, representations, and disciplinary history.
- Asset protection: understand where assets are held, who can move them, and how records are reconciled.
- Operational resilience: test whether controls, technology, people, and service providers can support the strategy.
- Decision quality: make assumptions, concerns, conditions, and dissent visible before commitment.
- Monitoring: establish the baseline against which future changes and exceptions will be judged.
What should hedge fund due diligence cover?
Due diligence scope matrix
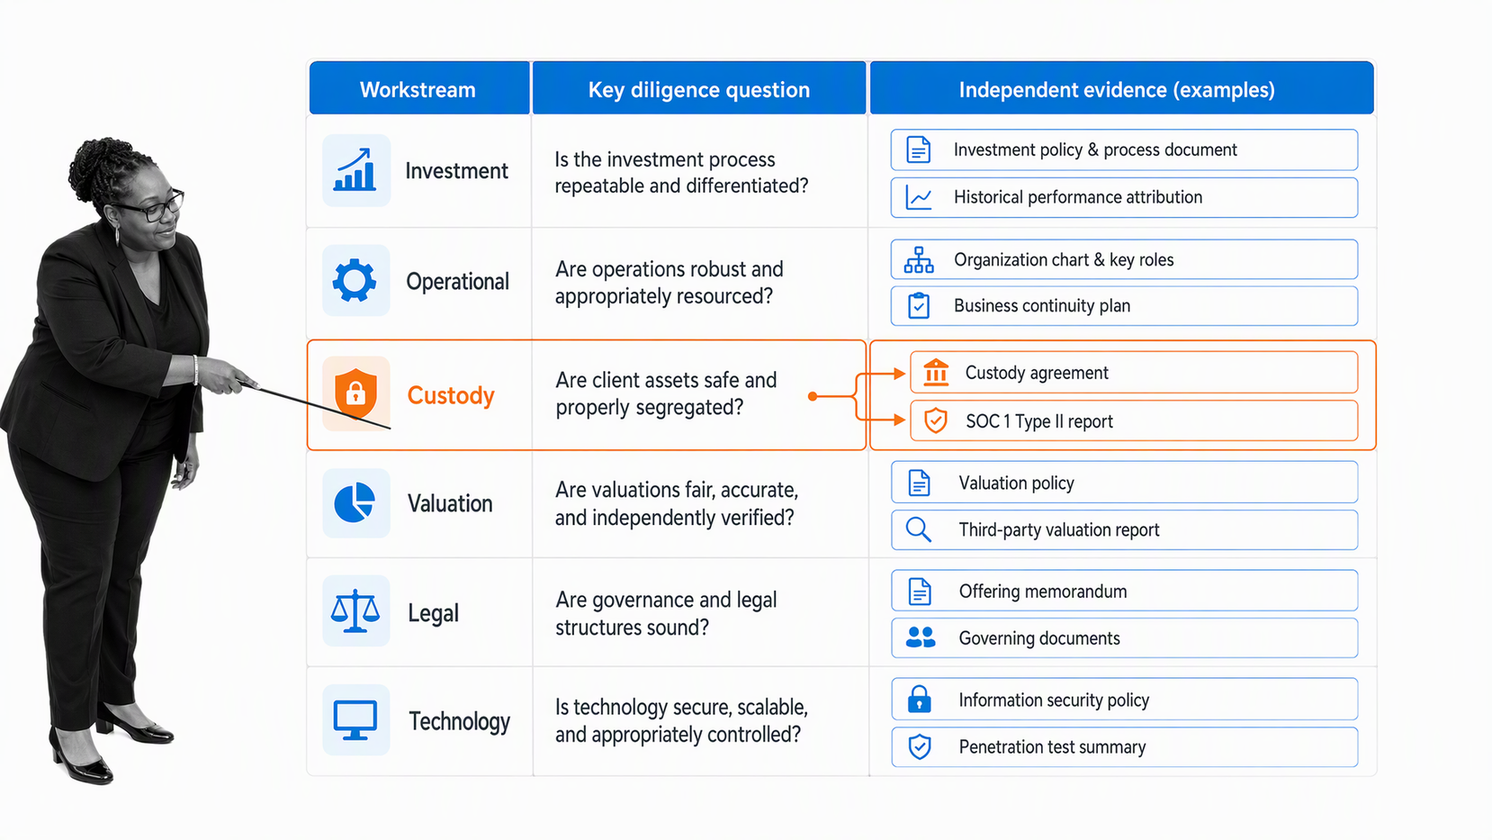
Scope should follow risk. A liquid public-markets strategy and a concentrated strategy holding hard-to-value assets should not receive identical questionnaires. The matrix below provides a starting point, then the team should deepen the work wherever complexity, discretion, concentration, or weak transparency raises the stakes.
| Workstream | Questions to resolve | Evidence to test |
|---|---|---|
| Strategy and edge | How are positions sourced, sized, hedged, exited, and reviewed? | Investment process, examples, exposures, risk reports, and attribution |
| People and governance | Who makes decisions, who challenges them, and what happens during absence or turnover? | Organization map, responsibilities, committees, succession, and references |
| Performance and risk | Are results consistent with the stated process and risks? | Return series, drawdowns, exposures, leverage, liquidity, and independent records |
| Operations | Can the firm book, reconcile, value, settle, report, and recover reliably? | Procedures, reconciliations, exception logs, continuity tests, and control evidence |
| Custody and assets | Where are assets held and who can direct movement? | Custodian, prime broker, administrator, account, authorization, and statement evidence |
| Valuation | Who prices assets and how are difficult cases challenged? | Valuation policy, price sources, overrides, committee records, and administrator checks |
| Legal and compliance | Do the structure, terms, disclosures, and actual practices align? | Offering documents, side letters, filings, conflicts, compliance testing, and counsel review |
| Technology and security | Can systems protect data and sustain critical operations? | Access controls, vendors, incident response, backup, recovery, and test results |
Investment strategy and performance
Begin by making the strategy explainable. The team should be able to describe what creates returns, which conditions support the approach, what causes losses, how positions are sized, how gross and net exposure change, how liquidity is measured, and where judgment enters the process. Performance analysis should test the explanation, not replace it.
Reconcile performance to independent sources where possible. Examine drawdowns, recovery behavior, concentration, factor exposure, leverage, turnover, capacity, and the effect of fees. Ask for examples of successful and unsuccessful positions. The aim is to understand whether the realized record is plausible given the stated process and whether the investor can tolerate the path, not just the endpoint.
People, governance, and conflicts
Map who owns research, trading, risk, valuation, operations, compliance, technology, and investor reporting. Identify key-person dependence and whether oversight is genuinely independent from revenue and portfolio decisions. Background checks and references should test both competence and consistency.
Conflicts need a complete view. Consider related entities, cross-trades, allocation between funds and accounts, personal trading, outside activities, expense allocation, valuation incentives, fee arrangements, and side-letter rights. The diligence record should show how each material conflict is disclosed, controlled, monitored, and escalated.
Operations, valuation, custody, and service providers
Follow a trade and a cash movement through the operating model. Who books it, who confirms it, who reconciles it, who resolves a break, who values it, and who can approve movement of funds? A narrative answer is useful only when it connects to systems, roles, segregation, evidence, and exception handling.
Custody deserves direct verification. The Investor.gov custody bulletin explains the role of qualified custodians, account statements, and independent safeguards, while also warning that regulatory protections do not replace investor care. Review the actual custody structure, statement flow, authorization controls, reconciliation process, and any related-party arrangements.
Interview material service providers using independently sourced contact details. Confirm the relationship, scope, reporting, escalation path, recent changes, and any limitations on what the provider verifies. A respected administrator, auditor, prime broker, or custodian does not transfer responsibility for understanding the fund’s control environment.
Legal, regulatory, and disclosure review
Offering and governing documents should be read alongside marketing materials, diligence responses, policies, and actual practice. For a registered adviser, use the Investment Adviser Public Disclosure database to review Form ADV information and disciplinary disclosures. Registration or a filing is not an endorsement, so the team still needs to test the facts and the fit.
Qualified counsel should examine the fund structure, investor eligibility, subscription documents, redemption and suspension rights, gates, side pockets, valuation discretion, fees and expenses, indemnification, removal and termination provisions, side letters, tax considerations, and governing law. Track every negotiated term and condition into the final decision record and post-investment monitoring plan.
What red flags should stop or pause an investment?
Red flag review board
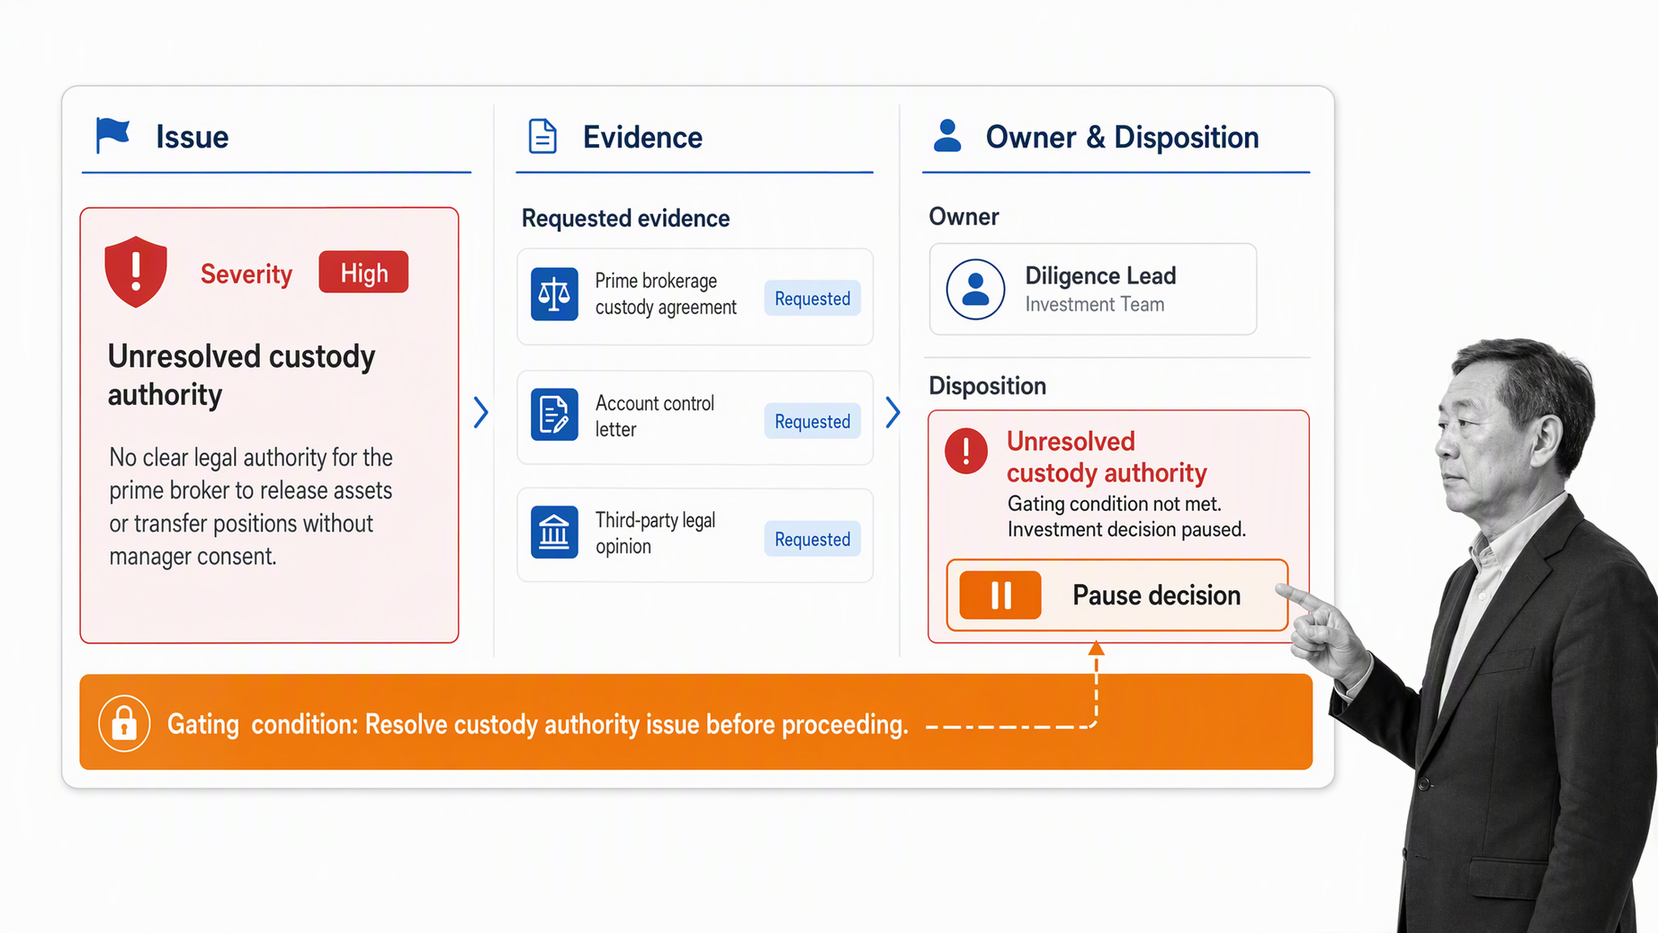
A red flag is a reason to investigate, not a substitute for judgment. The team should classify the issue, assign an owner, request specific evidence, record management’s response, and decide whether the concern is resolved, accepted with conditions, or disqualifying.
| Signal | Why it matters | Required response |
|---|---|---|
| Answers change across interviews or documents | The operating story may be unreliable | Reconcile each contradiction and retain supporting evidence |
| Performance cannot be independently supported | Returns may be misstated or misunderstood | Pause analysis until source records and calculation methods are clear |
| Valuation relies heavily on the portfolio team | Incentives and model judgment may be insufficiently challenged | Test independence, overrides, governance, and difficult examples |
| Custody or cash authority is unclear | Assets may be exposed to unauthorized movement or weak oversight | Verify accounts, authority, statements, reconciliation, and escalation directly |
| Service providers change repeatedly | Turnover may signal unresolved operating or relationship problems | Understand causes, transition controls, and outstanding issues |
| Reasonable verification is resisted | The investor may not be able to understand or monitor the risk | Define the minimum evidence required and decline if it is unavailable |
| Policy differs from observed practice | Controls may exist only on paper | Test actual cases and require remediation before approval |
Avoid scoring systems that let many low-risk answers cancel one critical failure. Some issues are gating conditions. Unverified custody, unreliable records, material misrepresentation, unresolved legal concerns, or an inability to understand the strategy can justify stopping regardless of the aggregate score.
How do you run a hedge fund due diligence process?
Stage-gated diligence workflow
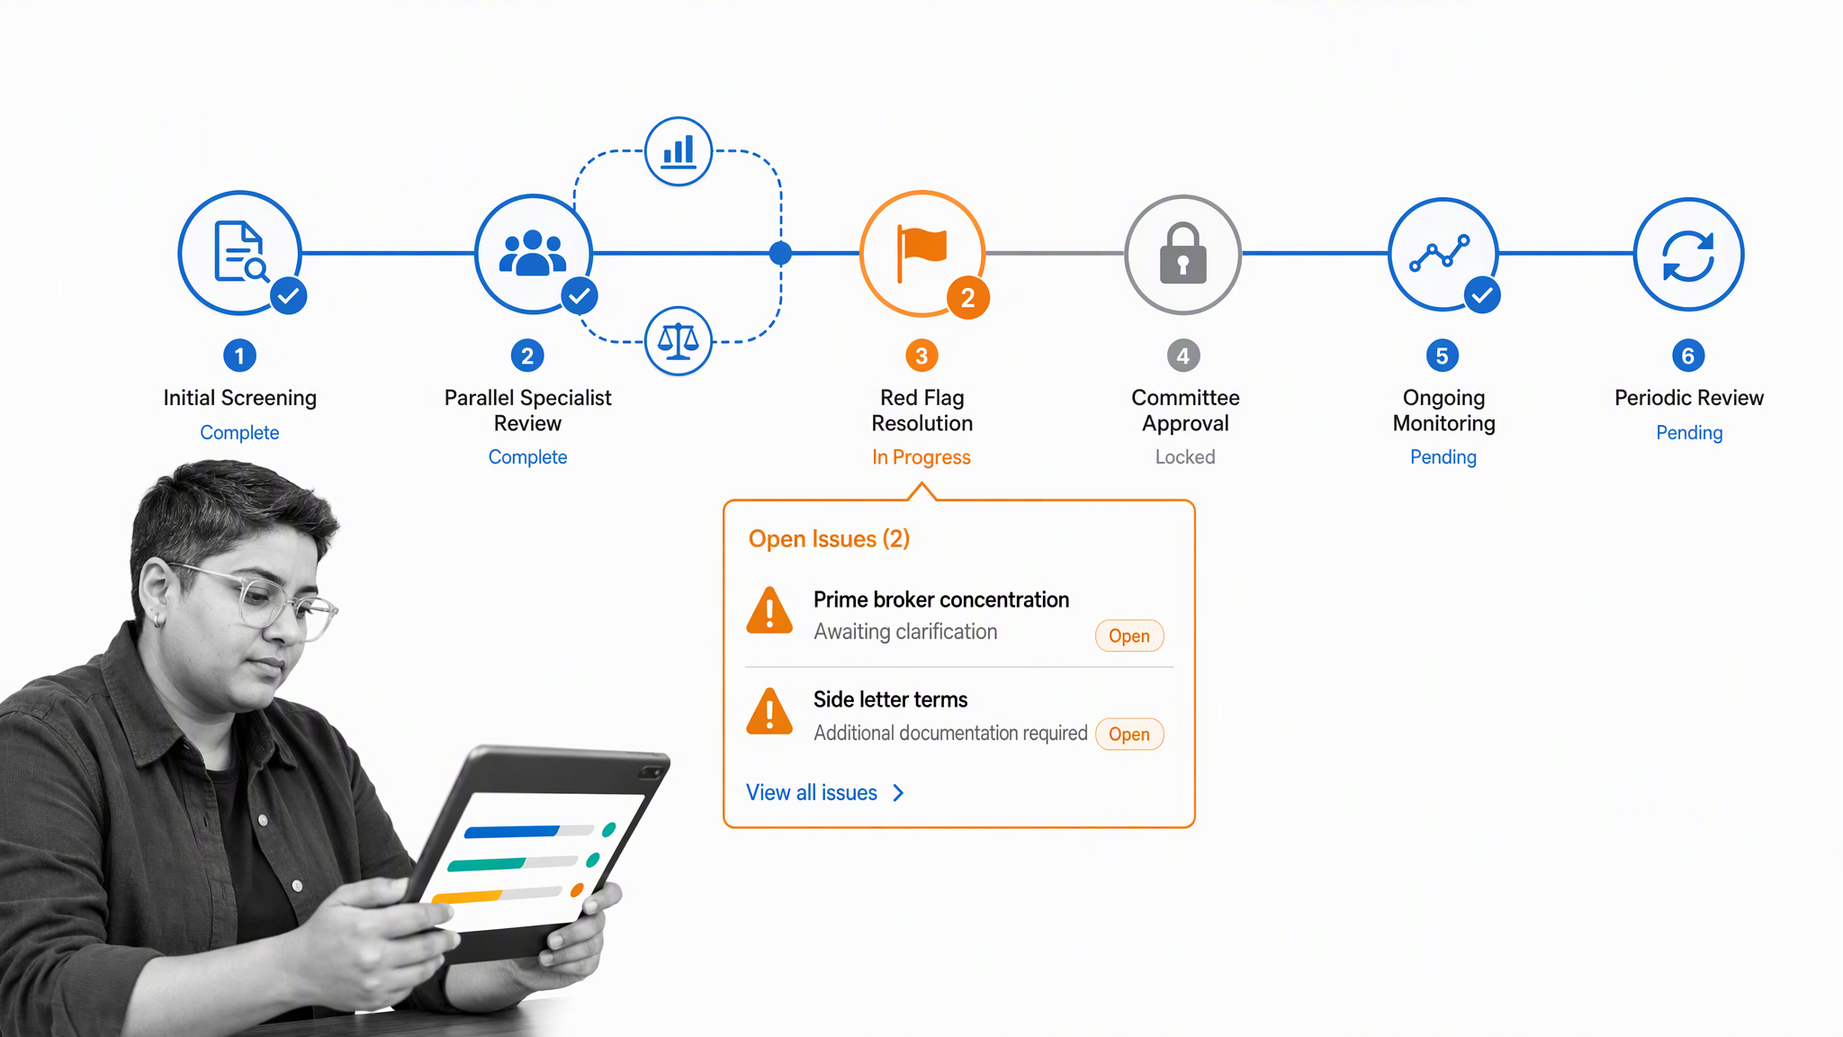
A stage-gated process creates a clean handoff from initial fit to deep review, investment committee decision, onboarding, and monitoring. Each stage should have an owner, required inputs, decision criteria, open-issue log, and approval gate.
- Define the mandate. Record objectives, liquidity needs, risk limits, concentration rules, prohibited exposures, and decision authority.
- Screen for fit. Review the strategy, team, terms, liquidity, transparency, capacity, and obvious conflicts before launching full diligence.
- Issue a tailored request. Ask for documents and data tied to the specific strategy and operating risks, not a generic data room dump.
- Run parallel workstreams. Coordinate investment, operational, legal, tax, compliance, technology, and background reviews with clear ownership.
- Interview and verify. Use manager meetings, service-provider confirmations, references, records, and independent sources to test the written answers.
- Resolve red flags. Keep a live issue register with evidence, response, owner, due date, severity, and disposition.
- Write the decision memo. State the thesis, risks, unresolved issues, conditions, dissent, monitoring plan, and reasons for the recommendation.
- Approve and onboard. Carry every condition into subscription, funding, data, reporting, and operational setup tasks.
- Monitor against the baseline. Review performance, exposures, people, controls, service providers, terms, compliance, and exceptions throughout the relationship.
The process should make independence visible. The person championing the investment should not be the only person deciding whether operational or legal concerns are acceptable. Each specialist should be able to record a view, and the final approver should see both agreement and dissent.
Decision memo and evidence register
The decision memo should be concise enough to use and detailed enough to defend. It needs the investment thesis, expected role in the portfolio, key assumptions, risk and liquidity analysis, operational assessment, legal terms, material conflicts, unresolved items, negotiated protections, approval conditions, and monitoring triggers.
Link claims to evidence rather than copying the data room into the memo. An evidence register can record the item requested, source, date received, reviewer, finding, related issue, confidentiality rule, retention location, and whether the evidence was independently verified. This makes later monitoring and re-diligence much faster.
Which questions should the diligence team ask?
Questions for the investment team
- What market behavior creates the opportunity, and why should it persist?
- Which positions, factors, counterparties, and financing relationships can dominate losses?
- How do leverage, liquidity, concentration, and hedges change during stress?
- What explains the largest gains, losses, and differences from stated expectations?
- How are ideas challenged, sized, reduced, and exited?
- What limits capacity, and how would asset growth change execution?
Questions for operations and control owners
- Which records are produced internally, which come from service providers, and how are differences reconciled?
- Who can approve cash movement, pricing overrides, new counterparties, and access changes?
- How are unresolved breaks aged, escalated, and closed?
- Which assets require models or broker quotes, and who challenges those inputs?
- What happened during the most recent disruption, incident, or failed control test?
- How are critical processes recovered when key people or systems are unavailable?
Questions for service providers and references
- What services are provided, and what is explicitly outside scope?
- Which records originate with the provider and which are supplied by the manager?
- How are exceptions, late files, overrides, and disagreements handled?
- Have scope, personnel, systems, or terms changed materially?
- What information can the provider verify independently?
- Does the manager respond to issues promptly and provide complete information?
How should ongoing due diligence work?
Ongoing monitoring dashboard
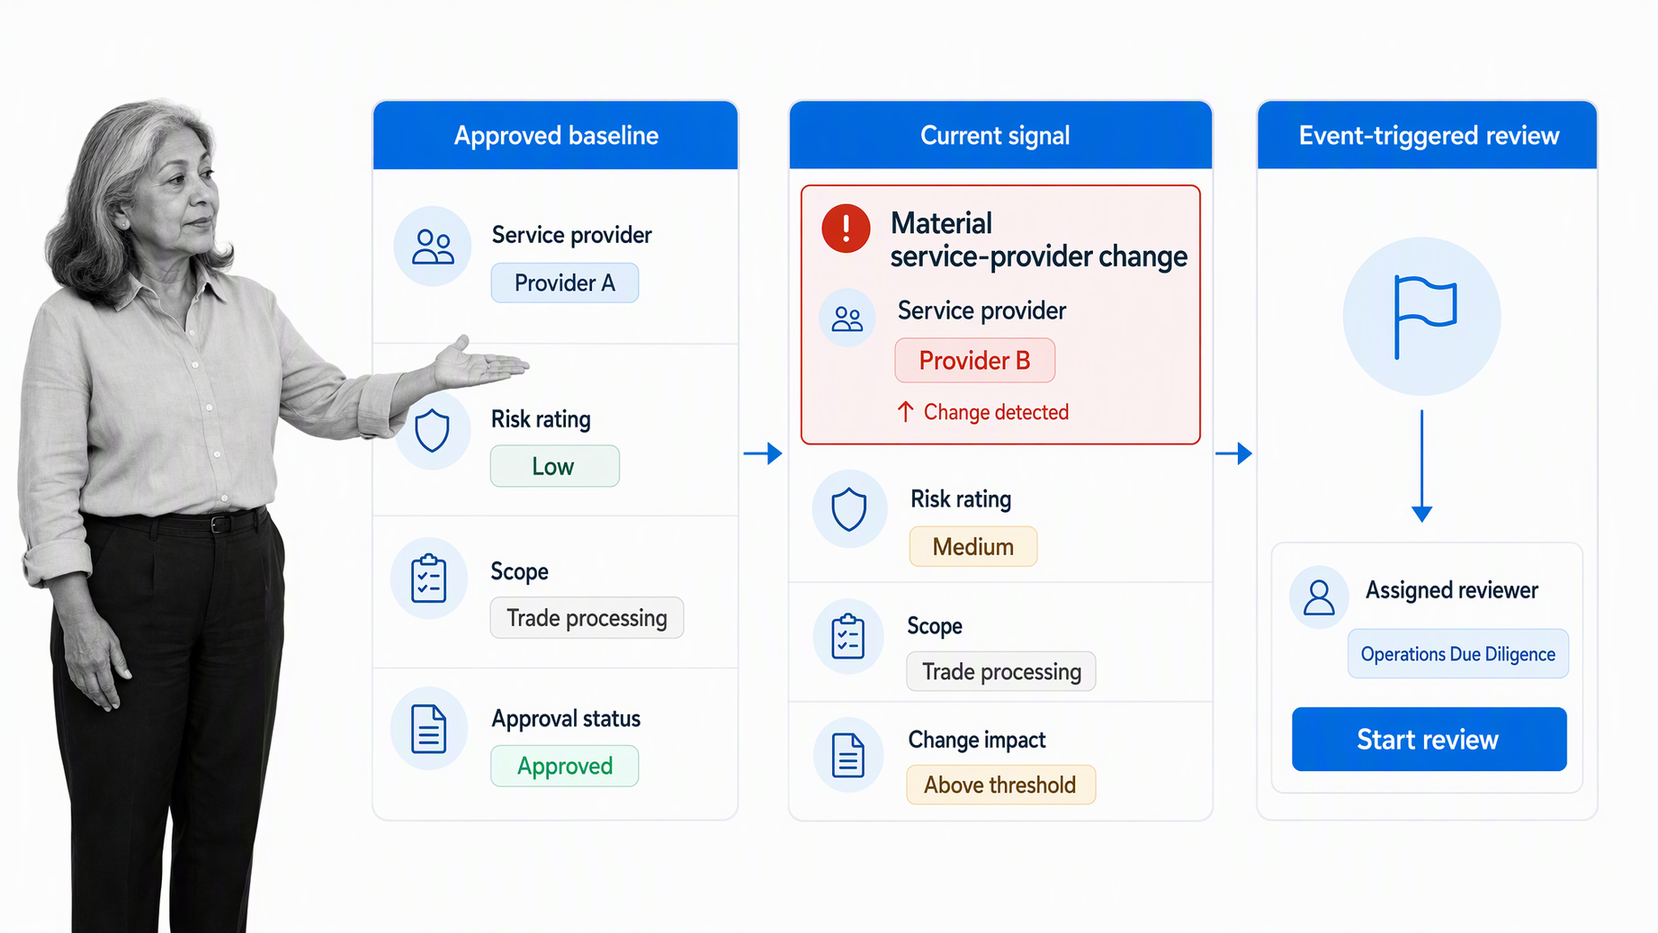
Ongoing diligence should compare current reality with the approved baseline. The monitoring plan needs defined data, owners, cadence, thresholds, and event triggers. It should surface change early enough for the investor to investigate, impose conditions, reduce exposure, or exit within the available rights.
| Monitoring area | Example signals | Escalation question |
|---|---|---|
| Performance and exposure | Unexpected losses, drift, concentration, leverage, liquidity change | Is behavior consistent with the approved strategy and risk budget? |
| People and organization | Departure, role change, hiring gap, ownership change | Does the thesis or control environment depend on the affected person? |
| Operations and service providers | Late NAV, breaks, audit delay, vendor change, control exception | Is this isolated, recurring, or evidence of a broader weakness? |
| Legal and compliance | Filing change, inquiry, breach, dispute, new conflict | What changed, who is affected, and what response is required? |
| Terms and investor rights | Side letter, liquidity action, fee change, suspension, gating event | Does the change alter fairness, access, or the ability to manage exposure? |
| Technology and security | Incident, outage, recovery failure, access exception | Were critical records or operations affected, and was remediation verified? |
Schedule periodic full reviews, but do not wait for the calendar when a material event occurs. Changes in strategy, ownership, key personnel, liquidity, valuation, leverage, service providers, control failures, cybersecurity, legal status, or investor terms should trigger targeted re-diligence.
How can Process Street support hedge fund due diligence?
A workflow product can turn diligence from a shared folder and spreadsheet into controlled execution. Process Street supports assigned workflows with owners, due dates, required fields, conditional paths, approval gates, evidence capture, and audit history. The workflow coordinates the work and proof while qualified investment, legal, tax, compliance, and technical reviewers retain responsibility for judgment.
Start with the operational due diligence checklist for hedge funds, then adapt questions, evidence, routing, and approvals to the strategy and mandate. Teams running recurring fund operations can also connect diligence findings to a broader hedge fund operations workflow for reconciliations, exceptions, approvals, and periodic reviews.
| Diligence stage | Process Street pattern | Control outcome |
|---|---|---|
| Scope and intake | Structured mandate, strategy profile, and risk-based routing | Review depth follows the actual risk |
| Document request | Assigned requests with required fields, files, and due dates | Missing evidence is visible |
| Parallel review | Separate specialist tasks with shared issue records | Views remain attributable and comparable |
| Red flags | Conditional escalation with severity, owner, response, and disposition | Critical issues cannot disappear in comments |
| Committee decision | Approval gate linked to memo, evidence, conditions, and dissent | The decision has a complete record |
| Ongoing monitoring | Recurring workflows with event-triggered reviews and exception tracking | Changes are tested against the approved baseline |
The best first workflow is the one that currently causes the most chasing or uncertainty. Build the process around one fund review, require evidence at the point of work, and make the approval depend on resolved gating issues. Then reuse the structure without turning it into a one-size-fits-all questionnaire.
Hedge fund due diligence FAQs
What is hedge fund due diligence?
Hedge fund due diligence is the structured investigation an investor performs before committing capital and throughout the investment. It tests the strategy, people, performance, operations, legal terms, custody, service providers, compliance, conflicts, and reporting against the investor’s mandate and risk tolerance.
What is the difference between investment and operational due diligence?
Investment due diligence asks whether the strategy can plausibly deliver its objective at an acceptable level of risk. Operational due diligence asks whether the organization, controls, service providers, valuation, custody, technology, and governance can protect assets and support the strategy reliably.
Which documents should an investor request?
The request should be tailored to the fund, but commonly includes offering and governing documents, audited financial statements, performance and exposure reports, valuation and risk policies, service-provider details, compliance materials, cybersecurity and business-continuity information, and evidence supporting key controls.
What are common hedge fund due diligence red flags?
Common red flags include inconsistent answers, unexplained performance, weak valuation independence, unclear custody, concentrated authority, related-party conflicts, repeated service-provider changes, poor evidence, resistance to reasonable verification, and material differences between written policy and actual practice.
How often should hedge fund due diligence be repeated?
Due diligence should continue after investment. The monitoring cadence should reflect the fund’s strategy and risk, with event-driven reviews when material changes occur in people, terms, liquidity, service providers, systems, compliance status, controls, or performance behavior.
How can Process Street support hedge fund due diligence?
Process Street can coordinate questionnaires, document requests, assigned reviews, conditional escalation, approval gates, evidence collection, decision records, and recurring monitoring in one controlled workflow. It supports execution and proof, while investment, legal, tax, and regulatory judgments remain with qualified professionals.
