


Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Weighted Average Cost of Capital (WACC): Formula and Guide
Weighted average cost of capital (WACC) is the blended rate a company is expected to pay for the debt and equity used to finance its operations. It gives finance teams a practical benchmark for valuation, capital budgeting, and investment decisions.
The idea is simple: debt and equity have different costs, so each cost is weighted by its share of the company’s capital structure. The result is one percentage that represents the required return across all capital providers.
This guide explains the formula, shows a worked calculation, clarifies when WACC is an appropriate discount rate, and identifies the assumptions that need the most scrutiny.
What will this WACC guide cover?
- What is weighted average cost of capital?
- What is the WACC formula?
- How do you calculate WACC?
- What are the components of WACC?
- How is WACC used?
- How does WACC differ from a required return?
- What is a good WACC?
- What are the limitations of WACC?
- How do you keep WACC current?
- WACC FAQs
What is weighted average cost of capital?
Weighted average cost of capital is a company-level estimate of the return required by the providers of its long-term financing. Equity investors expect a return for accepting business and market risk. Lenders expect interest for providing debt. WACC combines those required returns according to the market value of each financing source.
For a company financed only with common equity and debt, WACC is the weighted cost of equity plus the weighted after-tax cost of debt. If preferred stock is material, its weighted cost is included as a third component. The weights should add up to the full capital structure.
WACC is often described as a hurdle rate, but that phrase needs care. A company-wide WACC can be a reasonable starting point for a project whose operating risk and financing profile resemble the existing business. It is not automatically the correct discount rate for every investment.
What is the WACC formula?
For a capital structure containing common equity and interest-bearing debt, the standard formula is:
WACC = (E ÷ V × Re) + (D ÷ V × Rd × (1 − T))
Where:
- E is the market value of equity.
- D is the market value of interest-bearing debt.
- V is total capital, usually E + D when preferred stock is not material.
- Re is the cost of equity.
- Rd is the pre-tax cost of debt.
- T is the relevant marginal tax rate.
The formula follows the same structure presented in OpenStax’s finance treatment of WACC, including separate weights for debt, preferred stock, and common equity when all three are present.
WACC Formula Inputs
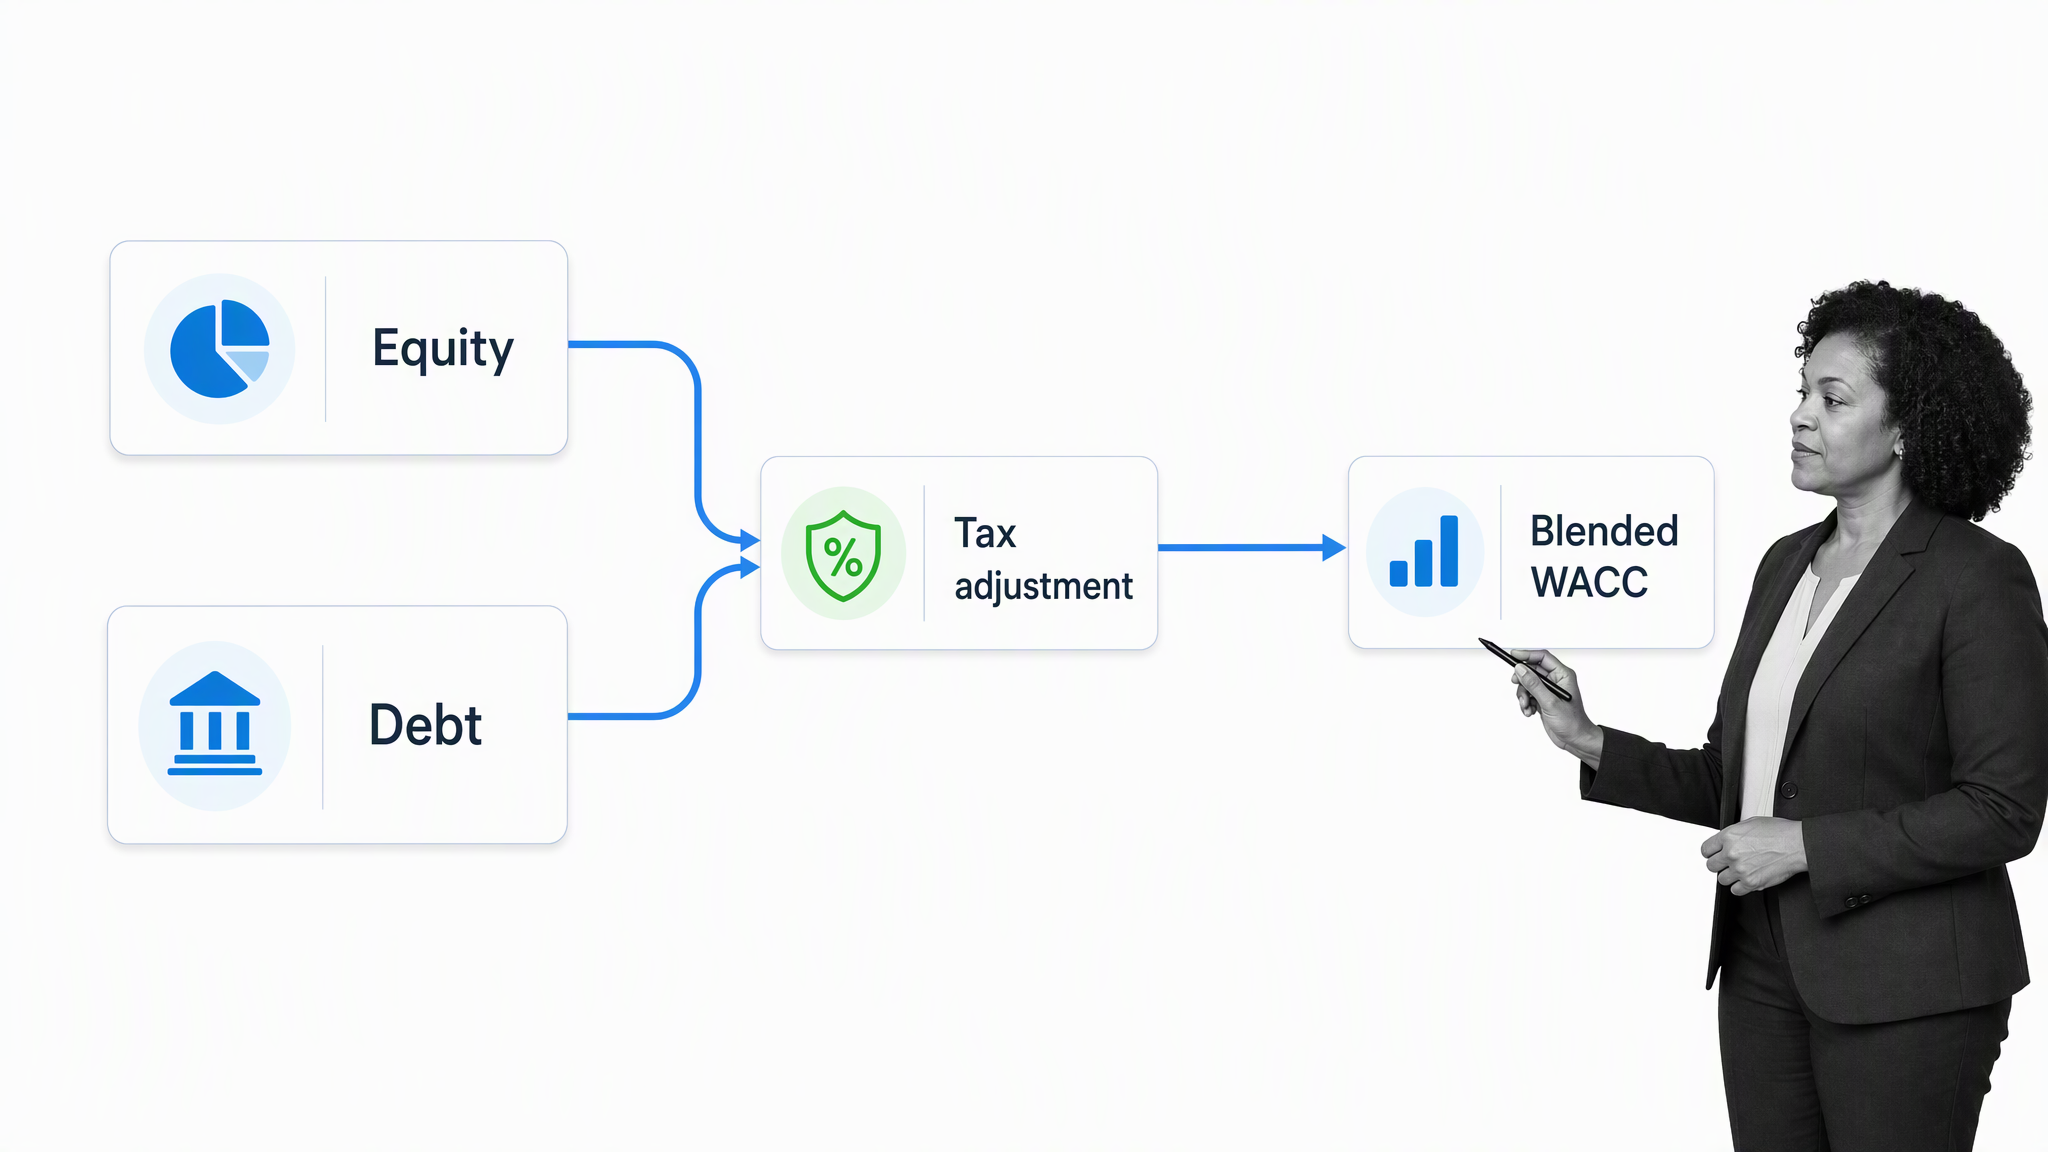
The formula is compact, but every input is an estimate. Use market values when possible because WACC is intended to reflect the current opportunity cost of capital, not the historical accounting amounts recorded when financing was first issued.
| Input | Common source | Main judgment |
|---|---|---|
| Equity value | Share price multiplied by diluted shares outstanding | Which share count and measurement date to use |
| Debt value | Market price of traded debt or an estimated present value | How to estimate private or illiquid debt |
| Cost of equity | CAPM or another defensible return model | Risk-free rate, beta, and equity risk premium |
| Cost of debt | Current yield or borrowing rate for comparable debt | Credit spread and debt maturity |
| Tax rate | Marginal rate applicable to interest deductions | Limits on deductibility and jurisdiction mix |
How do you calculate WACC?
A reliable calculation follows a consistent sequence. The arithmetic is usually the easy part. The quality of the result depends on how well the inputs match the company, valuation date, and cash flows being analyzed.
- Set the valuation date. Use market values and rate inputs observed on, or reasonably close to, the same date.
- Estimate the market value of equity. Multiply the current share price by the relevant diluted share count. For a private company, use a defensible valuation method or peer-based estimate.
- Estimate the market value of debt. Use quoted bond prices where available. For non-traded debt, estimate what the remaining payments would be worth at a current borrowing rate.
- Calculate the capital weights. Divide each financing source by total capital. Use target weights when the analysis is explicitly based on a target capital structure.
- Estimate the cost of equity. CAPM is common: risk-free rate + beta × equity risk premium. The U.S. Treasury’s published yield curve is one observable source for a U.S. dollar risk-free proxy, with the selected maturity matched to the analysis.
- Estimate the pre-tax cost of debt. Use the yield to maturity on existing debt or the rate the company would likely pay to borrow now, not merely the coupon on an old bond.
- Apply the tax adjustment. Multiply the cost of debt by (1 − T), but confirm that interest is actually deductible. The IRS explains current business-interest limitations and filing mechanics through Form 8990 guidance.
- Multiply and add. Apply each weight to its corresponding cost, then sum the weighted components.
- Run sensitivity checks. Recalculate with plausible changes to beta, credit spread, capital weights, tax treatment, and the equity risk premium.
Worked WACC Example
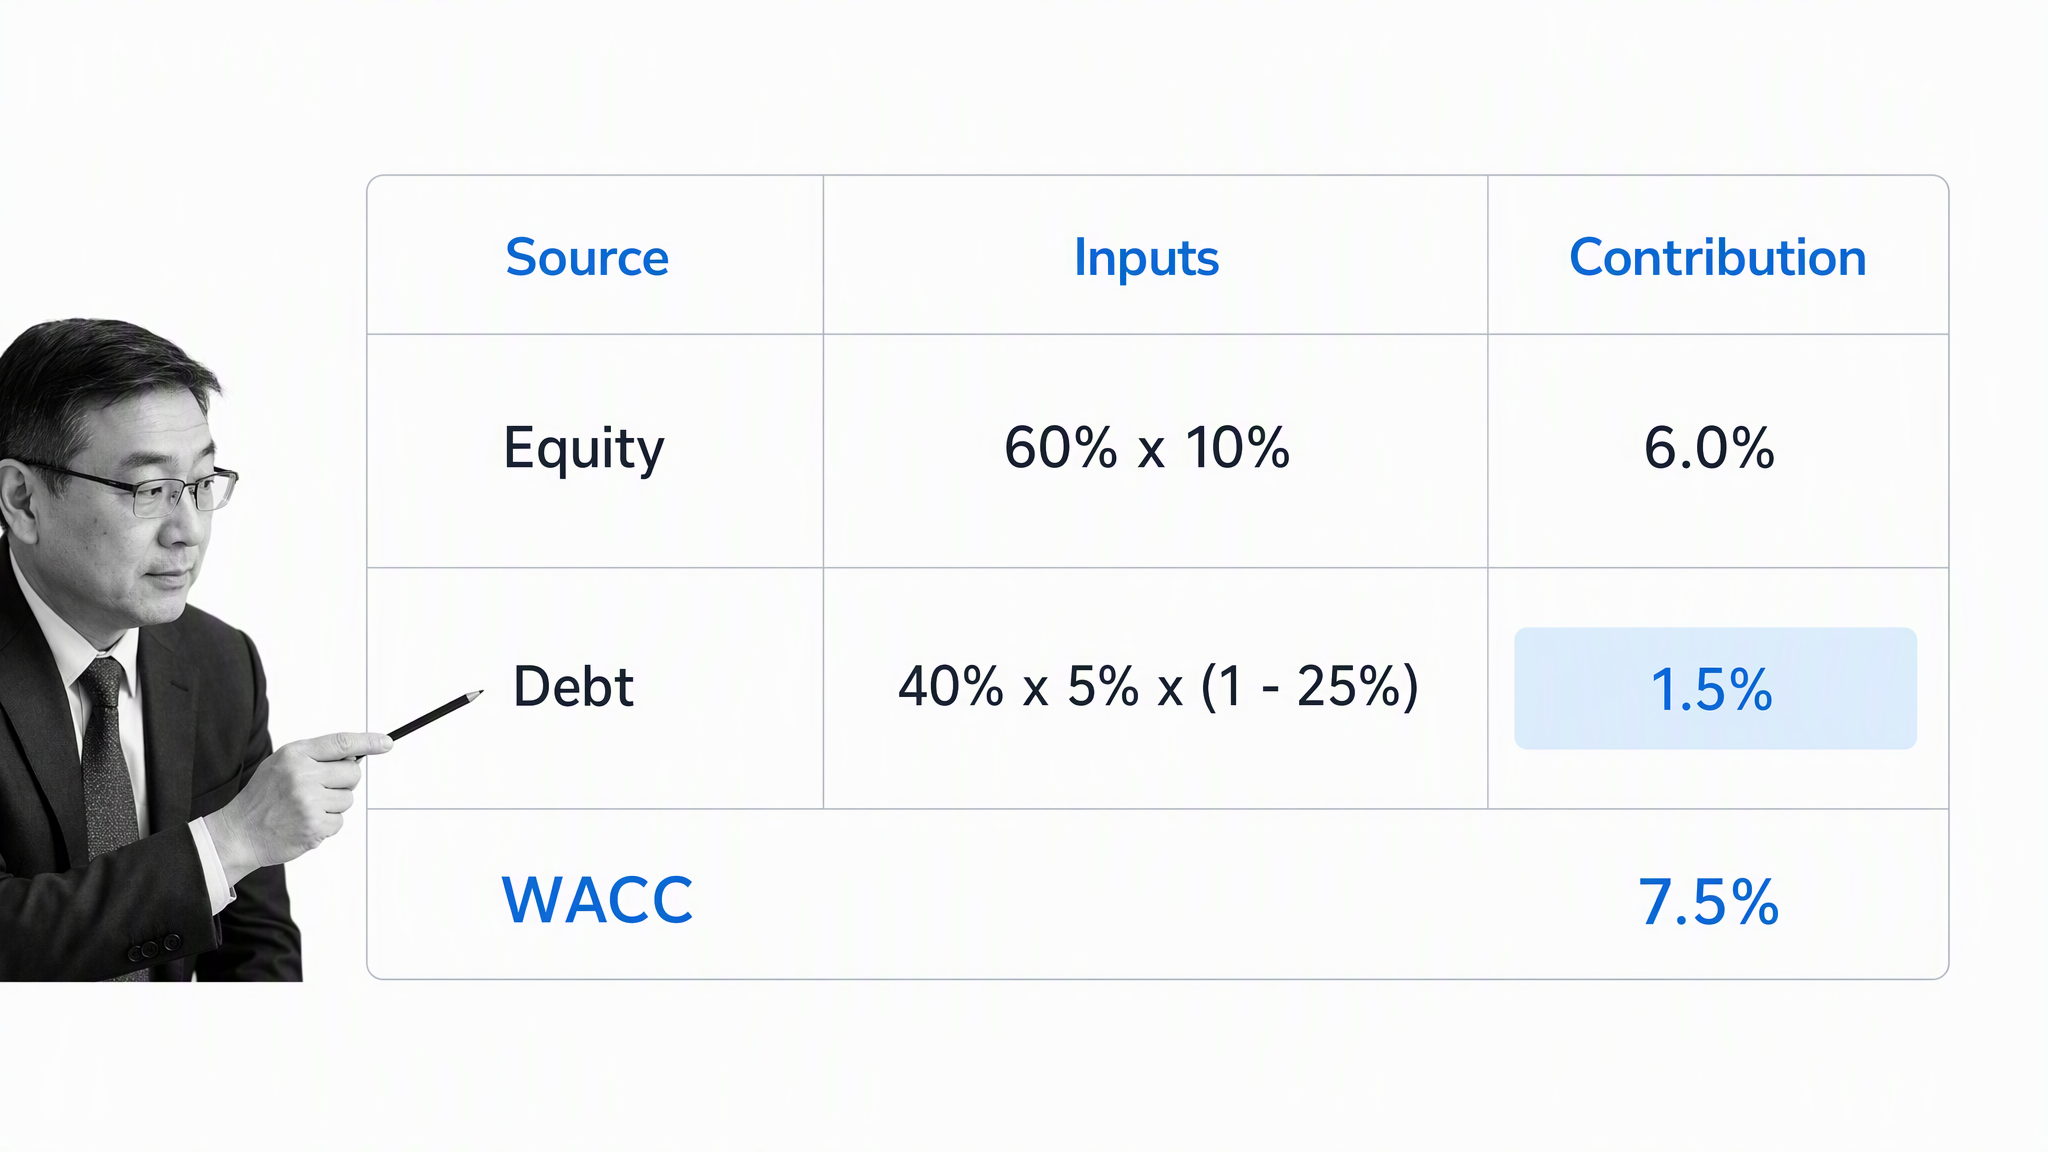
Assume an illustrative company has a market-value capital structure of 60% equity and 40% debt. Its estimated cost of equity is 10%, its pre-tax cost of debt is 6%, and its relevant tax rate is 25%.
- Weighted equity cost: 60% × 10% = 6.0%
- After-tax debt cost: 6% × (1 − 25%) = 4.5%
- Weighted debt cost: 40% × 4.5% = 1.8%
- WACC: 6.0% + 1.8% = 7.8%
This result means the blended required return implied by the assumptions is 7.8%. It does not mean every project should be approved when its forecast return exceeds 7.8%. The project’s own risk, duration, currency, and financing effects still need to be considered.
What are the components of WACC?
Cost of Equity
The cost of equity is the return shareholders require for bearing the risk of owning the company. It is not an invoice the company pays, so it must be estimated. CAPM is widely used because it separates the time value of money from systematic equity risk:
Cost of equity = Risk-free rate + Beta × Equity risk premium
Beta should reflect the business risk and financial leverage relevant to the company. Analysts often review peer betas, unlever them to isolate operating risk, and relever the result to the target capital structure. The equity risk premium should be internally consistent with the market, currency, and date of the valuation.
Cost of Debt
The cost of debt is the current return lenders require for the company’s borrowing risk. A traded bond’s yield to maturity can provide direct evidence. When debt is private or illiquid, the estimate may start with a risk-free benchmark plus a credit spread based on the borrower’s rating, leverage, coverage, collateral, and maturity.
Use the current borrowing cost rather than a historical coupon. A bond issued during a lower-rate period can carry a coupon that understates the company’s present marginal cost of debt.
Capital Structure Weights
The weights determine how much influence each financing cost has on WACC. Market-value weights are generally more relevant than book-value weights because they reflect what investors currently assign to debt and equity. Target weights can be appropriate when management has a credible, sustained capital policy that differs from the observed structure.
Tax Adjustment
The formula reduces the cost of debt for the value of deductible interest. The relevant tax rate is not always the statutory headline rate. Interest limitations, loss positions, credits, and the mix of jurisdictions can change the actual benefit. If the modeled cash flows already include a financing tax benefit, applying the WACC tax shield again would double count it.
Preferred Stock and Other Capital
Preferred stock is included when it is a material source of permanent financing. Its cost is commonly estimated as the preferred dividend divided by the current market price, then weighted by preferred stock’s share of total capital. Because preferred dividends are generally not treated like deductible interest, the preferred component usually does not receive the debt tax adjustment.
Convertible securities, leases, pensions, minority interests, and excess cash require judgment. The correct treatment depends on the purpose of the model and the cash flows being discounted. The governing principle is consistency: a claim included in enterprise value or the cash-flow forecast must be treated consistently in the capital base and the bridge to equity value.
How is WACC used?
Discounted Cash Flow Valuation
WACC is commonly used to discount unlevered free cash flow because that cash flow is available to both debt and equity providers. Discounting unlevered cash flow at WACC produces an enterprise value. Net debt and other non-operating claims are then considered when moving from enterprise value to equity value.
Capital Budgeting
Finance teams use WACC as a reference point when assessing projects, acquisitions, and major investments. A controlled capital budgeting process should document the cash-flow forecast, discount-rate rationale, sensitivity cases, approvals, and post-investment review rather than relying on one spreadsheet cell.
Performance and Value Creation
Comparing return on invested capital with WACC can help management assess whether the business is earning more than its estimated capital cost. That comparison is most useful over a meaningful period and with consistent definitions of operating profit, invested capital, and tax.
Capital Structure Decisions
WACC can clarify tradeoffs between debt and equity, but it should not be minimized mechanically. More debt may initially lower the blended cost because debt is senior and may receive a tax benefit. Beyond a point, higher leverage can increase credit risk, borrowing costs, and the return demanded by shareholders.
How does WACC differ from a required return?
WACC is one type of required return, calculated from the company’s blended financing costs. The broader term “required return” can refer to the minimum return demanded by a particular shareholder, lender, project sponsor, or asset buyer. A cost of equity estimate is therefore a required return for shareholders, while a borrowing yield is a required return for lenders.
The distinction matters because the rate must match the cash flow. Unlevered cash flow belongs to all capital providers and is commonly discounted at WACC. Cash flow to equity belongs only to shareholders and should be discounted at a cost of equity. A debt cash flow should be valued using a rate that reflects its own seniority, maturity, and default risk.
Mixing these perspectives produces misleading values. Discounting equity cash flow at WACC usually applies a rate built for a broader claim set. Discounting a high-risk project at a stable company’s WACC can understate risk. Before selecting a rate, identify who receives the cash flow, which risks drive it, and whether financing effects are already embedded.
What is a good WACC?
There is no universal “good” WACC. A lower WACC can indicate cheaper access to capital, but the number is meaningful only in context. Industry risk, business cyclicality, leverage, currency, country exposure, interest rates, and the valuation date all affect the result.
Useful comparisons include the company’s WACC across time, WACC estimates for genuinely comparable peers, and the expected return on investments with similar risk. Professor Aswath Damodaran’s industry cost-of-capital dataset illustrates why the benchmark varies across sectors rather than converging on one acceptable percentage.
A low WACC is not automatically a sign of superior performance. It may reflect a lower-risk business, favorable market conditions, a temporary capital structure, or assumptions that are too optimistic. The audit trail for the inputs matters as much as the final percentage.
What are the limitations of WACC?
A Company-Wide Rate Can Misprice Project Risk
Using one corporate WACC for every project can favor risky investments and reject safer ones. The discount rate should match the risk of the cash flows. A new market, product line, acquisition, or regulated asset may require a project-specific rate derived from relevant comparables.
Inputs Change Over Time
Risk-free rates, credit spreads, share prices, beta estimates, and capital weights move. A WACC calculated for last quarter may not represent conditions on today’s valuation date. The model needs an owner, a review cadence, and a clear rule for triggering an off-cycle update.
Private-Company Inputs Require More Judgment
Private companies do not have an observable share price or beta. Analysts usually rely more heavily on peer evidence, valuation ranges, and target capital structures. Each adjustment should be documented so a reviewer can distinguish market evidence from analyst judgment.
The Tax Shield May Be Overstated
The standard formula assumes the modeled interest benefit can be used. Deduction limits, insufficient taxable income, and jurisdiction-specific rules may reduce or delay that benefit. The tax input should align with the cash-flow model and the company’s actual ability to use deductions.
Circularity Can Enter the Model
WACC can depend on capital weights, while capital values depend on cash flows discounted at WACC. A model may need iteration or a clearly stated target structure to resolve that circularity. Hiding the loop inside a spreadsheet makes review harder, so the method should be explicit.
How do you keep WACC current?
Treat WACC as a governed finance process, not a permanent constant. Define the valuation date, source every input, record the chosen methodology, require independent review, and preserve the approved output with its supporting evidence.
Run WACC as a Controlled Finance Process
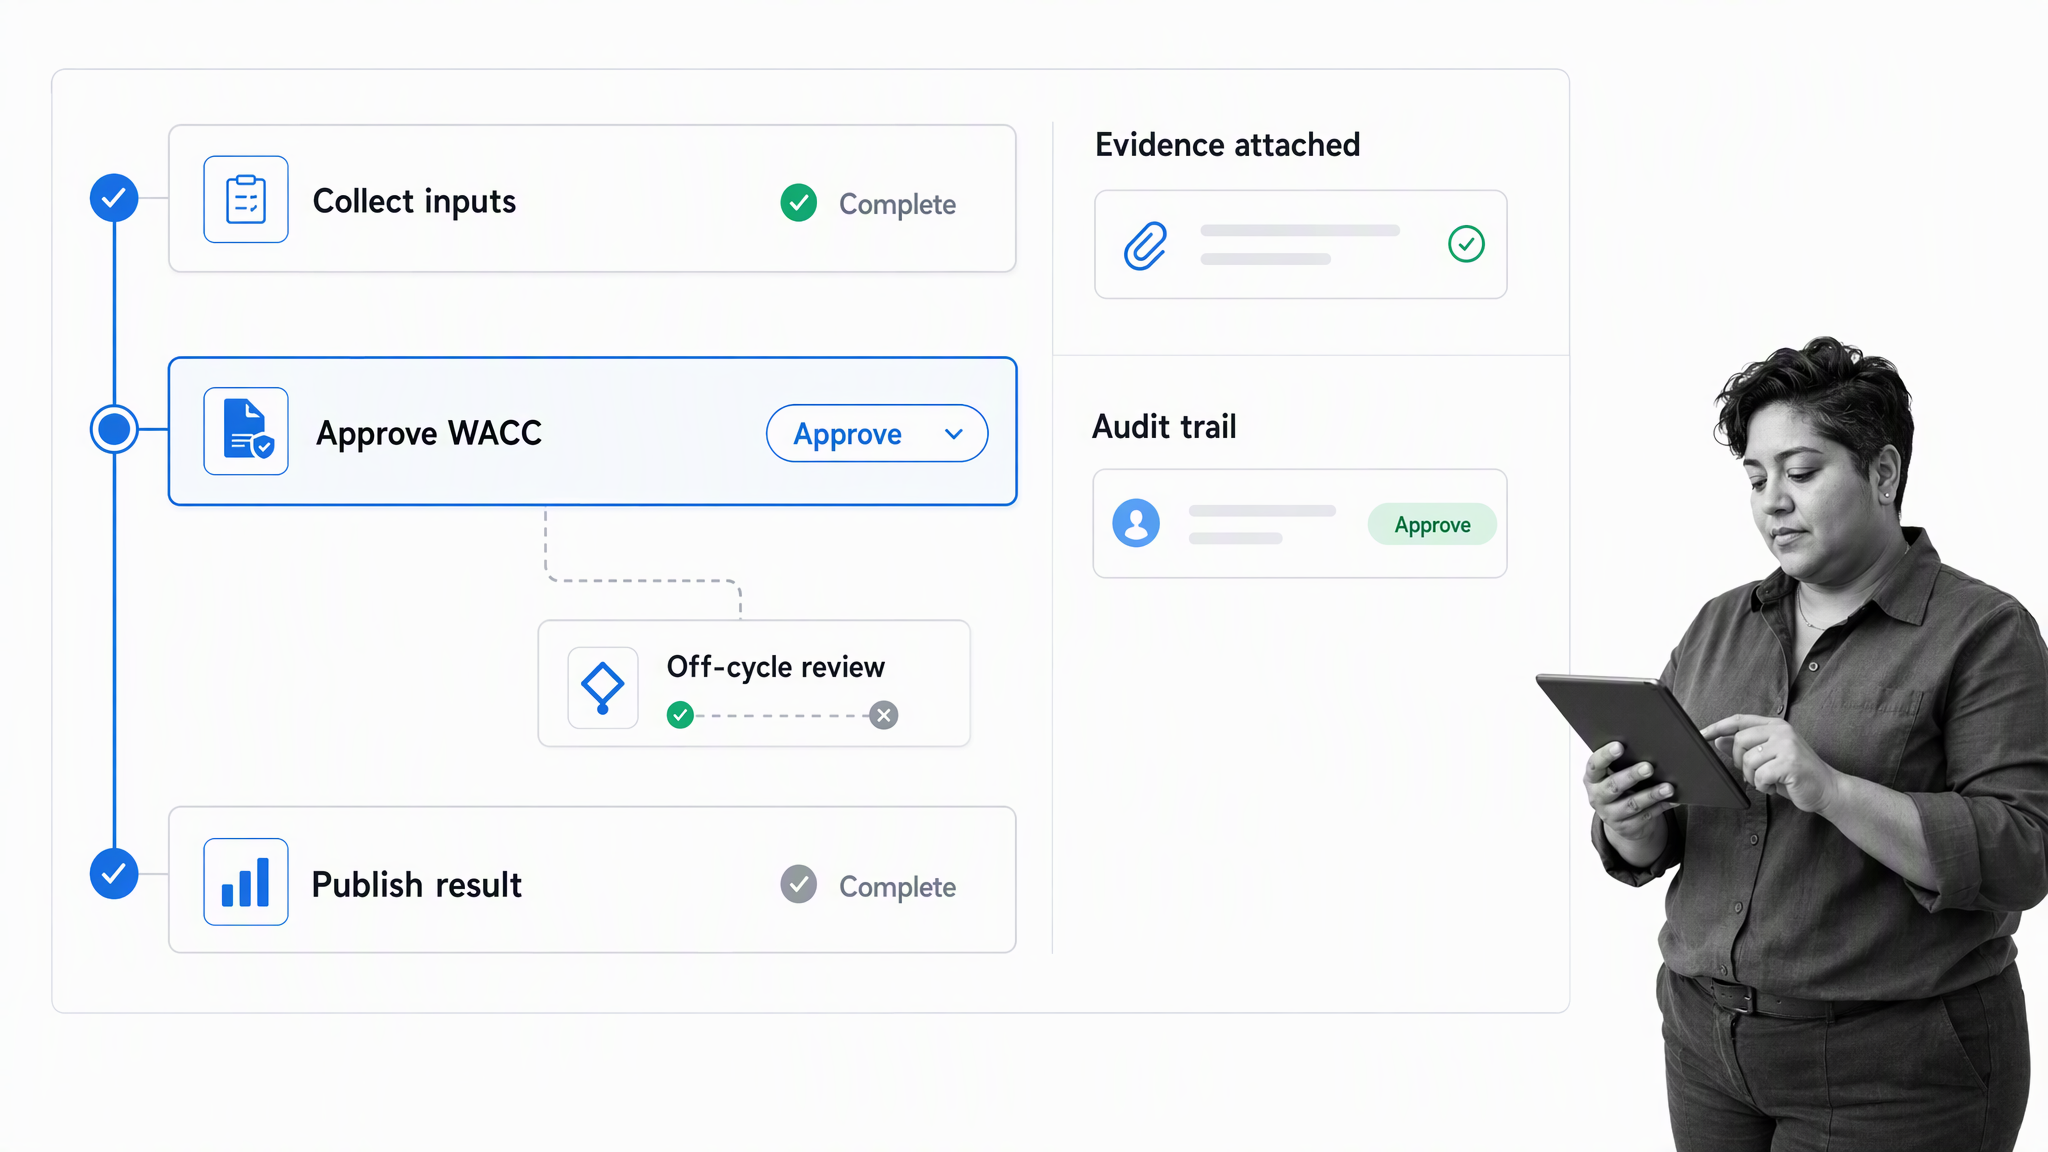
- Assign an owner. Name the finance role responsible for updating the model and collecting evidence.
- Lock the methodology. Document how market values, beta, premiums, debt costs, taxes, preferred stock, and target weights are handled.
- Capture source evidence. Store rate observations, market data, debt schedules, peer selections, and tax assumptions with the calculation.
- Route review and approval. Use a defined workflow approval process so changes cannot bypass the appropriate finance reviewers.
- Test sensitivities. Show how the result changes when the most judgment-heavy inputs move within a defensible range.
- Set update triggers. Revisit the model after major financing, a material acquisition, a significant rate move, a changed tax position, or a shift in business risk.
- Retain the decision record. Keep the approved rate, reviewer comments, exceptions, and effective date connected to the projects and valuations that use it.
Process Street can coordinate that recurring control with assigned tasks, required evidence, conditional routing, approvals, reminders, and an audit history. It complements the valuation model by governing how the inputs are gathered, reviewed, approved, and reused. The same pattern supports broader financial process automation without replacing the accounting or valuation system of record.
WACC FAQs
What does WACC mean in simple terms?
WACC is the blended return expected by the lenders and shareholders who finance a company. Each financing cost is weighted by its share of the company’s capital structure.
Why does WACC use market values instead of book values?
Market values better reflect the current economic weight and opportunity cost of each financing source. Book values record historical accounting amounts that may differ substantially from current investor values.
Is WACC the same as the required rate of return?
WACC is a blended company-level required return across debt and equity. A required rate of return can refer to the return demanded for one security, investor, project, or asset, so the terms are related but not interchangeable.
Can WACC be used as the discount rate for every project?
No. Company-wide WACC is most defensible when the project has business risk, financing characteristics, currency, and duration similar to the company’s existing operations. Other projects may need a project-specific rate.
How often should a company update WACC?
Update WACC on a defined review schedule and whenever a material change affects market rates, credit risk, capital structure, tax treatment, business risk, or the valuation date.
What is the biggest mistake in a WACC calculation?
The most damaging mistake is mismatching the discount rate and the cash flows. Other common errors include using book-value weights, stale debt costs, unsupported beta estimates, and a tax shield the company cannot use.
