


Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


What Is Comparable Company Analysis? A Practical Guide to CCA
Comparable company analysis, often called CCA, trading comps, or public comps, estimates a company’s value by comparing it with similar publicly traded businesses. The method converts market prices into valuation multiples, then applies a representative peer range to the target company’s matching financial metric.
The arithmetic is straightforward. The judgment is not. A credible result depends on selecting genuinely comparable companies, aligning the financial periods, normalizing unusual items, matching enterprise value with enterprise-level metrics and equity value with equity-level metrics, and explaining why the target belongs above, below, or near the peer benchmark.
This guide shows how to build a defensible comparable company analysis from the research question through the final valuation range. It also explains where the method breaks down and how to turn the analysis into a repeatable review process.
- What is comparable company analysis?
- When should you use comparable company analysis?
- What data do you need?
- How do you perform comparable company analysis?
- Which valuation multiples should you use?
- How should you interpret the results?
- What are the limitations?
- How can you make the process repeatable?
- Frequently asked questions
What is comparable company analysis?
Comparable company analysis is a relative valuation method. Instead of forecasting every future cash flow and discounting those cash flows to the present, the analyst asks how the market currently values businesses with similar economics. If similar companies trade within a consistent range of value relative to revenue, EBITDA, earnings, book value, or another driver, that range can inform the target company’s implied value.
The CFA Institute’s market-based valuation material distinguishes price multiples from enterprise-value multiples and explains that peer medians or averages can serve as benchmarks. That distinction matters because the numerator and denominator must refer to the same claimholders. Enterprise value belongs with revenue, EBITDA, or other operating measures available to debt and equity holders. Equity value belongs with net income, book equity, or per-share measures available to common shareholders.
CCA produces an implied range, not an objective truth. Market prices can reflect optimism, fear, temporary sector rotations, different accounting choices, and information that is difficult to isolate. The method is most useful when its assumptions are visible and when another valuation approach can challenge the conclusion.
When should you use comparable company analysis?
Use comparable company analysis when the target has a meaningful set of publicly traded peers and the available financial information can be made reasonably consistent. It is common in investment banking, equity research, corporate development, private equity, strategic planning, and fairness analysis because it is fast to update and grounded in observable market values.
- Valuation cross-check: compare the result of a discounted cash flow model, transaction analysis, or asset-based method with current public-market pricing.
- Transaction preparation: establish an initial valuation range before a financing, acquisition, divestiture, or strategic review.
- Performance benchmarking: identify how growth, margins, returns, or leverage differ from peers and whether those differences explain a premium or discount.
- Investor communication: understand the peer set and metrics that market participants may use when discussing valuation.
- Scenario testing: observe how the implied value changes when the peer group, time period, or selected multiple changes.
CCA is less persuasive when the target has a novel business model, operates across unrelated segments, has unstable or negative financial metrics, or sits in a market with very few public peers. In those cases, widen the evidence base rather than forcing a weak peer group to produce a precise answer.
What data do you need for a comparable company analysis?
Start with source documents that let every figure be traced. Annual reports, quarterly reports, earnings releases, investor presentations, and reliable market data are common inputs. Record the filing date, reporting period, currency, share count convention, and source location beside each data point. A comps table without provenance is difficult to review and even harder to update.
For US public companies, the SEC’s EDGAR search system is the primary filing source. When data is collected programmatically, the SEC also documents XBRL company facts and submissions APIs. Whatever the collection method, read the underlying filing when a value looks unusual. Structured data speeds collection but does not remove the need to understand the accounting.
A practical data set usually contains four groups of information:
- Market data: share price, diluted shares outstanding, market capitalization, debt, preferred equity, non-controlling interests, cash, and investments needed to bridge to enterprise value.
- Operating data: revenue, EBITDA or another defined operating profit measure, EBIT, net income, free cash flow, and sector-specific operating metrics when relevant.
- Forward estimates: consistent consensus periods for revenue, EBITDA, earnings, or other denominators when forward multiples are part of the analysis.
- Comparison drivers: growth, margins, returns, leverage, customer or product concentration, geography, capital intensity, and other factors that may explain valuation dispersion.
Keep the valuation date consistent. Market capitalization can change every trading day while financial statements update quarterly. Mixing market values from one date with denominators from unrelated periods creates noise that looks like insight.
How do you perform comparable company analysis step by step?
1. Define the valuation question and target metric
Write down the decision the analysis must support. Are you estimating enterprise value, equity value, or value per share? Is the target profitable? Is the business best understood through revenue, cash flow, book value, or a sector-specific operating measure? Defining the question first prevents the spreadsheet from becoming a collection of ratios without a clear purpose.
Set the valuation date and the periods you will use, such as trailing results, forward estimates, or both. Decide how you will treat currency conversion, non-calendar fiscal years, leases, minority interests, and unusual securities before collecting the peer data.
2. Build a defensible peer group
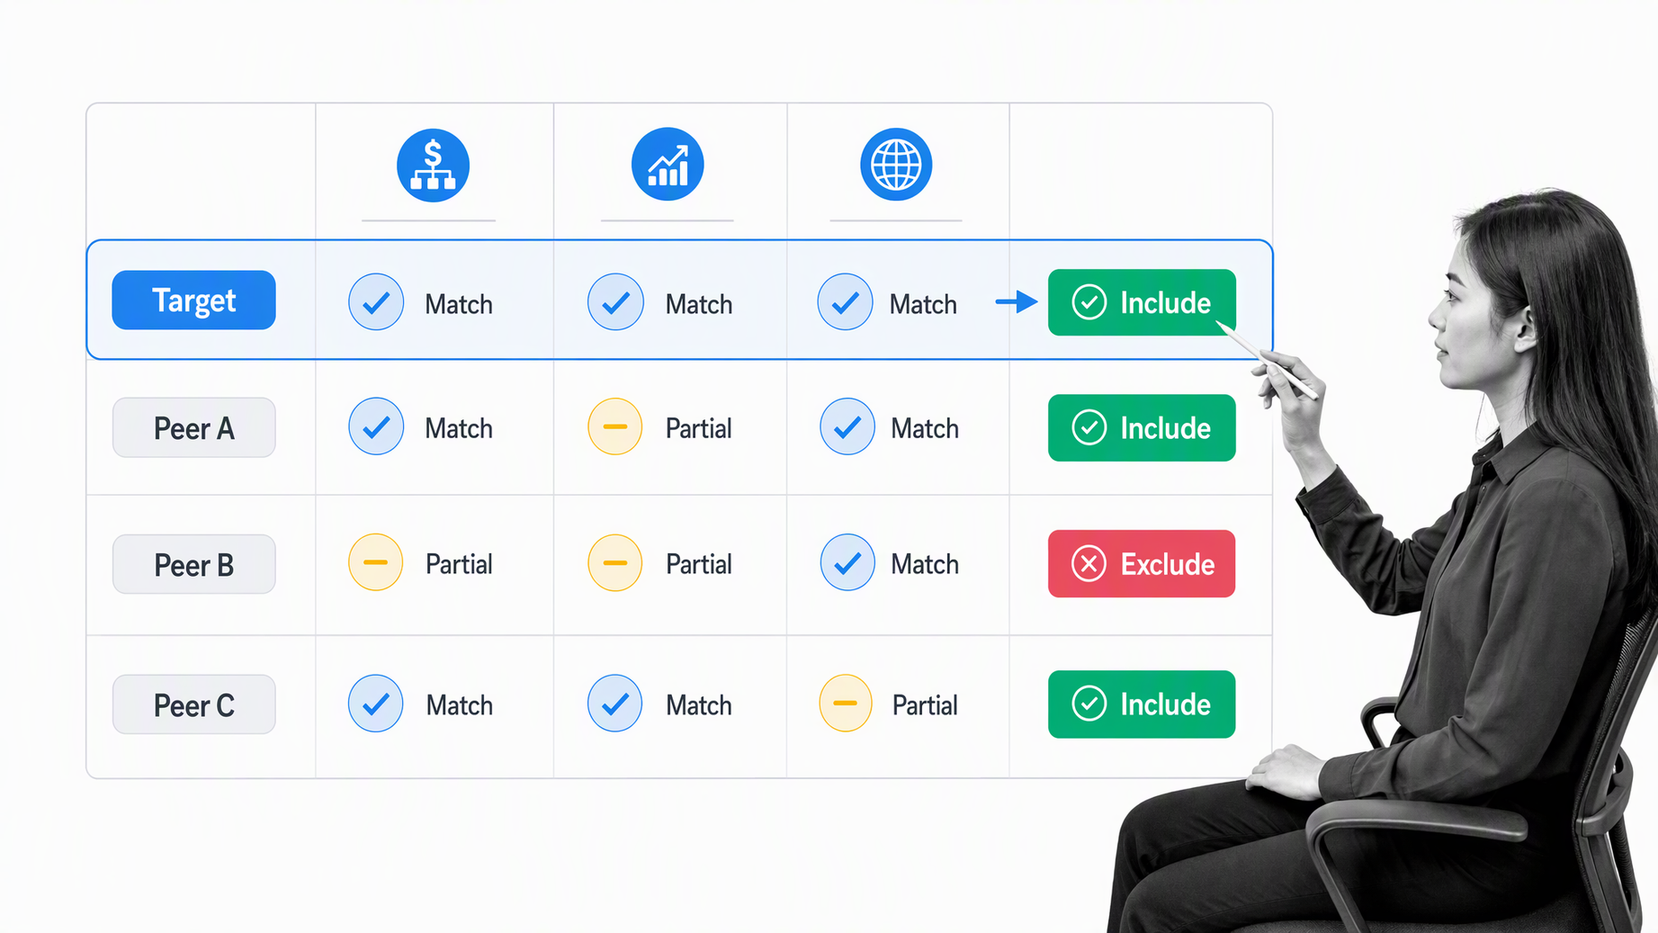
Begin with business-model similarity, not a broad industry label. Strong peers serve similar customers, earn revenue in similar ways, face comparable cost structures, and respond to similar economic drivers. Then examine size, growth, margins, geography, capital intensity, leverage, and risk. Two companies in the same sector may deserve very different multiples if one is a high-growth subscription business and the other is a low-margin distributor.
Create an inclusion and exclusion log before reviewing the final valuation range. That simple control reduces hindsight bias. It also gives reviewers a clear answer when they ask why a familiar company is missing or why a less obvious company belongs in the set.
3. Collect market and financial data
Gather each input from a traceable source and label whether it is reported, adjusted, estimated, or calculated. Use the same definitions across the group. If one company reports an adjusted profit measure that excludes items another company includes, either reconcile the definitions or use a denominator that is more comparable.
Build explicit source checks into the work. A reviewer should be able to move from a multiple to its numerator and denominator, then from each input to the filing or data source. A financial due diligence checklist can help structure the collection and verification work when several analysts contribute.
4. Normalize the financial information
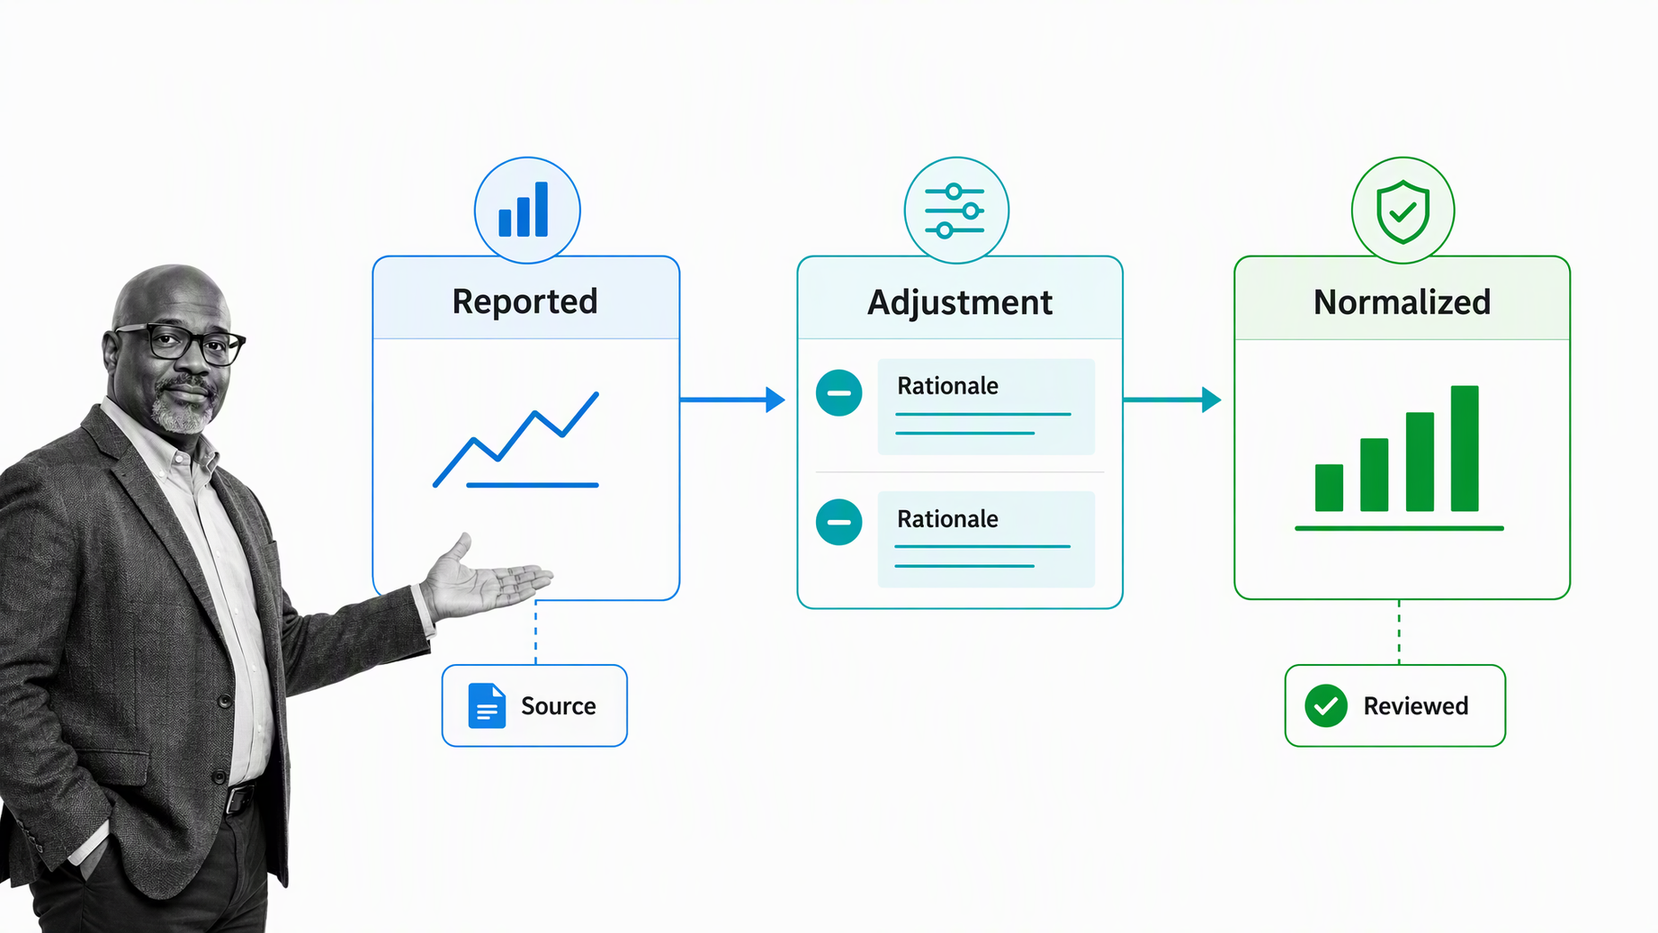
Normalization improves comparability by removing differences that do not reflect ongoing economics. Common review items include one-time restructuring costs, unusual gains or losses, discontinued operations, inconsistent fiscal periods, acquisitions, accounting-policy differences, and temporary working-capital effects. The goal is not to manufacture a preferred result. It is to make the denominator mean the same thing across the group.
Document every adjustment with its source and rationale. Preserve both reported and adjusted values so a reviewer can see the bridge. If a normalization relies heavily on judgment, present the analysis with and without it.
5. Calculate equity value and enterprise value
Equity value represents the market value attributable to common shareholders. Enterprise value expands the view to the operating business by incorporating claims such as debt and preferred equity, then subtracting cash and cash-like items under the chosen convention. The exact bridge can vary with the company’s capital structure, so list every component rather than hiding the calculation in a single cell.
This bridge is where many silent errors occur. Verify diluted shares, convertible securities, options, leases, investments, pension items, and non-controlling interests when they are material. Consistency across peers matters as much as sophistication in any one calculation.
6. Calculate the trading multiples
Calculate only multiples that fit the target and peer set. An enterprise-value numerator should pair with a pre-interest operating denominator. An equity-value numerator should pair with a post-interest measure attributable to equity holders. Use identical trailing or forward periods across every peer.
Aswath Damodaran’s relative P/E material emphasizes a basic but frequently missed rule: the earnings definition must be consistent between the company and the benchmark. The same discipline applies to every multiple. A clean label should state the numerator, denominator, and period rather than using a vague shorthand.
7. Analyze the distribution and select a benchmark range
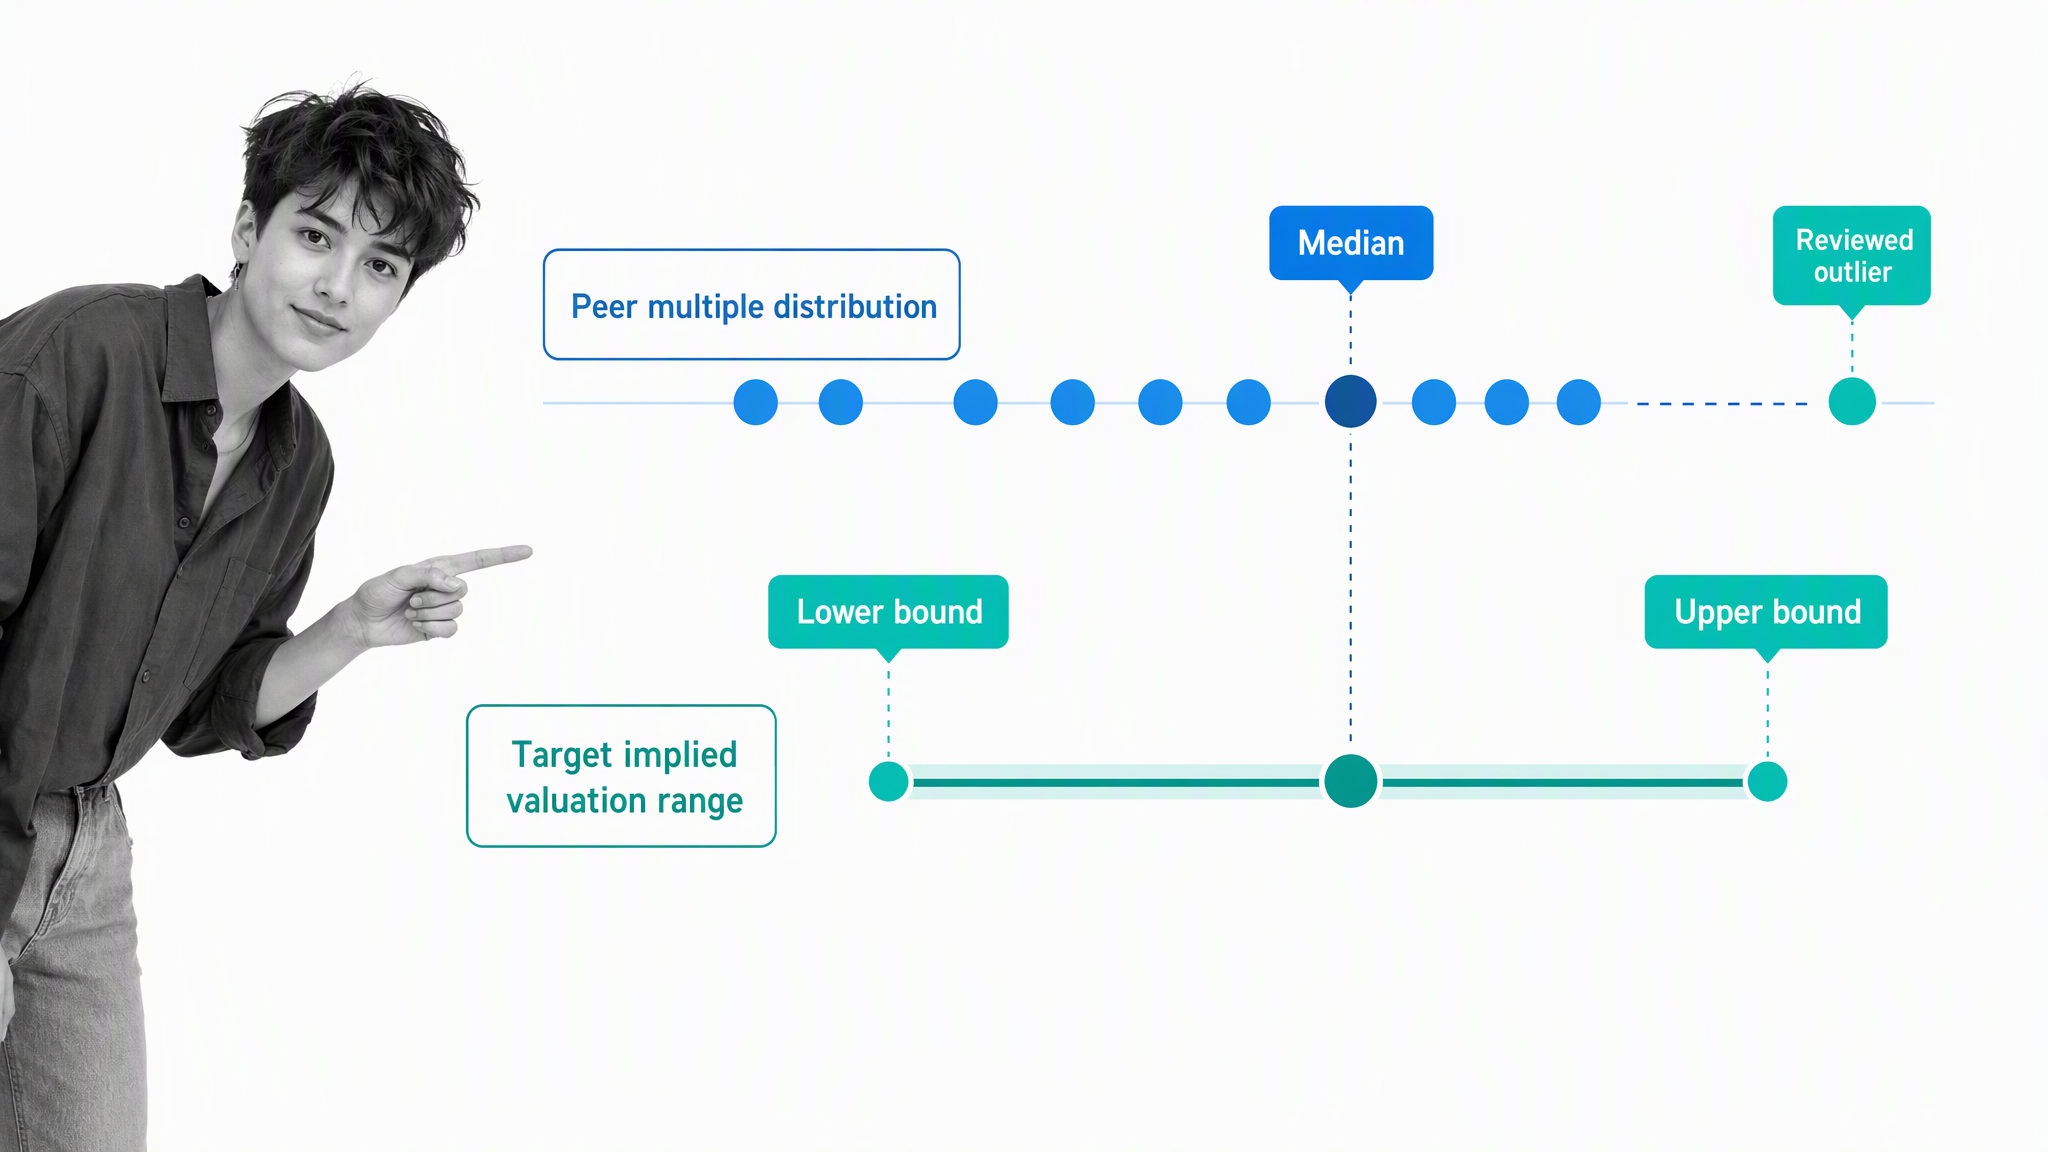
Review the minimum, lower quartile, median, upper quartile, and maximum, but do not let summary statistics replace judgment. Investigate outliers. A very high multiple may reflect exceptional growth, a depressed denominator, an acquisition rumor, or a data error. A very low multiple may reflect distress, concentration risk, litigation, weak governance, or a cyclical trough.
The median often provides a useful center because it is less affected by extremes than the mean. The final benchmark may still place more weight on the closest peers or use a range that reflects the target’s growth, profitability, risk, and strategic position. Write down the reason for that choice.
8. Apply the range and reconcile the result
Apply the selected enterprise-value multiple to the target’s corresponding operating metric to estimate enterprise value, then bridge to equity value under the same convention used for peers. Apply an equity-value multiple directly to the matching equity metric when that is the chosen approach. Use a range of multiples so the output remains a range of implied values.
Reconcile the result with the target’s fundamentals and other valuation methods. If the implied range conflicts with a discounted cash flow analysis or precedent transaction analysis, identify the reason instead of averaging the numbers automatically. The disagreement may reveal different growth assumptions, market sentiment, control value, synergies, or a problem in the peer set.
Which valuation multiples should you use?
Choose the multiple that best matches how the business creates value and how reliably the denominator can be compared. Using several sensible multiples can expose where one metric is distorted, but adding every available ratio does not improve the analysis.
| Multiple | Value basis | Often useful when | Watch for |
|---|---|---|---|
| EV/Revenue | Enterprise value | Profitability is limited or margins are still scaling | Large margin differences, revenue recognition, business-model mix |
| EV/EBITDA | Enterprise value | Operating profitability is positive and broadly comparable | Capital intensity, lease treatment, adjusted EBITDA definitions |
| EV/EBIT | Enterprise value | Depreciation reflects meaningful asset use | Different depreciation policies and asset ages |
| P/E | Equity value | Net income is positive and capital structures are comparable | Leverage, tax differences, unusual earnings, negative income |
| Price-to-book | Equity value | Book capital is economically meaningful, often in financial businesses | Asset quality, accounting marks, different return profiles |
| Price-to-cash-flow | Equity value | Cash generation is more informative than accounting earnings | Working-capital volatility and inconsistent cash-flow definitions |
Sector-specific measures can be useful when they capture the economics better than general accounting metrics. The burden is higher, however, because operating metrics may not be standardized. Define the metric, confirm how every company reports it, and avoid combining superficially similar numbers that measure different things.
The Corporate Finance Institute’s comps guide provides a useful overview of building a comps table, while the deeper analytical task is explaining why the selected multiple should track the target’s growth, risk, margins, and reinvestment needs.
How should you interpret comparable company analysis results?
Treat the output as an evidence-based range. A target may deserve a premium when it has stronger growth, better margins, more durable revenue, lower risk, superior returns on capital, or a more attractive strategic position. It may deserve a discount when it has weaker economics, higher concentration, less liquidity, greater execution risk, or poorer governance. Every premium or discount should connect to an observable difference rather than a vague quality label.
Separate market information from analytical judgment. The peer multiples report how the market prices the group on the valuation date. The selected benchmark and target positioning express the analyst’s view of comparability. Keeping those layers distinct makes the conclusion easier to challenge and update.
Run sensitivity cases. Compare a broad peer group with a narrower closest-peer subset. Compare trailing and forward periods. Show the effect of including and excluding disputed adjustments. Sensitivity does not weaken the analysis. It reveals which assumptions drive the answer.
What are the limitations of comparable company analysis?
- No company is perfectly comparable. Differences in products, geography, scale, growth, margins, capital intensity, management, and risk always remain.
- Market mispricing carries through. If the entire peer group is unusually expensive or cheap, a relative valuation can reproduce that market condition.
- Peer selection can be biased. Adding or removing companies after seeing the result can turn the method into support for a predetermined conclusion.
- Accounting is not uniform. Reported and adjusted metrics may differ in definition even when the labels look identical.
- Negative denominators break some multiples. P/E and EV/EBITDA may be meaningless for loss-making companies, which can force the analysis toward revenue or sector-specific measures.
- Public and private companies differ. Liquidity, disclosure, governance, scale, and access to capital can make public peers imperfect benchmarks for a private target.
- The answer changes with the market. A comps analysis is tied to a valuation date and should be updated when prices, estimates, filings, or business conditions change materially.
A detailed trading comps tutorial from Wall Street Prep similarly emphasizes that operational and financial comparability drive peer selection. The practical response to the method’s limitations is transparency: show the source data, peer rationale, adjustments, outliers, sensitivities, and cross-checks.
How can you build a repeatable comparable company analysis workflow?
A valuation model is only one part of the process. The work also involves source collection, peer decisions, adjustment review, approval, version control, and periodic updates. Turn those activities into an explicit workflow so the analysis can be reproduced after the team, market, or source data changes.
- Define the valuation date, purpose, owner, reviewer, and required output.
- Record peer inclusion and exclusion criteria before calculating the final range.
- Assign source collection with required links and period labels for every input.
- Require a documented bridge for each normalization and enterprise-value adjustment.
- Add quality checks for numerator-denominator consistency, period alignment, currency, formulas, and outliers.
- Route the peer set, adjustments, and selected range through review and approval.
- Store the final output with assumptions, sources, unresolved questions, and the next update trigger.
A structured investment due diligence workflow can coordinate source gathering and review. In Process Street, approval tasks can route selected work to a reviewer for approval or rejection with comments, as described in the official approvals documentation. That turns analytical judgment into a visible control instead of leaving it inside an emailed spreadsheet.
The most useful template is not merely a blank comps table. It is a controlled sequence that makes the analysis traceable: question, peer criteria, sources, adjustments, calculations, outlier review, sensitivity, approval, and final range. For a high-stakes valuation process, request a Process Street demo and bring the actual review path, evidence requirements, and approval points you need to enforce.
Frequently asked questions about comparable company analysis
What is comparable company analysis in simple terms?
Comparable company analysis estimates a company’s value by examining how the market values similar public companies. The analyst selects a defensible peer group, calculates consistent valuation multiples, and applies a representative peer range to the target company’s matching financial metric.
Which valuation multiples are used in comparable company analysis?
Common enterprise-value multiples include EV/Revenue and EV/EBITDA. Common equity-value multiples include P/E and price-to-book. The right multiple depends on the business model, sector, profitability, capital structure, and the reliability of the denominator.
How do you choose comparable companies?
Start with companies that share the target’s business model, customers, revenue drivers, geography, and industry economics. Then compare size, growth, margins, capital intensity, leverage, and risk. Record why each peer is included or excluded before reviewing the valuation outcome.
Why use the median multiple instead of the average?
The median is often less sensitive to unusually high or low peer multiples. Analysts should still inspect every outlier, because a data error, negative denominator, unusual capital structure, or genuinely different growth profile may explain the dispersion.
Can comparable company analysis value a private company?
Yes, but the result needs more judgment. Public peers may differ in liquidity, scale, disclosure quality, access to capital, and governance. A private-company valuation should document those differences and use other valuation methods as cross-checks rather than treating public trading multiples as a complete answer.
What is the difference between trading comps and precedent transactions?
Trading comps use the current market values of similar public companies. Precedent transactions use prices paid in completed acquisitions. Transaction values may include control premiums and deal-specific synergies, so the two methods answer related but different questions.
