


Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Why Form ADV Is Important for Investment Advisors
Form ADV is the central registration and disclosure filing for investment advisers in the United States. It tells regulators how an advisory business operates and gives investors a public record of the firm’s services, fees, conflicts, ownership, disciplinary history, and key personnel.
The form is not a single document with one audience. Its structured filing, narrative brochure, brochure supplements, and relationship summary serve different purposes. A dependable Form ADV process therefore needs more than accurate answers. It needs clear ownership, source evidence, legal and compliance review, controlled submission, and a repeatable amendment cycle.
This guide is educational and does not provide legal or regulatory advice. Registration obligations can depend on the adviser’s business, assets, clients, affiliations, and states of operation. Use the current Form ADV instructions and qualified counsel when deciding what a firm must file or disclose.
- What is Form ADV?
- Why is Form ADV important?
- Who files Form ADV?
- What does each part of Form ADV disclose?
- When must Form ADV be updated?
- How do you access Form ADV?
- How do you file Form ADV?
- How can Process Street support Form ADV operations?
- What belongs on a Form ADV review checklist?
- Form ADV FAQs
What is Form ADV?
The Investor.gov Form ADV overview defines Form ADV as the uniform form investment advisers use to register with the Securities and Exchange Commission and state securities authorities. The filing also supplies disclosures that regulators and the public can use to understand the adviser and its business.
Form ADV should be treated as a system of connected disclosures. Part 1 captures structured information. Part 2 contains narrative brochures for clients. Part 3 provides a concise relationship summary for covered retail relationships. Schedules and disclosure reporting pages add detail where the form calls for it.
Form ADV is both a filing and a public disclosure system
For the advisory firm, Form ADV is part of registration and ongoing regulatory maintenance. For regulators, it supports oversight, risk assessment, and examinations. For clients and prospects, it provides a way to compare what a firm says about its services, fees, conflicts, disciplinary information, and people with the relationship being offered.
That dual purpose shapes the writing standard. A technically complete filing can still create risk if it is inconsistent, difficult to understand, unsupported by source records, or out of step with the firm’s actual practices. The strongest process verifies both regulatory completeness and operational truth.
Form ADV parts at a glance
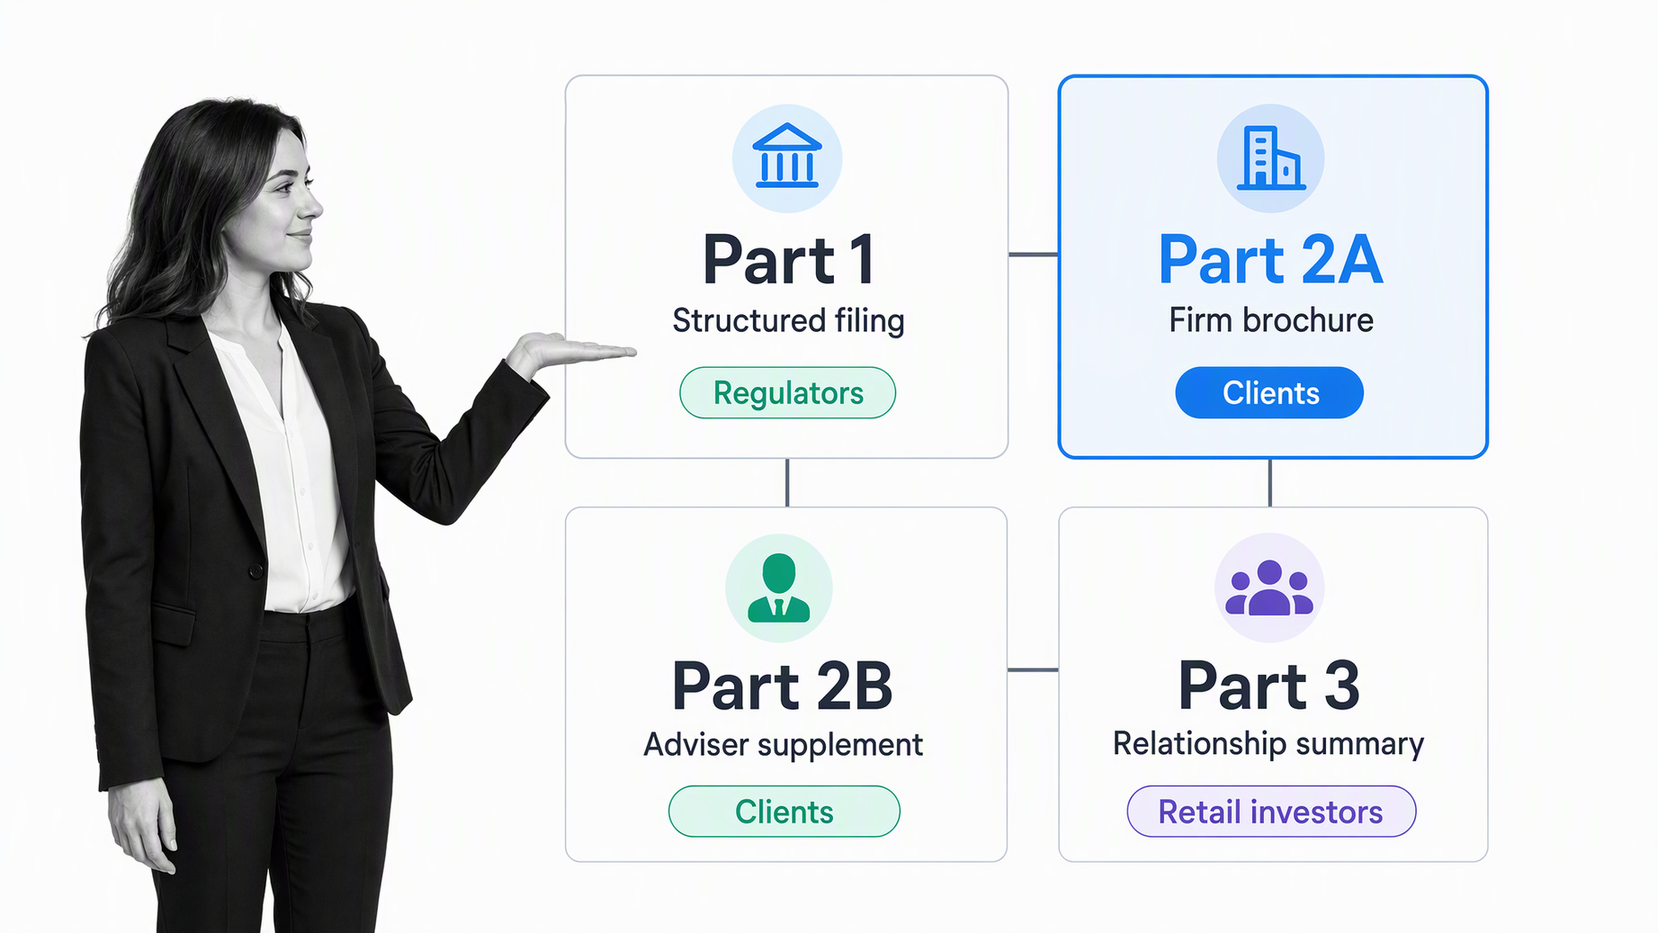
- Part 1: Structured information about the adviser, its business, ownership, clients, employees, affiliations, practices, and disciplinary events.
- Part 2A: The firm brochure, written in narrative form for clients and prospects.
- Part 2B: Brochure supplements about certain supervised persons who provide advisory services.
- Part 3: The relationship summary, commonly called Form CRS, for covered SEC-registered advisers serving retail investors.
Why is Form ADV important?
It gives regulators a consistent record
A uniform filing lets the SEC and state securities authorities collect comparable information from advisory firms. The record can show who controls the firm, where it operates, what clients it serves, what services it provides, what affiliations or business practices may create risk, and whether disciplinary disclosures apply.
Form ADV operates within the broader framework of the Investment Advisers Act of 1940 and applicable state law. The filing does not replace the underlying rules. It is one of the mechanisms through which an adviser represents its eligibility, organization, practices, and disclosures to regulators.
It helps investors evaluate an adviser
An investor can use Form ADV to understand the services an adviser offers, how the adviser describes fees and compensation, which conflicts may affect recommendations, who owns or controls the firm, whether disciplinary events are disclosed, and which individuals provide advice. The filing is most useful when read alongside the advisory agreement and direct questions to the firm.
Form ADV is not a scorecard and it does not tell an investor which adviser is best. It provides a disclosure record. Investors still need to consider fit, cost, investment approach, custody arrangements, conflicts, experience, and the quality of the answers they receive.
It forces the firm to reconcile policy with practice
Preparing the filing exposes operational gaps. A brochure may describe a fee process that the billing system does not follow. Ownership records may not match the organizational chart. A disciplinary response may depend on incomplete personnel records. Marketing language may imply services that the advisory agreement does not support.
A controlled review process brings compliance, legal, finance, operations, and business owners together before submission. Each answer should have an owner and supporting evidence, and every narrative disclosure should reflect how the firm actually operates.
Who files Form ADV?
Investment advisers use Form ADV when applying for registration with the SEC or one or more state securities authorities. Certain exempt reporting advisers also submit specified portions of Part 1A. The correct filing path depends on the firm’s facts and applicable law, so a firm should not decide its registration status from a generic asset threshold or a copied checklist alone.
SEC-registered and state-registered advisers
Both SEC and state registration use Form ADV, but the applicable items, notice filings, fees, and state-specific obligations may differ. Part 1B applies to state-registered advisers where required. State regulators can also impose brochure, financial, bonding, or amendment requirements that are not identical across jurisdictions.
The NASAA Form ADV resource provides the uniform form materials used by state securities authorities, including Part 1, Part 2 instructions, and related guidance. Firms should pair those materials with the rules of each relevant state.
Exempt reporting advisers
An exempt reporting adviser is not completing the same registration application as a registered investment adviser, but it may still need to file designated Form ADV items and keep those reports current. The filing type selected in IARD matters because an initial report, registration application, annual updating amendment, and other-than-annual amendment are not interchangeable.
When the firm’s status changes, the workflow should trigger a fresh legal analysis rather than reusing the prior year’s assumptions. Changes in business activities, clients, private fund relationships, ownership, assets, or jurisdictions can affect the filing path.
What does each part of Form ADV disclose?
Form ADV Part 1
Part 1 is primarily structured data. It asks about identifying information, registration status, organization, successions, other business activities, financial industry affiliations, private funds, advisory activities, clients, employees, assets, custody, participation in client transactions, and disciplinary information. Schedules and disclosure reporting pages collect supporting detail.
Because answers connect across items and schedules, a change in one part of the firm can affect several responses. A new affiliate may affect ownership, business activities, conflicts, private fund reporting, and brochure language. The review should test connected answers, not treat every field as an isolated question.
Form ADV Part 2A: the firm brochure
Part 2A explains the advisory firm in narrative form. It addresses services, fees and compensation, performance-based fees, types of clients, methods of analysis, disciplinary information, other financial activities, codes of ethics, brokerage practices, account review, client referrals, custody, investment discretion, voting, and financial information where applicable.
Plain English matters because the brochure is written for clients and prospects, not only regulators. A good brochure names the conflict, explains why it matters, and describes how the firm addresses it. Generic language can obscure the practical effect of a business practice and create inconsistency with contracts or marketing material.
Form ADV Part 2B: brochure supplements
Part 2B provides information about certain supervised persons who formulate investment advice and have direct client contact, or who exercise discretionary authority over client assets. The supplement can cover educational background, business experience, disciplinary information, other business activities, additional compensation, and supervision.
Personnel changes should therefore connect to the Form ADV process. Hiring, promotion, role changes, new outside business activities, disciplinary events, and departures can create review triggers. A strong process routes those events to compliance instead of waiting for the annual cycle.
Form ADV Part 3: Form CRS
Part 3 is the relationship summary for SEC-registered investment advisers that offer services to retail investors. It presents specified information about relationships and services, fees and costs, conflicts, standard of conduct, legal and disciplinary history, and questions a retail investor may ask.
The relationship summary is brief, but it should agree with the more detailed brochure, advisory agreement, fee schedule, disciplinary responses, and client experience. Concision does not reduce the need for cross-document review.
When must Form ADV be updated?
Annual updating amendments
Under Rule 204-1 in the Electronic Code of Federal Regulations, an SEC-registered investment adviser must amend Form ADV at least annually within 90 days after the end of its fiscal year. The annual review should cover the entire filing, related schedules, brochure changes, and the firm’s current eligibility for registration.
A calendar reminder is only the first control. The workflow should start early enough to collect data, resolve inconsistencies, complete legal and compliance review, obtain executive certifications where required by policy, fund the IARD account where needed, run validation, and submit before the deadline.
Other-than-annual amendments
The Form ADV General Instructions identify which information must be amended promptly and which information may be updated through the annual process. Firms should use the current instructions because amendment obligations vary by item and can also be affected by state law.
Build event triggers around the facts that can make a filing inaccurate. Common triggers include changes to legal name, principal office, contact information, ownership, control, affiliates, business activities, custody, disciplinary information, private funds, fee practices, client types, and supervised persons. The trigger should open a review, not assume that every change produces the same amendment.
Brochure delivery and record coordination
Filing and delivery are related but distinct responsibilities. A firm may need to file an amended brochure, deliver an updated brochure or summary of material changes, update the relationship summary, or maintain evidence of delivery. The correct action depends on the change, the firm’s registration, the client relationship, and the applicable rule.
Keep the filed version, client-delivery version, approval record, effective date, and evidence of distribution connected. That record helps the firm answer what changed, who approved it, when it became effective, and which clients received the applicable disclosure.
How do you access Form ADV?
Search the IAPD database
The public can search the Investment Adviser Public Disclosure database by firm or individual. The record may show registration status, current Form ADV filings, relationship summaries, professional background, employment history, and disciplinary disclosures.
Investor.gov explains that the IAPD database contains registration documents filed electronically through IARD. Certain personal identifying information is not public, but the database is the main public access point for adviser disclosure records.
Read the filing as a connected record
Start with the relationship summary or brochure for a readable overview, then use Part 1 to confirm structured facts. Compare the services, fees, conflicts, owners, affiliates, disciplinary information, and supervised persons across the documents. Differences are not automatically wrongdoing, but they are reasons to ask focused questions.
Look at the filing date and amendment history. A current filing can still describe a complex business, and an older document may have been superseded. Save the version relied on for a due diligence decision so the review record remains reproducible.
How do you file Form ADV?
Form ADV is filed electronically through IARD. The exact sequence depends on whether the firm is submitting an initial application, an exempt reporting adviser report, an annual updating amendment, or an other-than-annual amendment.
1. Confirm entitlement and filing type
Confirm the firm and authorized users have the correct IARD entitlement. Select the filing type only after confirming the firm’s regulatory status and the purpose of the submission. Choosing the wrong amendment type can create a deficiency even if the underlying information is complete.
2. Build the filing workflow in IARD
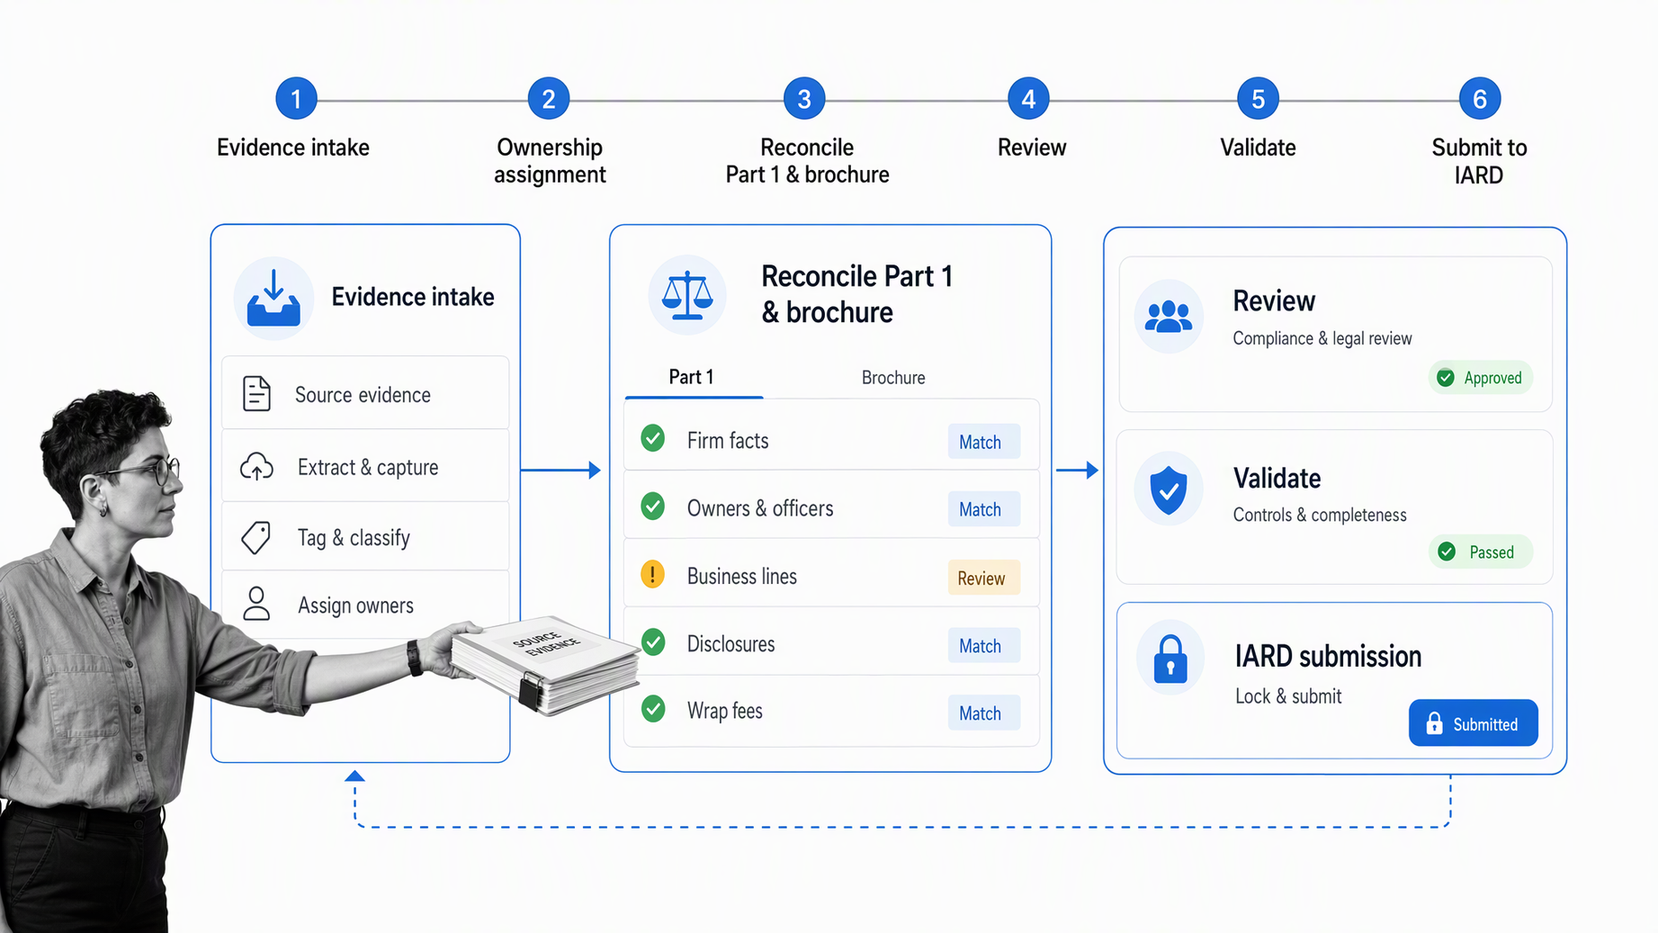
Create an item-level work plan before data entry. Assign each Form ADV item, schedule, brochure section, supplement, and relationship summary section to the person who owns the underlying information. Identify the source record and reviewer for each response.
- Corporate records for legal name, offices, ownership, control, and affiliates.
- Finance and portfolio records for assets, clients, fees, compensation, and custody-related responses.
- Human resources and compliance records for employees, supervised persons, outside activities, and disciplinary disclosures.
- Legal, contracts, marketing, and operations records for services, conflicts, brokerage, referrals, account review, voting, and client communications.
- Prior filings and change logs to identify every answer that may need revision.
3. Reconcile Part 1, Part 2, Part 3, and firm records
Compare the structured filing with the narrative documents. Confirm that client types, assets, services, fees, conflicts, affiliates, custody practices, disciplinary disclosures, and supervised persons tell one coherent story. Resolve differences against authoritative source records, not against whichever version is easiest to copy.
4. Review, validate, submit, and preserve evidence
Run the IARD completeness check and resolve errors. Complete the appropriate execution page, confirm the filing account is ready for applicable charges, obtain the firm’s required approvals, and have an authorized person submit. After submission, save the accepted filing, timestamp, approval evidence, source package, delivery actions, and follow-up items.
A rejected or deficient filing should reopen the workflow with the regulator’s message, named owner, response deadline, corrected evidence, and final resolution. Do not handle the exception only through email, where the reason and corrective action can become detached from the filing record.
How can Process Street support Form ADV operations?
Process Street can organize the work around Form ADV, but it does not replace IARD, legal analysis, or an authorized filer. Use it as the operating layer that connects deadlines, owners, evidence, review, approvals, and exceptions before the official submission.
Run Form ADV work in Process Street
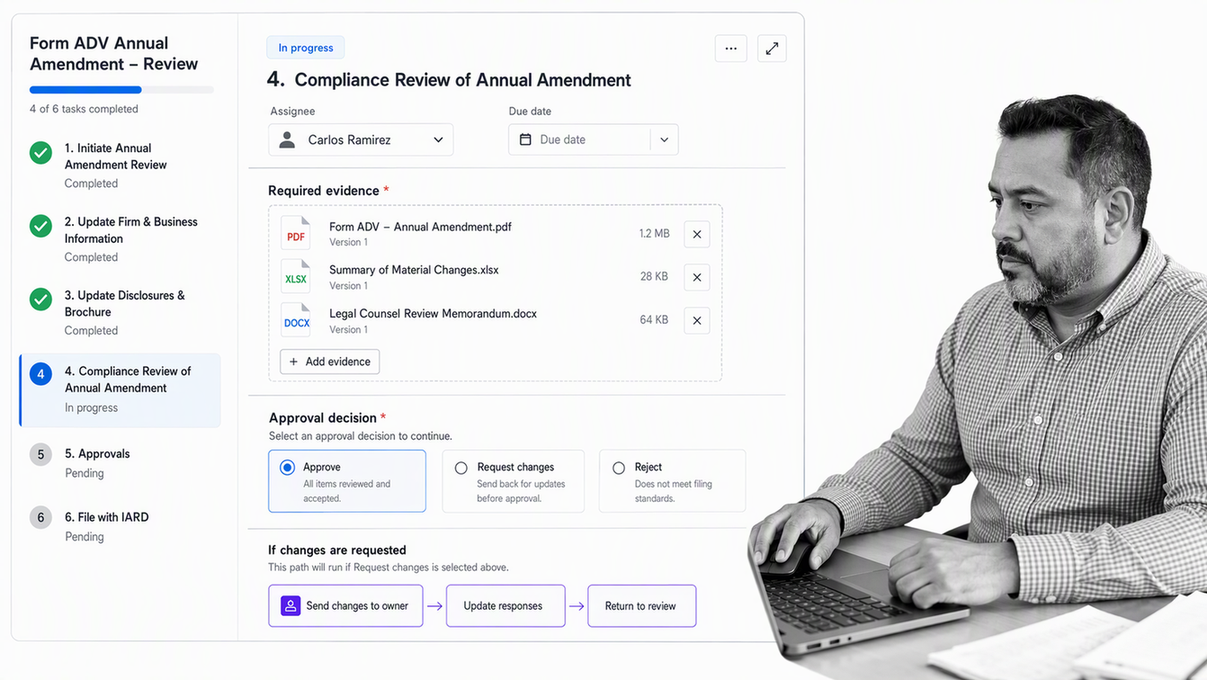
A form workflow can turn the filing cycle into a reusable sequence with assigned tasks, required form fields, due dates, conditional paths, approvals, and evidence. The workflow can branch for an initial application, annual amendment, other-than-annual amendment, state filing, brochure change, or personnel update while keeping a common review standard.
Start with the actual filing map. One task should correspond to one clear outcome: collect the source, draft the response, review it, resolve exceptions, approve it, enter it in IARD, or verify acceptance. Avoid a single task called complete Form ADV, because it hides ownership and makes proof difficult to inspect.
Put controls inside the filing process
Use required fields to prevent a task from closing without its source record. Use approval tasks for legal, compliance, finance, or executive review points. Set due dates backward from the regulatory deadline so data collection, reconciliation, and exception handling have time to finish.
A broader financial services compliance workflow can connect Form ADV to marketing review, employee disclosures, outside business activities, disciplinary escalation, custody monitoring, client delivery, and books and records. The goal is one controlled operating model, not a standalone annual scramble.
Preserve proof and improve the next cycle
Keep the final filing package, task completion history, approval decisions, comments, exceptions, and delivery evidence together. At closeout, record what arrived late, which answers required rework, which source systems disagreed, and which events should trigger a midyear amendment review.
The SEC compliance checklist template can provide a starting structure. Adapt it to the firm’s registration, policies, states, filing calendar, and review responsibilities before using it for production work.
What belongs on a Form ADV review checklist?
- Confirm the filing type, regulator, jurisdictions, due date, and authorized submitter.
- Copy the prior filing into a controlled review package and create a complete change log.
- Assign every Part 1 item, schedule, disclosure reporting page, brochure section, supplement, and relationship summary section.
- Identify the authoritative source record for each material response.
- Reconcile ownership, control, affiliates, employees, client types, assets, fees, services, custody, conflicts, and disciplinary information.
- Compare Part 1, Part 2, Part 3, agreements, marketing material, policies, and actual operating practice.
- Document all legal, compliance, finance, and business approvals required by firm policy.
- Run the IARD completeness check and resolve every validation error.
- Verify applicable account funding or filing charges without relying on a stale fee table.
- Submit through IARD and retain acceptance evidence, the final filing package, and a timestamped copy.
- Complete required brochure, supplement, relationship summary, and client delivery actions.
- Open follow-up tasks for deficiencies, regulator questions, policy changes, training, and future amendment triggers.
Form ADV FAQs
What is Form ADV?
Form ADV is the uniform form used by investment advisers to register with the SEC and state securities authorities. It also creates public disclosures that investors can review when evaluating an adviser.
What is the difference between Form ADV Part 1 and Part 2?
Part 1 is a structured filing about the advisory firm, its ownership, business, clients, affiliations, and disciplinary information. Part 2 is the narrative brochure and brochure supplement written for clients in plain English.
What is Form ADV Part 3?
Part 3 is the relationship summary, commonly called Form CRS. It applies to SEC-registered investment advisers that provide services to retail investors and summarizes services, fees, conflicts, legal history, and questions investors may ask.
How often is Form ADV updated?
A registered adviser generally files an annual updating amendment within 90 days after the end of its fiscal year. The Form ADV instructions also require certain information to be amended promptly when it becomes inaccurate. Firms should review the current instructions and applicable state requirements.
Where can investors find an adviser's Form ADV?
Investors can search the Investment Adviser Public Disclosure database by firm or individual. The public record may include the firm’s current Form ADV, relationship summary, registration status, professional background, and disciplinary disclosures.
Can Process Street file Form ADV for an adviser?
Process Street does not replace IARD, legal counsel, or compliance judgment. It can organize the work around the filing through assigned tasks, required information, due dates, approvals, evidence collection, and completion history before an authorized person submits through the official system.
