

Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


What You Need to Know About Generational Wealth Planning
Generational wealth planning is the work of building assets, protecting them, preparing the people who may one day manage them, and transferring responsibility in a way that reflects a family’s goals. It is not one account or one estate document. It is a system that connects financial habits, ownership, risk management, legal documents, family communication, and recurring review.
A useful plan answers five questions early: What does the family own? What should those assets accomplish? Who has authority now and later? What documents and account instructions control the transfer? How will the family keep the plan accurate as people, assets, and laws change?
This guide provides an educational framework, not individualized legal, tax, or investment advice. Estate and property law varies by jurisdiction, and investment decisions depend on personal circumstances. Use qualified attorneys, tax professionals, insurance professionals, and fiduciary financial advisers where appropriate.
- What is generational wealth planning?
- Why is generational wealth difficult to build and preserve?
- How do you build a generational wealth plan?
- How does estate planning fit into generational wealth?
- How do you prepare the next generation?
- How can Process Street make the plan operational?
- What belongs on a recurring review checklist?
- Generational wealth planning FAQs
What is generational wealth planning?
Generational wealth is the financial and nonfinancial advantage one generation can pass to another. It may include cash, investments, retirement accounts, real estate, business interests, intellectual property, insurance proceeds, valuable property, education support, professional relationships, and the knowledge required to manage those resources.
Generational wealth planning coordinates how those resources are accumulated, governed, protected, and transferred. The plan should cover both the assets and the operating capability around them. Passing an account to someone who does not understand its purpose, risks, tax treatment, or decision rules can leave the transfer incomplete.
A plan transfers assets and decision-making capability
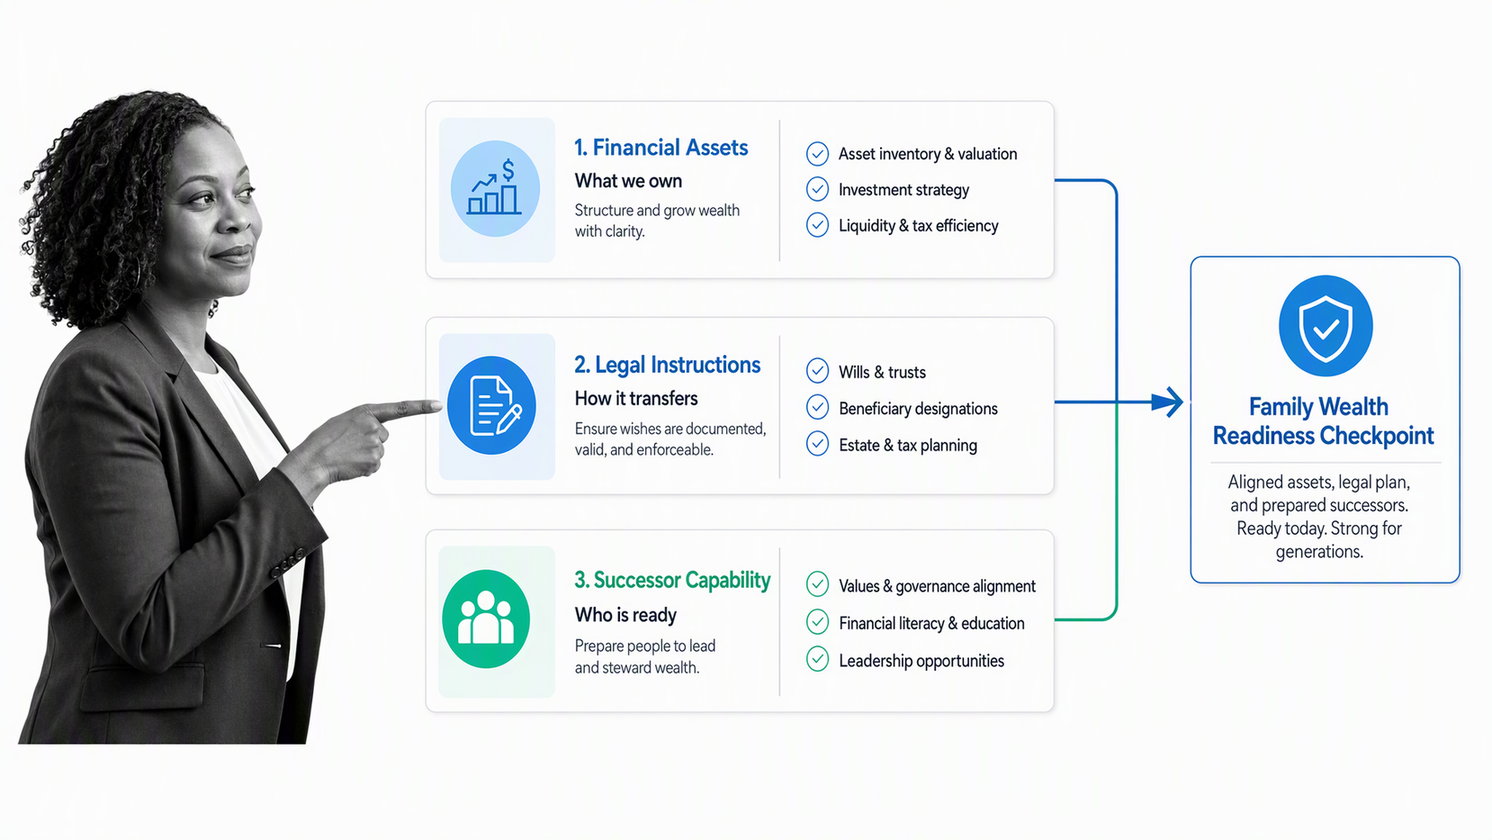
The financial layer covers saving, investing, property, insurance, debt, business ownership, and liquidity. The legal layer covers ownership, beneficiary designations, wills, trusts where appropriate, powers of attorney, health care documents, and business agreements. The human layer covers values, financial education, roles, communication, conflict management, and readiness to act.
These layers should agree. A family may have careful legal documents but no current asset inventory. It may have strong investments but outdated beneficiaries. It may own a business but have no successor or decision process. Planning finds those gaps before a transition forces the family to solve them under pressure.
Why is generational wealth difficult to build and preserve?
Families do not begin from the same position. Income, homeownership, access to credit, education, inherited assets, discrimination, health costs, caregiving responsibilities, and exposure to financial shocks all affect the ability to accumulate wealth. The Federal Reserve’s Distributional Financial Accounts show how unevenly wealth is distributed across demographic groups. A sound guide should acknowledge those different starting points without treating planning as a substitute for broader economic conditions.
Even after assets are built, preservation can fail through concentrated risk, excessive debt, missing insurance, unclear ownership, poor records, outdated legal documents, family conflict, unprepared successors, fraud, or an estate plan that does not match the way accounts and property are titled.
- Fragmented information: records sit across institutions, inboxes, paper files, and individual memory.
- Unclear authority: relatives do not know who may act, who should be consulted, or where professional judgment is required.
- Mismatched instructions: a will, beneficiary form, trust, deed, or business agreement may point in different directions.
- No successor preparation: future owners inherit responsibility without context, skills, or agreed decision rules.
- No review rhythm: the plan falls out of date after a move, marriage, birth, death, sale, acquisition, or law change.
The purpose of planning is not to predict every future event. It is to create a clear system for decisions, records, professional review, and adaptation.
How do you build a generational wealth plan?
Start with the family’s current reality, then connect long-term goals to concrete ownership, documents, roles, and recurring actions. The sequence below keeps the plan practical.
Step 1: Build a stable financial foundation
A transfer plan cannot compensate for fragile day-to-day finances. Establish a budget, emergency reserves, appropriate insurance, manageable debt, and a consistent saving and investing habit. Match investments to the family’s goals, time horizon, liquidity needs, and capacity for risk.
Diversification can reduce reliance on one asset or market segment, but it does not eliminate loss. Investor.gov explains that allocation depends on time horizon and risk tolerance, and that diversification should be checked across and within asset classes. Review the Investor.gov guide to asset allocation and diversification with a qualified adviser before making personal investment decisions.
Step 2: Inventory assets, liabilities, ownership, and records
Create a structured inventory of financial accounts, retirement plans, insurance, property, business interests, valuable personal property, debts, guarantees, digital assets, intellectual property, and important contracts. For each item, record the owner, co-owner, beneficiary where applicable, custodian or institution, purpose, location of supporting records, and the professional contact who understands it.
Do not place passwords or private keys in a general workflow or unsecured document. Record where protected access instructions are held and who is authorized to retrieve them. The inventory should help the right person find the right record without exposing sensitive access data.
Step 3: Define goals and transfer principles
Decide what the wealth is meant to do. Goals may include housing security, education, care for a family member, business continuity, philanthropy, entrepreneurship, retirement support, preservation of a shared property, or flexible opportunity for future generations.
Then define the principles that guide tradeoffs. Examples include keeping a family business operating, treating heirs equitably rather than identically, preserving liquidity for taxes or expenses, requiring shared-property decisions to follow an agreed process, or funding education while leaving other choices open.
Step 4: Align ownership, beneficiaries, and legal documents
Review how every important asset is owned and what instruction controls it at death or incapacity. A will does not necessarily control an account with a beneficiary designation or property held under another legal arrangement. Coordinate the full set of instructions with an estate-planning attorney and other relevant professionals.
The NAACP’s estate-planning roadmap highlights practical safeguards such as making an inventory, creating a valid will, reviewing beneficiaries, checking property title, and revisiting the plan after major life changes.
Step 5: Prepare successors and fiduciaries
Name people based on judgment, reliability, availability, and fit for the role, not only family seniority. Executors, trustees, agents under a power of attorney, guardians, business successors, and family representatives may need different skills. Confirm that a person is willing to serve and understands when to involve professionals.
The Consumer Financial Protection Bureau explains that a fiduciary managing another person’s money must act in that person’s interest, manage property carefully, keep funds separate, and maintain complete records. Its fiduciary guidance is a useful starting point for discussing the seriousness of these roles.
Step 6: Run a recurring review and communication process
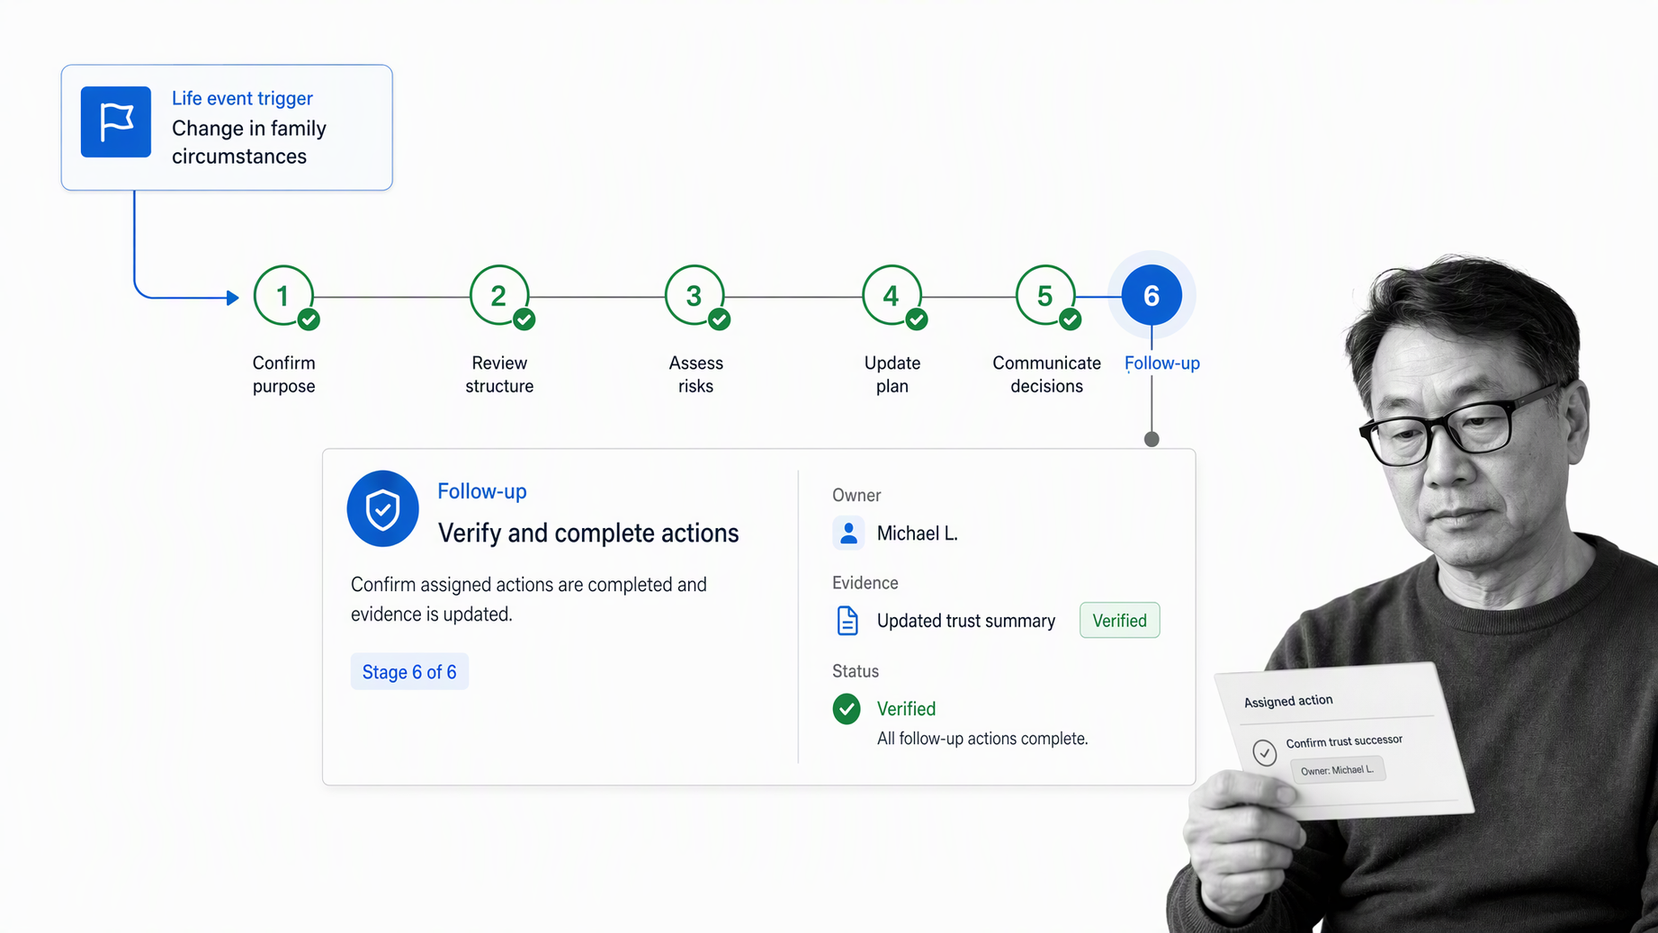
Set a recurring review date and event-based triggers. Review the inventory, legal documents, beneficiaries, ownership, insurance, professional contacts, family roles, business succession, and open actions. Record decisions and assign follow-up rather than ending with a conversation and no owner.
A clear wealth management process turns the plan into a cycle: assess, decide, document, act, verify, and review. The cycle matters because generational planning is ongoing stewardship, not a one-time document project.
How does estate planning fit into generational wealth?
Estate planning is the legal and administrative part of the broader wealth plan. It addresses how property and authority should be handled during incapacity and after death. The appropriate documents and structures depend on the family, the assets, the jurisdiction, and current law.
Coordinate wills, trusts, powers, and beneficiary instructions
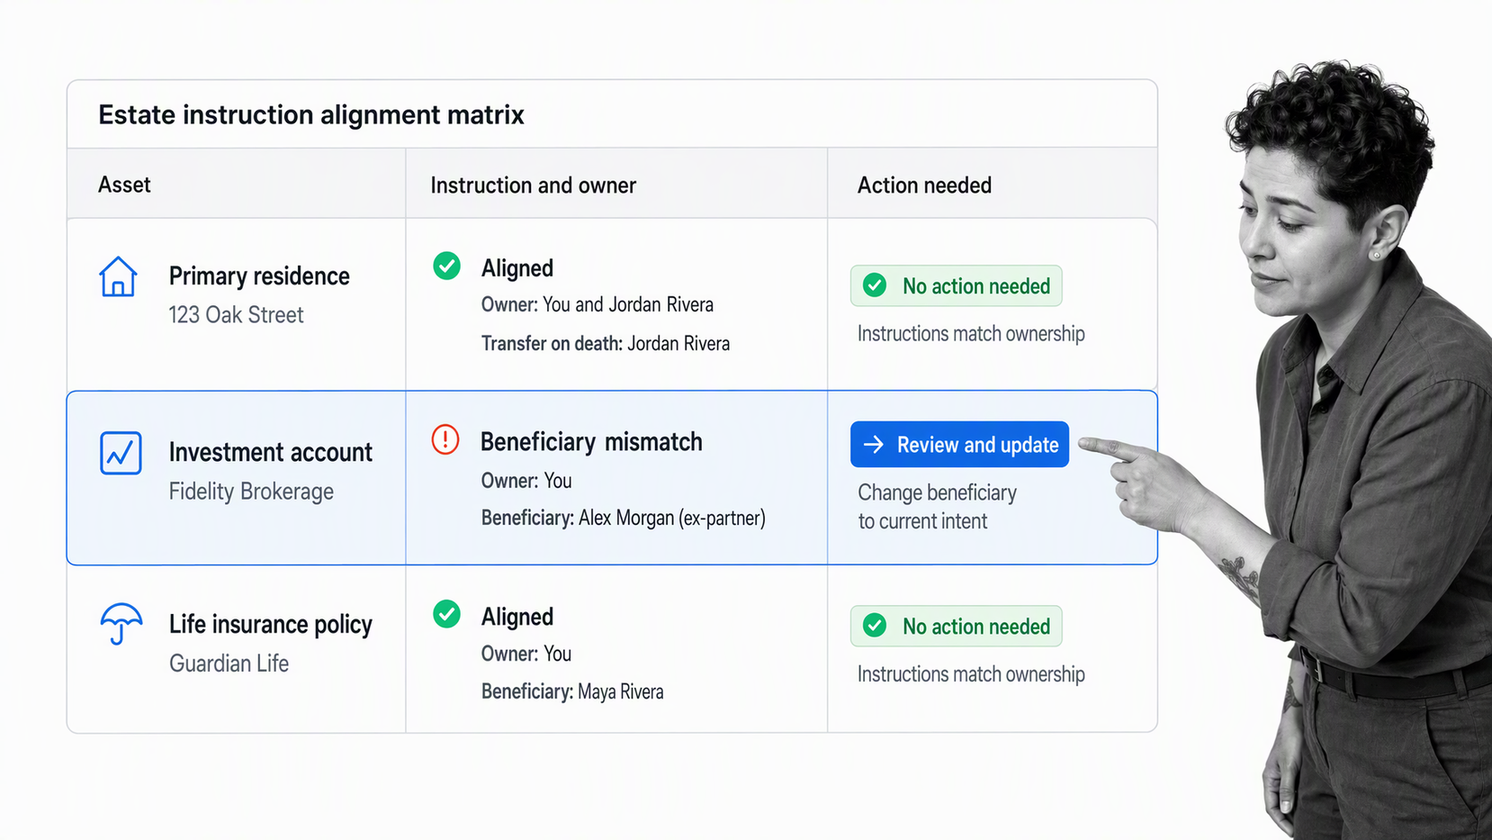
A typical review may consider a will, beneficiary designations, property title, powers of attorney, health care directives, trusts where appropriate, guardianship choices, business agreements, insurance, and instructions for personal or digital property. The goal is not to collect documents. It is to make the instructions consistent and executable.
Plan for tax review without relying on stale thresholds
Estate and gift tax rules can change, and state rules may differ from federal rules. Avoid building a long-term plan around a figure copied from an old article. Check current filing guidance and transfer rules with a qualified professional and the IRS estate and gift tax resource when the plan is reviewed.
Fund and implement the plan
Signing documents may not complete the work. A trust may need to be funded, account beneficiaries may need to be updated, property title may need review, insurance may need coordination, and business agreements may need signatures or approvals. Use an implementation checklist that names the owner, evidence required, professional reviewer, and completion date for each action.
The estate planning process template can help organize the administrative sequence, but legal documents and transfer decisions should be prepared or reviewed by the appropriate licensed professionals.
How do you prepare the next generation?
Preparing heirs does not require disclosing every account balance at once. It means building the knowledge, judgment, and communication habits needed to handle greater responsibility. The level of detail can grow with age, readiness, and the complexity of the assets.
Create a family decision framework
Document who participates in which decisions, what requires professional advice, how conflicts are handled, how shared assets are governed, and how family members can request information. Families with a business or shared property may need a more formal council, meeting cadence, voting rule, employment policy, or buy-sell process.
Teach stewardship through real responsibilities
Financial education is stronger when it connects to real work. A younger family member might help prepare a meeting agenda, maintain part of the asset inventory, research a charitable decision, shadow a business review, or present a budget for a defined goal. Responsibility can increase as the person demonstrates skill and judgment.
Preserve context, not only documents
Record why major decisions were made, what risks the family is trying to manage, which relationships matter, and what values should guide future choices. Future owners need room to adapt, but they should not have to reconstruct the purpose of every structure from scattered paperwork.
How can Process Street make the plan operational?
Process Street can help families, family offices, and advisers coordinate the recurring work around a generational wealth plan. It does not replace an attorney, tax professional, insurance professional, fiduciary adviser, custodian, or financial system. It provides a structured operating layer for assignments, required information, approvals, files, reminders, exceptions, and completion history.
Run a recurring family wealth review workflow
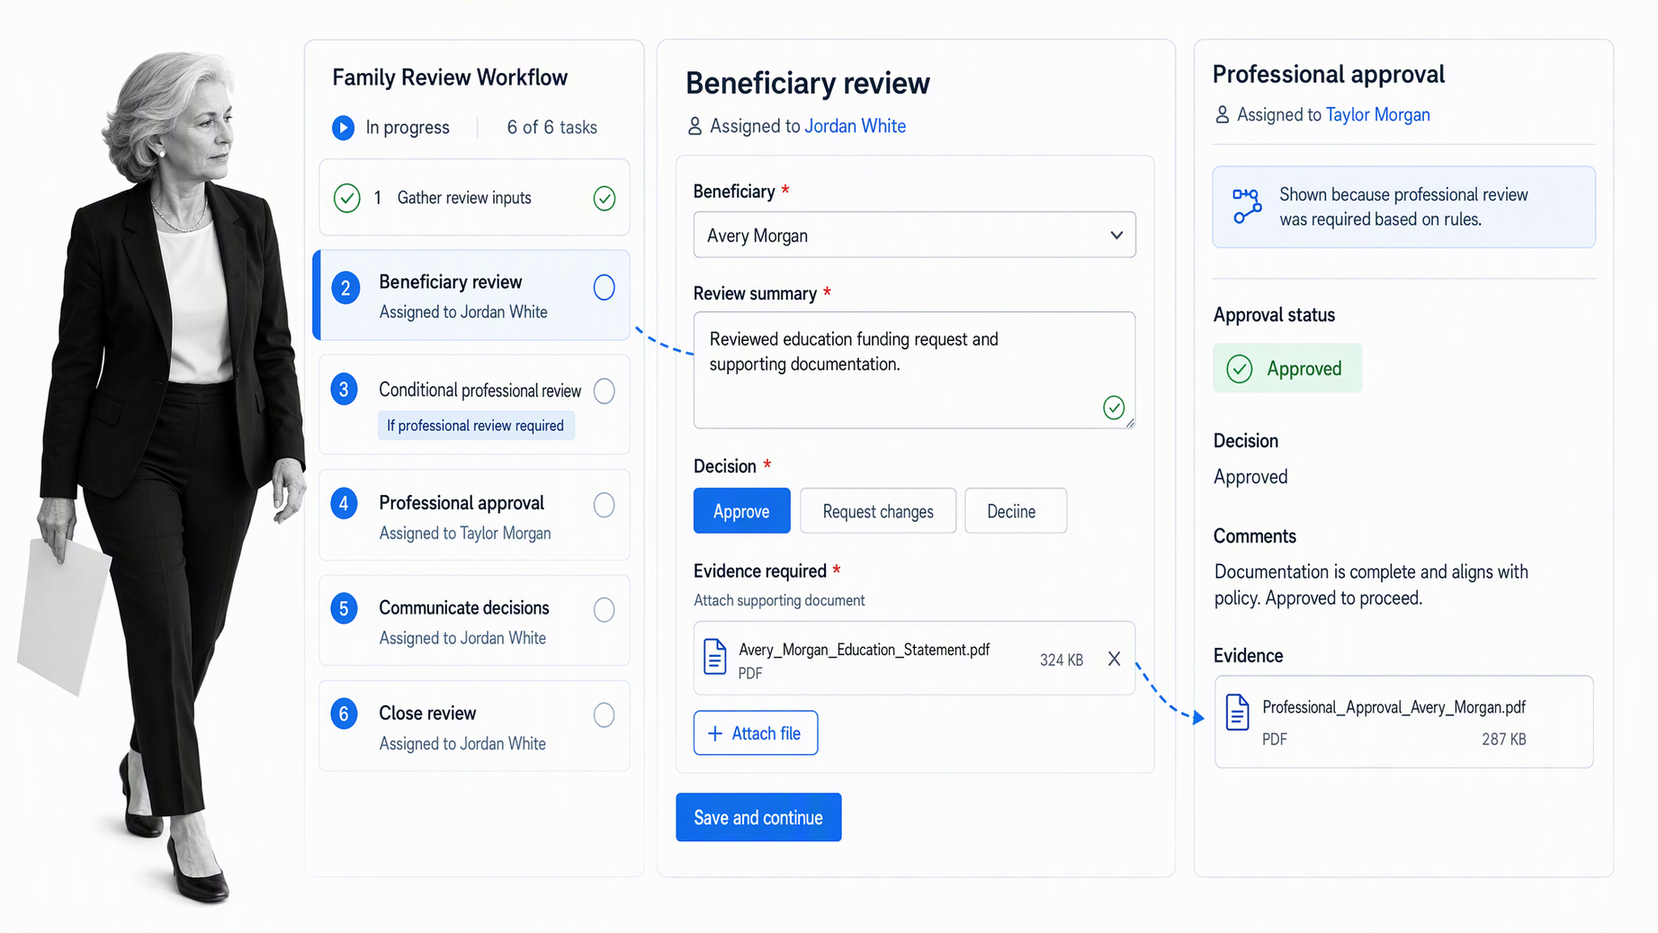
A review workflow can assign the asset inventory, beneficiary checks, legal-document review, insurance review, business succession actions, family meeting preparation, professional sign-off, and follow-up. Conditional paths can route work based on an asset type, a life event, or whether a specialist review is required.
Approvals can keep a sensitive step from moving forward until the accountable person has reviewed it. Required fields and files can keep evidence with the task. A completion history helps the family or adviser see what was checked, what changed, who decided, and what still needs action.
Process Street is especially useful when the plan involves recurring handoffs between family members and professionals. See how similar controls work in financial workflows, then start with one annual review process rather than trying to automate the entire family system at once.
What belongs on a recurring review checklist?
Use the checklist as an agenda and assignment system. It should direct qualified judgment to the right person rather than turning legal, tax, or investment questions into box-ticking.
- Confirm the family’s goals, priorities, and major changes since the last review.
- Update the inventory of assets, debts, ownership, beneficiaries, insurance, and important records.
- Review wills, trusts where applicable, powers of attorney, health care documents, guardianship choices, and property title with counsel.
- Review current estate and gift tax considerations with a qualified tax or estate professional.
- Check investment allocation, concentration, liquidity, and risk against current goals with a qualified adviser.
- Review business succession, key relationships, operating agreements, and continuity plans.
- Confirm fiduciaries, successors, emergency contacts, and professional advisers are current and willing to serve.
- Prepare and hold the appropriate family meeting, then record decisions and unresolved questions.
- Assign every follow-up action with an owner, due date, required evidence, and reviewer.
- Confirm protected access instructions are current without exposing passwords or private keys in the checklist.
Generational wealth planning FAQs
What is generational wealth planning?
Generational wealth planning is the coordinated work of building assets, protecting them, preparing the people who may receive or manage them, and creating a lawful transfer plan. It can cover property, investments, business interests, insurance, education funding, beneficiary designations, estate documents, family governance, and recurring review.
How do you start a generational wealth plan?
Start with a complete inventory of assets, debts, ownership structures, beneficiaries, insurance, and important records. Then define what the wealth should accomplish, identify the people and professional advisers involved, document the legal and financial plan, and establish a regular review process.
Is generational wealth planning only for wealthy families?
No. Families at many asset levels can benefit from clear beneficiaries, a valid will, incapacity planning, organized records, appropriate insurance, financial education, and a plan for property or business interests. The right structure depends on the family, its assets, and the law where it lives.
What is the difference between a will and a trust?
A will states how covered property should be handled after death and can address matters such as guardianship. A trust is a legal arrangement that holds or manages assets under defined terms. Neither is automatically right for every family, and beneficiary designations or property title may control some assets outside a will. A qualified estate-planning attorney can advise on the applicable state law.
How often should a generational wealth plan be reviewed?
Review the plan on a regular schedule and when a material event occurs, such as a birth, death, marriage, divorce, move, business change, major asset change, change in a fiduciary, or change in tax or estate law. The review should cover documents, ownership, beneficiaries, insurance, contact information, and the family’s operating agreements.
How can Process Street support generational wealth planning operations?
Process Street can turn recurring planning work into assigned workflows with required information, due dates, conditional paths, approvals, files, and completion history. Families and advisers can use those workflows to coordinate inventories, document reviews, family meetings, beneficiary checks, business succession tasks, and follow-up while keeping professional legal, tax, and investment judgment with the appropriate experts.