Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Complete Guide to the Different Types of Hedge Funds
The main types of hedge funds are usually grouped by the source of return they pursue: equity selection, corporate events, relative-value relationships, macroeconomic moves, systematic signals, credit opportunities, or a combination of strategies. The labels are useful, but they are not standardized risk grades. Two funds in the same category can have very different leverage, liquidity, concentration, and downside exposure.
This guide explains how the major hedge fund types work, what can make each one gain or lose money, how hedge funds differ from mutual funds, and what investors should examine before committing capital. It also covers the operational workflows fund teams use to make due diligence, onboarding, approvals, and evidence more consistent.
Hedge funds are complex private investments. This article is educational and is not legal, tax, or investment advice. Eligibility does not make an investment suitable, and a sophisticated strategy does not remove the possibility of substantial loss.
- What is a hedge fund?
- What are the main types of hedge funds?
- How do hedge fund strategies differ?
- How are hedge funds different from mutual funds?
- What risks should investors evaluate?
- How should investors perform hedge fund due diligence?
- How can hedge fund operations teams standardize repeatable work?
- Types of hedge funds FAQs
What is a hedge fund?
A hedge fund is a private pooled investment fund. Its manager invests capital from eligible investors under a defined mandate, which may permit short selling, derivatives, leverage, concentrated positions, less-liquid assets, or rapid changes in exposure. Investor.gov explains that hedge funds do not operate under all of the investor-protection rules that apply to mutual funds and exchange-traded funds.
The word hedge can be misleading. Some funds reduce selected risks by pairing long and short positions or by using derivatives. Others deliberately accept market, credit, volatility, liquidity, event, or model risk in pursuit of return. The offering documents and actual portfolio construction matter more than the label.
Hedge funds are often described by strategy, trading style, asset class, or portfolio structure. That is why different classification systems produce different lists. An equity long/short fund may also be quantitative. A distressed-credit fund may sit inside an event-driven portfolio. A multi-strategy fund may allocate to several teams whose books behave differently.
What are the main types of hedge funds?
There is no single universal taxonomy. The HFR strategy classification uses broad families such as equity hedge, event driven, macro, and relative value, while other industry and educational frameworks add specialist, systematic, managed-futures, multi-manager, or portfolio-structure categories. The practical map below helps readers understand where returns and losses may come from.
| Hedge fund type | Primary return driver | Important risks to examine |
|---|---|---|
| Equity hedge | Long and short equity positions | Market exposure, concentration, short squeezes, stock-selection error |
| Event-driven | Corporate transactions or restructurings | Deal failure, timing, legal outcomes, financing conditions |
| Relative value | Price relationships between related instruments | Leverage, basis widening, liquidity, model assumptions |
| Global macro | Economic, policy, currency, rate, or commodity moves | Directional exposure, volatility, geopolitical surprises |
| Managed futures | Systematic or discretionary trends in futures markets | Trend reversal, whipsaw, leverage, model crowding |
| Credit and distressed | Credit selection, spreads, restructuring outcomes | Default, recovery value, liquidity, legal complexity |
| Quantitative or systematic | Rules and models applied to market data | Model decay, data quality, crowding, execution |
| Multi-strategy | Allocation across several internal strategies | Complexity, hidden correlation, capital allocation, governance |
| Fund of funds | Selection and combination of external funds | Layered fees, manager selection, transparency, liquidity mismatch |
Equity hedge funds
Equity hedge funds build portfolios around shares and equity-linked instruments. Long/short equity managers buy securities they expect to outperform and short securities they expect to underperform. Net exposure can remain positive, negative, or close to neutral, depending on the mandate.
The category includes fundamental stock pickers, sector specialists, market-neutral portfolios, short-biased funds, and systematic equity strategies. Investors should look beyond the number of long and short positions. Gross exposure, net exposure, factor tilts, position concentration, borrow availability, and liquidity can determine how the portfolio behaves during stress.
Event-driven hedge funds
Event-driven funds invest around company-specific catalysts such as mergers, acquisitions, spin-offs, recapitalizations, bankruptcies, or restructurings. Merger-arbitrage managers may seek to capture the spread between a target company’s market price and the value offered in a transaction. Distressed specialists may invest across a company’s debt or equity while a restructuring unfolds.
The risk is not simply that the market falls. A deal can be delayed, challenged, repriced, or abandoned. A restructuring can produce a lower recovery than expected. Legal rights, financing conditions, security seniority, and the time required to reach an outcome can all change the economics.
Relative value hedge funds
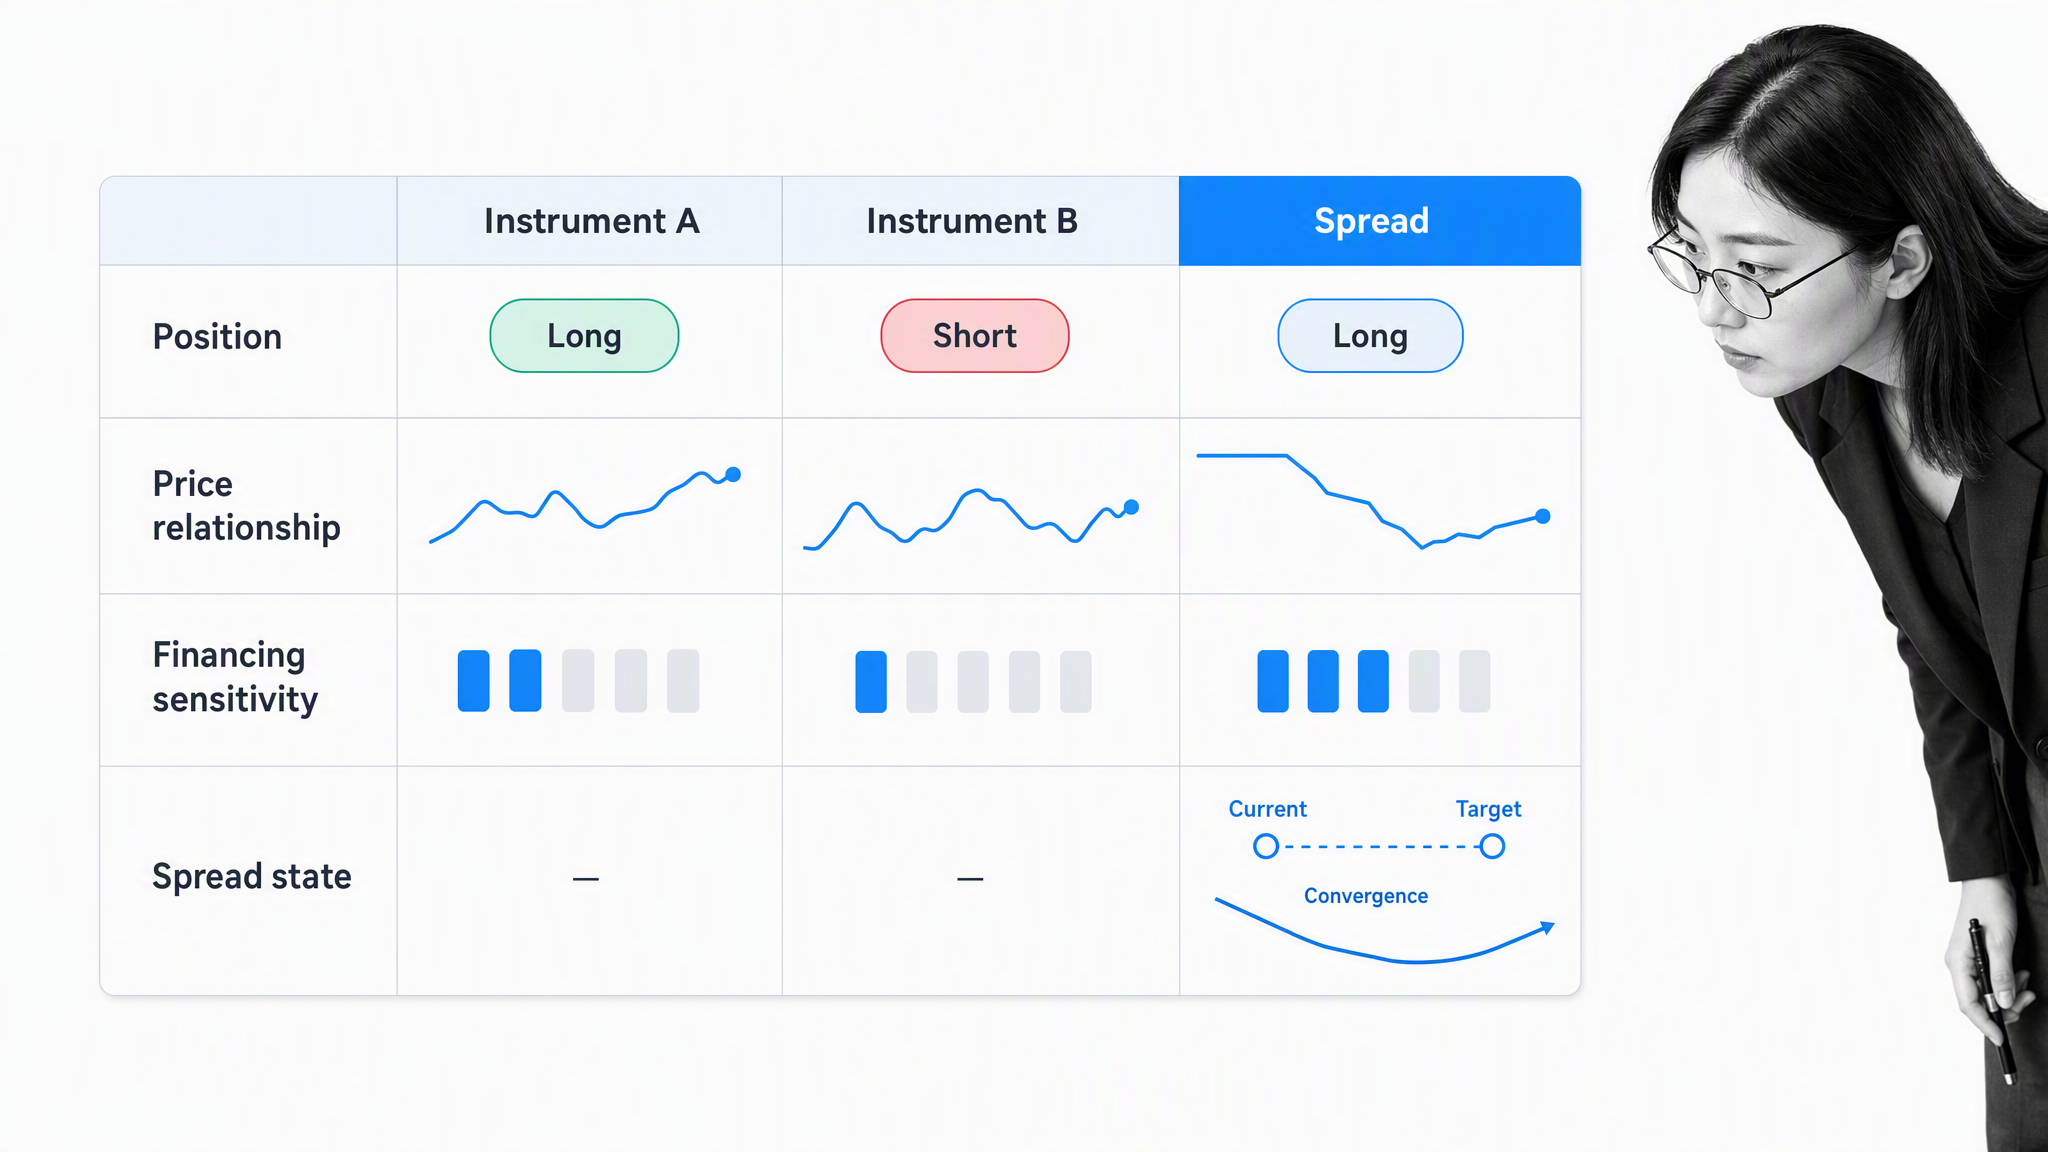
Relative value funds look for pricing differences between related instruments rather than making a simple bet on the direction of an entire market. Examples include convertible arbitrage, fixed-income relative value, capital-structure trades, and statistical relationships between securities.
These trades can appear stable when the relationship holds, but small price gaps often require meaningful position size or leverage to produce a return. A relationship can widen before it converges, financing can become expensive, and liquidity can disappear when many participants try to exit similar trades.
Global macro hedge funds
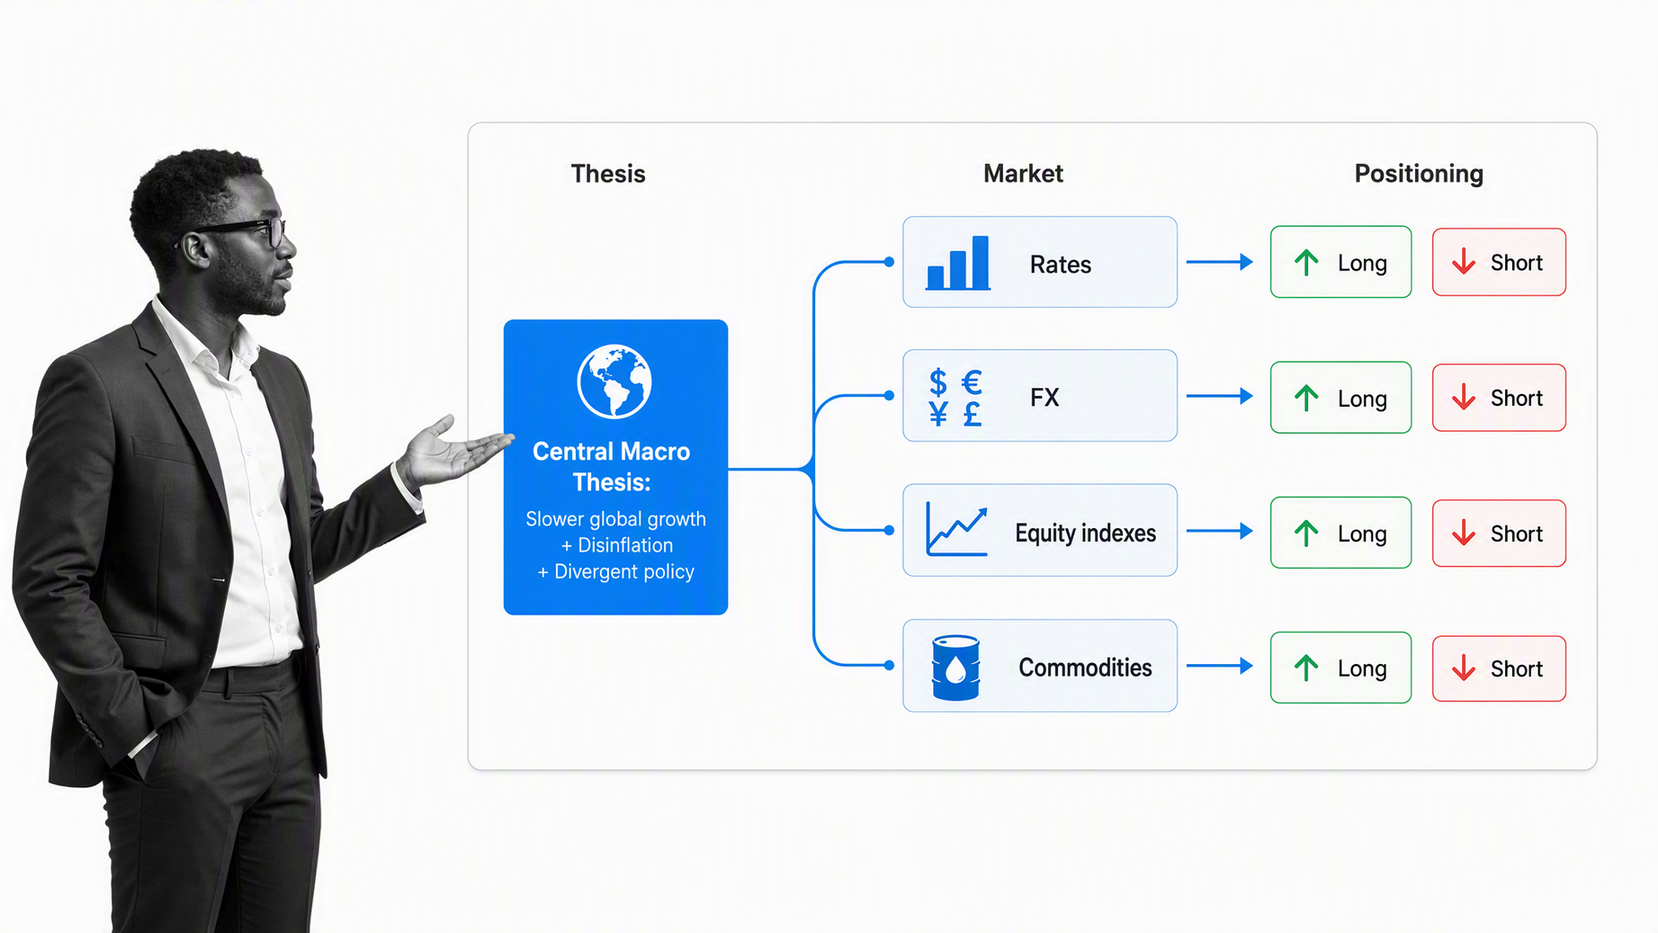
Global macro managers take positions based on broad economic and political views. They may trade currencies, interest rates, sovereign debt, equity indexes, commodities, or related derivatives. A discretionary manager may build a thesis from policy and economic research, while a systematic manager may translate macro signals into rules.
The same flexibility that creates opportunity can create large directional exposure. Investors should understand the manager’s time horizon, use of options, approach to stop-losses, concentration by theme, and behavior when several macro positions express the same underlying view.
Managed futures and trend-following funds
Managed-futures funds trade futures and related instruments across markets such as rates, currencies, equity indexes, commodities, and sometimes volatility. Many use trend-following rules that increase or reduce positions as price signals change, although discretionary and non-trend approaches also exist.
Broad market access can produce a return pattern that differs from long-only stock and bond holdings, but it is not a guaranteed hedge. Choppy markets can create repeated false signals, rapid reversals can erase trends, and model settings can cause several funds to respond similarly.
Credit and distressed hedge funds
Credit funds invest in corporate bonds, loans, structured credit, credit derivatives, or other claims on borrowers. Some focus on performing credit and changes in spreads. Distressed funds focus on issuers facing financial or operational pressure and may participate in restructurings.
Credit analysis must account for default probability, collateral, covenant protection, security priority, refinancing conditions, and likely recovery. Reported prices can lag reality in less-liquid holdings, so valuation policy and independent oversight deserve as much attention as the investment thesis.
Quantitative and systematic hedge funds
Quantitative funds use models and defined rules to select securities, size positions, manage risk, or execute trades. The model may draw on price, fundamental, economic, or other approved data. Systematic does not mean automatic safety. It describes how decisions are generated and implemented.
Due diligence should cover the economic rationale behind the signal, data provenance, testing discipline, transaction costs, capacity, execution quality, change control, and human override rules. A backtest can look convincing while depending on unavailable data, favorable assumptions, or relationships that weaken after deployment.
Multi-strategy hedge funds
Multi-strategy funds allocate capital across several strategies, teams, or trading books. The structure can diversify sources of return and let central management move capital as opportunities change. It can also make the portfolio harder to understand because risk may be shared across desks through common financing, counterparties, factors, or crowded positions.
Investors should examine how capital and risk limits are assigned, who can override a team, how losses affect future allocation, how liquidity is managed at the total-fund level, and whether the risk system can identify correlated exposures that appear unrelated at the desk level.
Fund of hedge funds
A fund of hedge funds allocates to a portfolio of external hedge fund managers. The approach can provide manager diversification and centralized selection, monitoring, and administration. It also introduces another layer of decision-making and costs.
The allocator must test whether underlying managers truly diversify one another, whether redemption terms align, and whether exposure data are timely enough to manage aggregate risk. Manager access is valuable only if selection, portfolio construction, and ongoing monitoring are strong.
How do hedge fund strategies differ?
The most useful comparison starts with the source of return and the path of loss. CFA Institute groups hedge fund strategies by investment characteristics and implementation, a reminder that categories describe different engines rather than a single product class with one expected behavior.
- Directional versus relative: Macro and some equity funds may take explicit market views. Relative-value funds focus more on relationships between instruments, although residual market exposure can remain.
- Discretionary versus systematic: Discretionary managers rely heavily on human judgment. Systematic managers encode much of the decision process in models and rules. Many funds combine both.
- Liquid versus less liquid: Exchange-traded positions can often be adjusted quickly. Distressed claims, complex credit, or private instruments may require longer holding periods and judgment-based valuations.
- Concentrated versus diversified: A focused activist or event portfolio may hold a small number of high-conviction positions. A quantitative book may hold many positions whose risks still cluster around common factors.
- Low gross exposure versus leveraged spread trades: Net market exposure can look modest while gross positions, derivatives, or financing create meaningful sensitivity to liquidity and price changes.
- Single strategy versus portfolio structure: A multi-strategy fund or fund of funds adds an allocation layer that must be evaluated separately from the underlying trades.
Labels can also conceal change. A manager may widen the mandate, add a new asset class, alter hedging, or hold more cash as conditions evolve. Investors need current exposure and process information, not only a category printed in a marketing document.
How are hedge funds different from mutual funds?
Both vehicles pool investor capital, but they operate under different structures and rules. Hedge funds are private funds offered to eligible investors under exemptions. Mutual funds are registered investment companies designed for broad public access and standardized oversight.
| Comparison area | Hedge funds | Mutual funds |
|---|---|---|
| Investor access | Generally limited by eligibility and offering terms | Generally available to retail investors |
| Strategy flexibility | May permit shorting, derivatives, leverage, concentration, and less-liquid assets | Operates within a registered fund mandate and regulatory framework |
| Liquidity | Redemption schedules, notice periods, gates, or lockups may apply | Shares are generally redeemable each business day at net asset value |
| Disclosure | Terms and reporting depend on private offering and regulatory requirements | Standardized public prospectus and shareholder reporting |
| Fees | May include management, performance, incentive, and fund expenses | Typically charges stated operating expenses and may have other distribution or transaction costs |
| Valuation | May include manager-valued or less-liquid positions | Net asset value calculated under registered-fund requirements |
Mutual funds can still lose money, hold concentrated exposures within a mandate, or charge meaningful expenses. Hedge funds can still use conservative positions. The structural distinction does not replace product-level analysis. Investor.gov provides a separate overview of mutual funds and exchange-traded funds for readers comparing registered products.
What risks should investors evaluate before choosing a hedge fund?
A practical hedge fund risk map
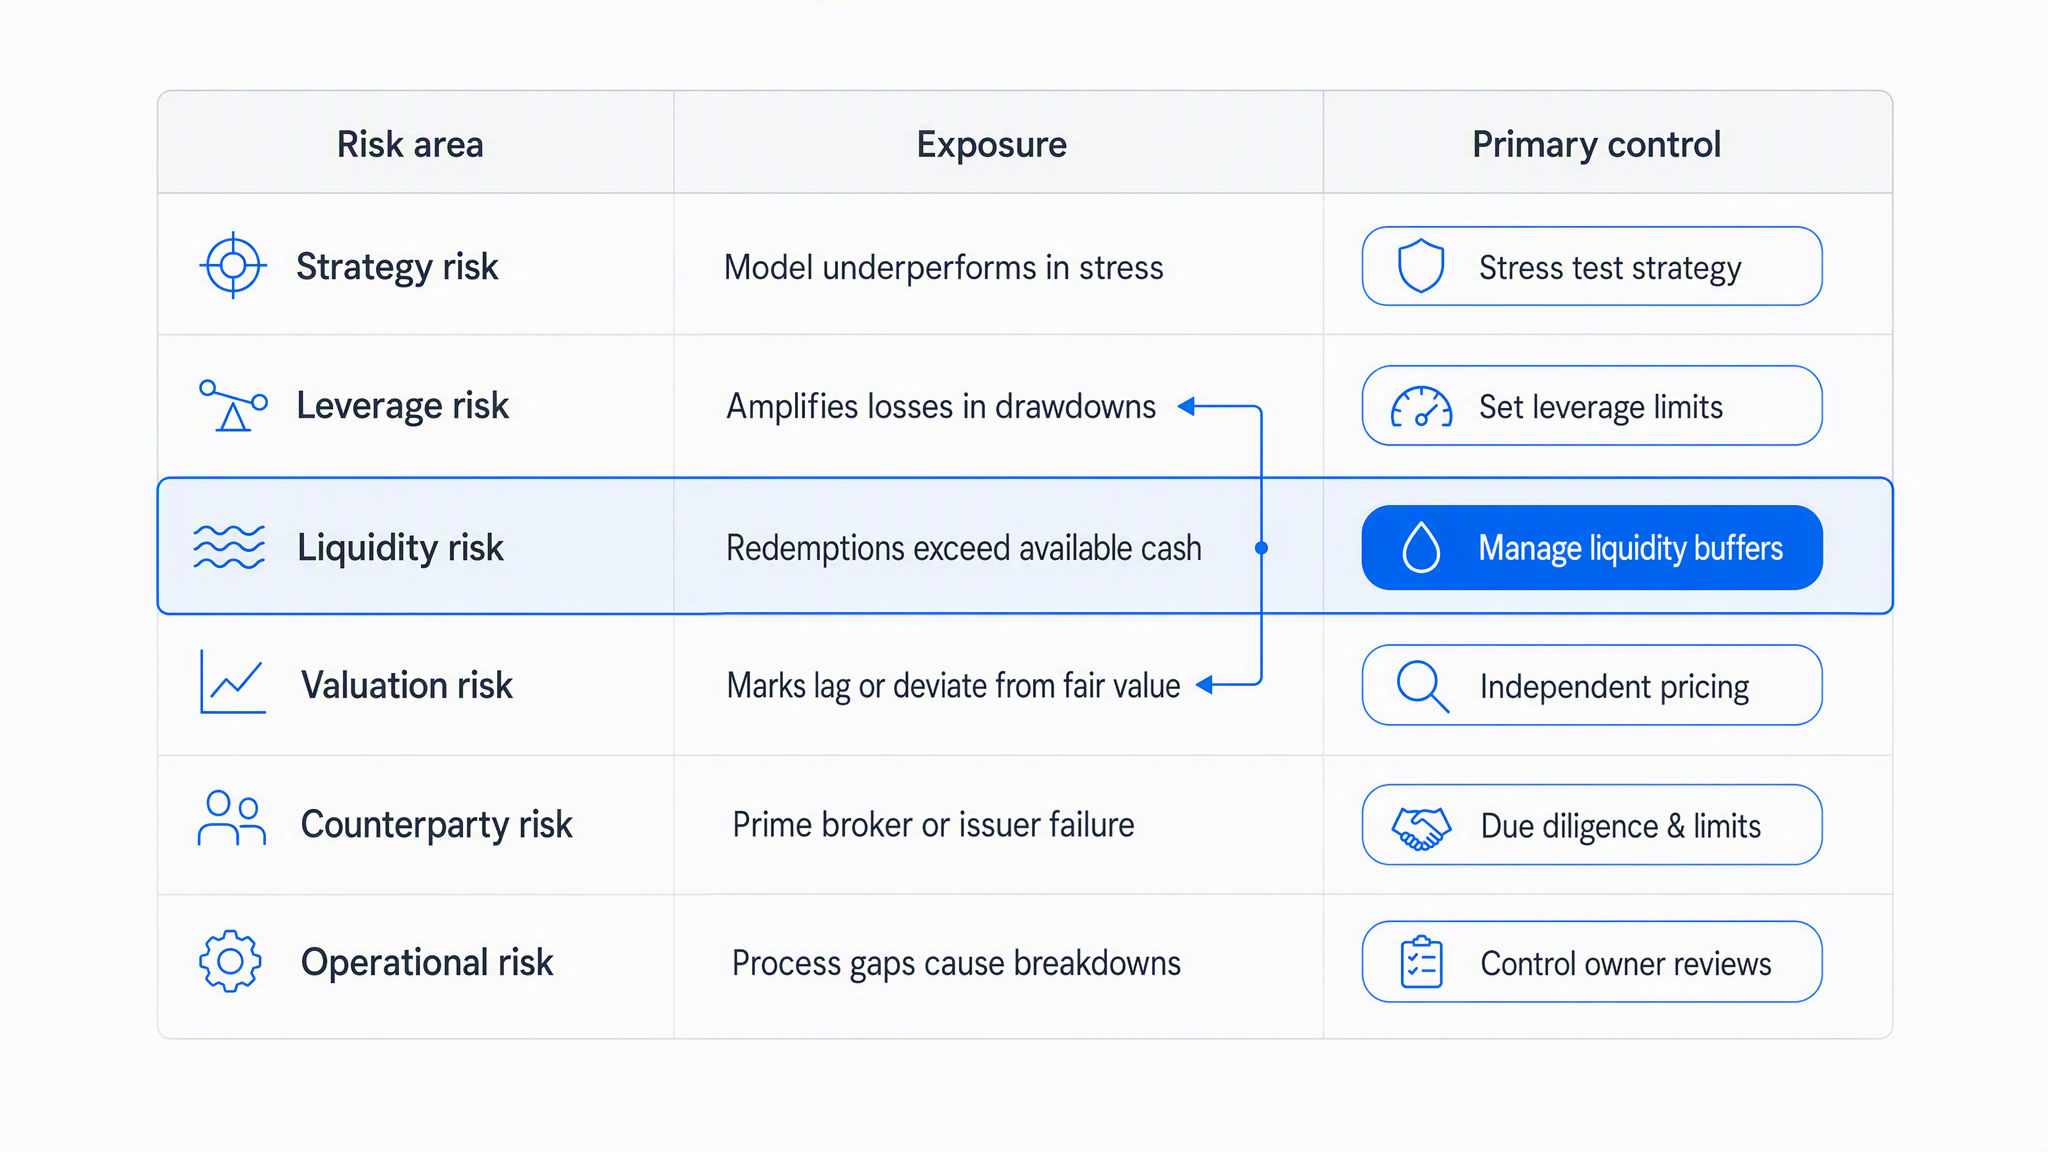
The relevant question is not which category sounds most sophisticated. It is whether the investor understands the full path from strategy to exposure, liquidity, valuation, operations, and loss. These risks interact, especially during stressed markets.
- Strategy risk: The core thesis may be wrong, early, crowded, or dependent on a relationship that breaks.
- Leverage risk: Borrowing and derivatives can magnify losses, create margin calls, and force sales at unfavorable prices.
- Liquidity risk: Assets may be difficult to sell while investors face lockups, notice periods, gates, or side pockets.
- Valuation risk: Less-liquid or complex positions may rely on models, broker quotes, or manager judgment rather than frequent market trades.
- Counterparty risk: Prime brokers, derivatives counterparties, custodians, administrators, and other service providers can create dependencies.
- Concentration risk: A portfolio can be concentrated by issuer, theme, geography, factor, financing source, or hidden common exposure.
- Model and data risk: Quantitative decisions can fail because of weak assumptions, bad data, implementation errors, or changing market structure.
- Key-person risk: Performance, relationships, or controls may depend heavily on a small number of decision-makers.
- Operational risk: Weak reconciliation, access controls, valuation governance, trade capture, compliance, or disaster recovery can create loss even when the investment idea is sound.
- Conflict risk: Allocation, valuation, related-party transactions, side arrangements, or parallel products may create incentives that differ from an investor’s interests.
Diversification can reduce some exposures, but it does not guarantee protection. Different positions can become correlated during stress, and funds that report smooth returns may still hold liquidity, valuation, or tail risks that are not obvious from monthly performance.
How should investors perform hedge fund due diligence?
Due diligence should test both the investment process and the organization that executes it. A persuasive return history is not enough. Investors need to understand how the record was produced, whether the process is repeatable, and what could prevent them from receiving the value they expect.
- Define the portfolio job: State why the allocation is being considered, which risk or return objective it serves, and what would make the position unnecessary.
- Understand the strategy: Ask what creates return, what creates loss, where leverage appears, how positions are sized, and what market conditions are unfavorable.
- Reconcile the track record: Review returns, drawdowns, exposures, capacity, attribution, benchmark choice, and whether results include predecessor or simulated performance.
- Read the legal terms: Examine fees, expenses, liquidity, gates, side pockets, valuation discretion, suspension rights, conflicts, key-person provisions, and investor reporting.
- Evaluate the organization: Assess ownership, decision rights, staffing, turnover, succession, compliance, technology, cybersecurity, and business continuity.
- Review service providers: Confirm the roles of the administrator, auditor, custodian, prime broker, legal counsel, and other material parties.
- Test operations and controls: Follow a trade and a cash movement through authorization, booking, confirmation, reconciliation, valuation, reporting, exception handling, and evidence retention.
- Verify regulatory information: Where applicable, review the adviser’s filing and disciplinary information through the SEC’s Investment Adviser Public Disclosure database.
- Monitor after investment: Define reporting expectations, exposure thresholds, liquidity checks, operational events, personnel changes, and review triggers before capital is committed.
Every answer should connect to evidence. If the manager says risk is tightly controlled, the investor should understand the limits, who monitors them, what happens after a breach, and how the event is recorded. If liquidity is described as adequate, compare the redemption promise with the time required to sell the underlying positions.
How can hedge fund operations teams standardize repeatable work?
A controlled hedge fund review workflow
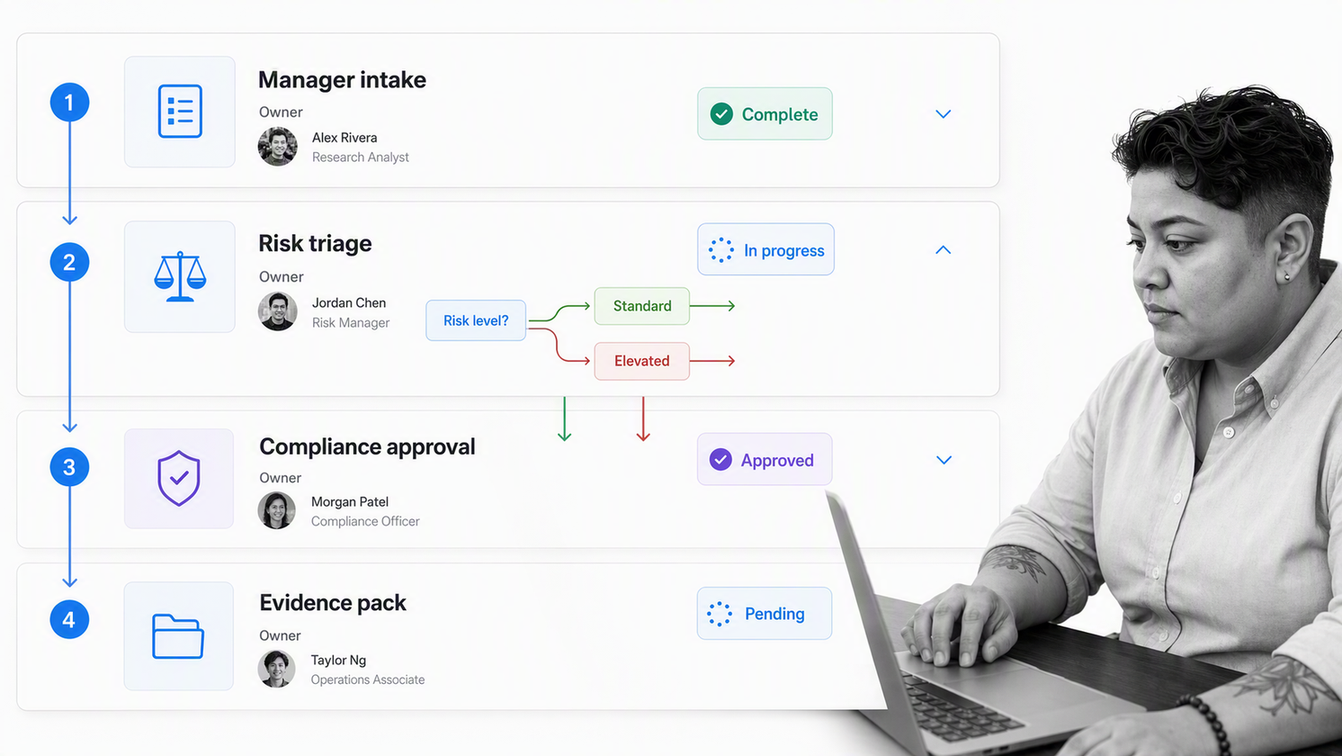
Investment judgment may be specialized, but much of the supporting work is repeatable. Investor onboarding, due-diligence questionnaires, account opening, compliance reviews, trade reconciliations, valuation checks, cash controls, incident response, and periodic reporting all benefit from a defined process with named owners and evidence.
A form workflow can capture structured intake, route the case by risk or strategy, assign reviewers, require approvals, and retain the decision record in one controlled run. Conditional routing helps a team ask different questions for a liquid equity fund, a leveraged relative-value strategy, or an illiquid distressed vehicle without forcing every case through the same checklist.
Process Street can support the operational layer around investment work. Teams can turn a policy or procedure into a recurring workflow, assign tasks, branch by responses, collect files, add approval steps, and maintain a visible history of actions. The workflow does not decide whether an investment is suitable. It helps the authorized people execute and document the review consistently.
- Investor onboarding: Gather required information, route compliance checks, collect approvals, and record unresolved exceptions.
- Manager due diligence: Assign investment, operational, legal, tax, cybersecurity, and service-provider reviews with a common decision record.
- Valuation governance: Schedule price challenges, independent reviews, exception escalation, and committee approval for difficult positions.
- Trade and cash controls: Separate initiation, approval, confirmation, reconciliation, and exception resolution responsibilities.
- Periodic monitoring: Trigger reviews when exposure, personnel, service providers, liquidity terms, or other material facts change.
- Evidence readiness: Keep files, comments, decisions, approvals, and completion records connected to the workflow that produced them.
The strongest starting point is one real process with clear stakes. Map the trigger, required information, owners, decisions, exceptions, evidence, and completion criteria, then test it with the people who perform the work. If you want to turn that design into a controlled workflow, request a Process Street demo with the process you want to improve.
Types of hedge funds FAQs
What are the main types of hedge funds?
A practical classification includes equity hedge, event-driven, relative value, global macro, managed futures, credit, quantitative or systematic, multi-strategy, and fund-of-funds approaches. Taxonomies vary because one fund can combine several strategies.
Which type of hedge fund is the least risky?
No category is automatically low risk. Risk depends on the fund’s actual positions, leverage, liquidity, concentration, counterparties, valuation methods, controls, and manager behavior. A strategy label is a starting point for due diligence, not a risk rating.
How are hedge funds different from mutual funds?
Hedge funds are private funds with broader strategy flexibility and investor eligibility restrictions. Mutual funds are registered investment companies with standardized disclosure and daily redemption requirements. Individual products can still differ materially within either group.
Do all hedge funds use leverage and short selling?
No. Many hedge funds may use leverage, short positions, or derivatives, but the extent and purpose vary by mandate. Investors should review the offering documents and ask how gross, net, and embedded exposures are measured and limited.
What documents should a potential hedge fund investor review?
Review the offering memorandum, subscription documents, audited financial statements, fee and expense disclosures, liquidity terms, valuation policies, conflict disclosures, and the adviser’s Form ADV when one is available. Professional legal, tax, and investment advice may also be appropriate.
How can hedge fund teams improve operational consistency?
Teams can standardize recurring work such as investor onboarding, due diligence, approvals, reconciliations, exception handling, compliance reviews, and evidence collection in controlled workflows with named owners and a visible completion record.