

Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


What Are the 5 Venture Capital Stages? The Ultimate Guide
Venture capital stages describe how a startup and its financing needs change as the company moves from an idea to a scalable business and, eventually, a liquidity event or long-term private operation. The round label matters, but it is only shorthand. Investors are really asking what has been proved, what remains uncertain, how the capital will change the company, and whether the next milestone can justify the risk.
A practical five-stage map is: pre-seed and seed, Series A, Series B, Series C and later growth, and exit readiness. This structure aligns with the broad funding lifecycle described in the NVCA 2026 Yearbook, while avoiding brittle funding-size rules that can become obsolete or misclassify unusual companies.
There is no universal classification. The OECD notes that venture capital stage definitions differ across data providers. Use the five stages as a decision framework, then judge the company by its maturity, evidence, financing purpose, and market context.
In this guide:
- What are venture capital stages?
- How do stages differ from funding rounds?
- What are the five venture capital stages?
- What changes between stages?
- How should founders prepare for the next stage?
- How can VC firms manage stage-gated workflows?
- What happens after late-stage funding?
- Venture capital stages FAQs
What are venture capital stages?
Venture capital stages are categories used to describe a private company’s maturity and the purpose of a financing round. Early capital may fund discovery, product development, and initial customer learning. Later rounds tend to fund a repeatable go-to-market system, organizational scale, expansion, acquisitions, resilience, or preparation for an exit.
Venture funds are pooled investment vehicles managed by an adviser that invests on behalf of the fund. The SEC investor education site explains the pooled private-fund structure and the long-term, illiquid nature of private-equity investing. Venture capital sits within the broader private-equity universe and focuses on companies that can grow rapidly but may have limited operating history.
For founders, a stage sets expectations about the proof needed for the next financing. For investors, it shapes sourcing, ownership targets, diligence depth, reserves, governance, and the type of support a portfolio company may need. For operators, it changes the systems required to close the round and use the capital responsibly.
How do venture capital stages differ from funding rounds?
A funding round is a transaction. A stage is a description of company maturity. They often move together, but they are not identical. A Series A company may still be testing parts of its go-to-market model. A seed company may already have meaningful revenue. A later company may raise an extension or bridge round without entering a new operating stage.
Round names can also reflect legal structure, negotiation history, or market convention. Company stage is better assessed through evidence: product maturity, customer behavior, repeatability, leadership capacity, financial controls, risk management, and the plan for the capital. The round label helps people communicate, but it should not substitute for analysis.
- Stage asks: What has the company learned and built?
- Round asks: What financing is being completed now?
- Readiness asks: Which milestone will this capital make possible?
- Diligence asks: What evidence supports the investment case and which risks remain open?
Avoid stage-label traps
Stage labels can create false precision. A larger round does not automatically mean a stronger company, and a smaller round does not automatically mean an earlier one. Capital intensity, geography, sector, market conditions, ownership strategy, and the financing instrument can all change the size and shape of a transaction.
Do not build a fundraising plan around a benchmark alone. Start with the operating milestone, the time and resources required to reach it, a downside case, and the proof the next investor will need. Then decide whether equity financing is appropriate and which round structure fits the company. A qualified adviser can help evaluate legal, tax, accounting, and financing consequences.
What are the 5 venture capital stages?
The following map groups the venture journey into five durable stages. It keeps pre-seed and seed together because both focus on discovery and initial validation, then separates the scaling and growth phases where the operating demands change materially.
Stage map: pre-seed and seed through exit readiness
| Stage | Company focus | Investor question | Operating priority |
|---|---|---|---|
| Pre-seed and seed | Validate the problem, team, product, and early demand | Is there a credible reason this could become a valuable company? | Fast learning and clean foundations |
| Series A | Turn early demand into a repeatable business | Can the company scale a working model? | Repeatability, measurement, and key hires |
| Series B | Scale the engine across teams, segments, or regions | Does performance hold as the company grows? | Management systems and operating leverage |
| Series C and later growth | Expand, defend, diversify, or acquire | Can the company sustain category-level growth and governance? | Resilience, controls, and strategic execution |
| Exit readiness | Prepare for a sale, public listing, secondary liquidity, or durable private operation | Can the company withstand transaction and public-market scrutiny? | Governance, reporting, and transaction readiness |
Pre-seed and seed
At pre-seed, founders are defining the problem, forming the team, building a prototype, and testing whether anyone cares. Seed capital extends that learning. The company develops a usable product, recruits early employees, tests distribution, and looks for evidence that customers experience enough value to support a business.
The strongest early evidence is specific. It may include repeated customer interviews, product use, pilot outcomes, retention, signed demand, technical progress, or a founder insight that is difficult to copy. Vanity metrics are less useful than evidence that changes a decision. Founders should be able to explain what they believed before the experiment, what happened, and how the result changed the product or market thesis.
- Define the customer and urgent problem.
- Build the smallest product that can test the core assumption.
- Document ownership, intellectual property, key agreements, and basic financial records.
- Set milestone-based use of funds rather than a broad spending wish list.
- Create a clear record of customer evidence and unresolved risks.
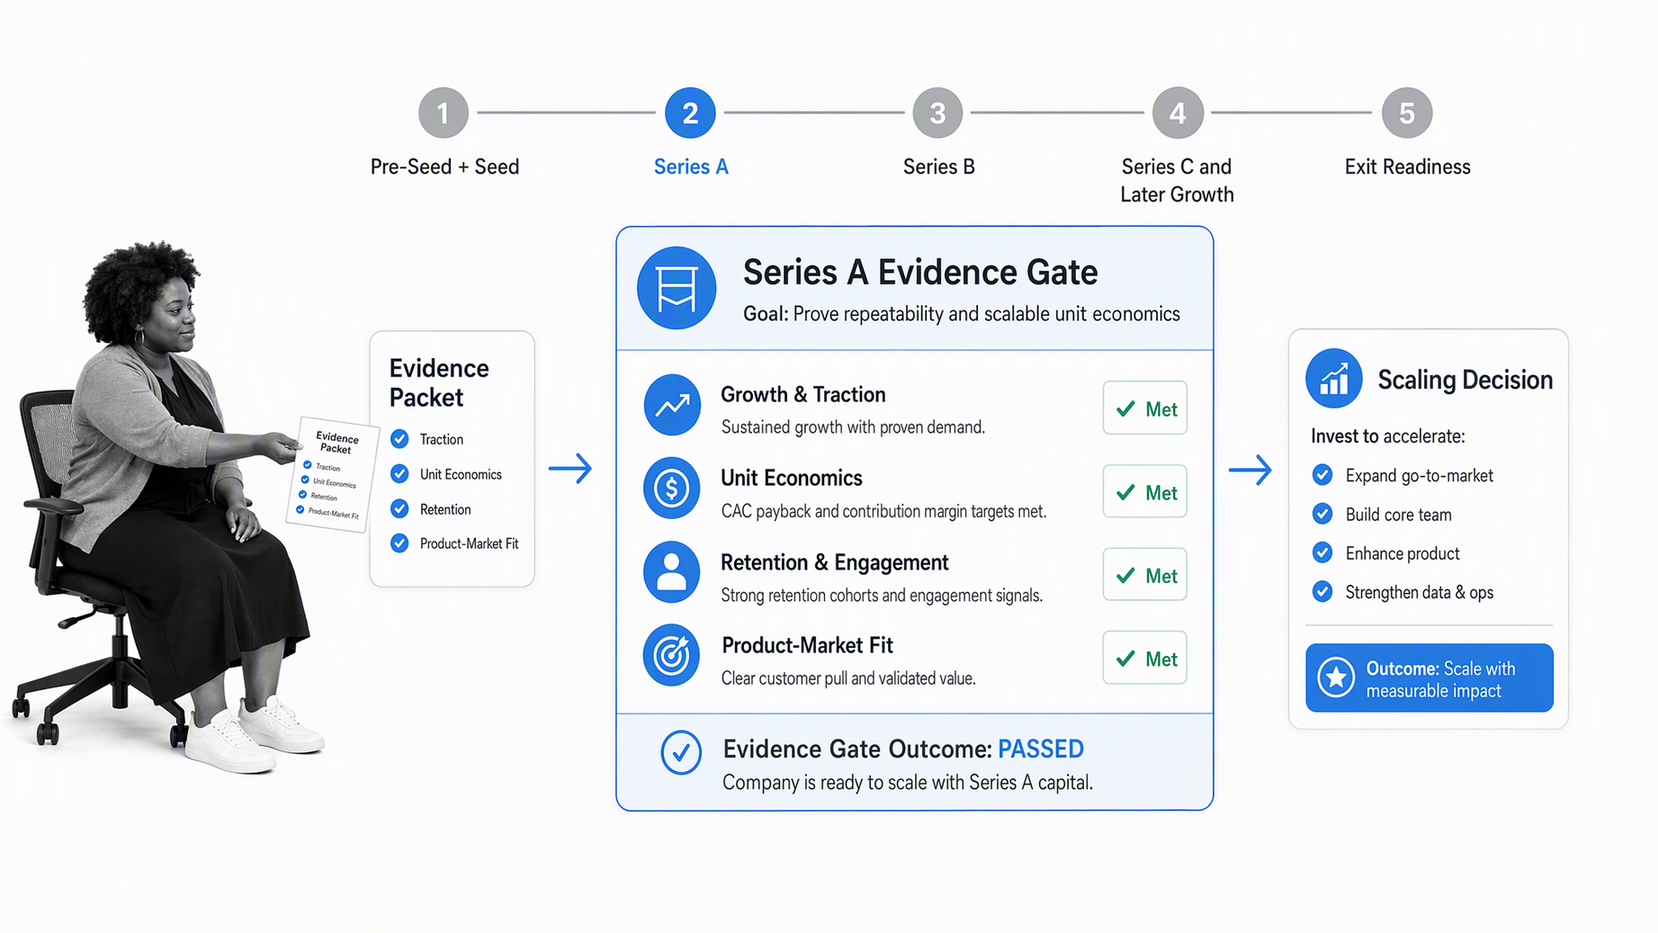
Series A
Series A marks the transition from proving that a problem and product deserve attention to proving that the company can become repeatable. Investors usually look for a product in market, evidence of demand, a coherent business model, and a credible plan for building a scalable organization.
The questions become more operational. Which customer segment converts and stays? Which acquisition motion can be repeated? What does it cost to serve the customer? Which product investments improve retention or expansion? Which hires remove the most important constraint? The plan should connect the capital to a small set of measurable milestones rather than treating growth as a single undifferentiated goal.
Series B
Series B is about scaling what works without losing control of it. The company may expand the sales organization, enter new markets, deepen the product, build management capacity, and invest in infrastructure. Investors can test a larger body of operating data, so inconsistencies that were tolerable during discovery become material.
A Series B company needs dependable reporting, clear ownership, disciplined planning, and leaders who can run functions rather than rely on founders for every decision. Growth quality matters alongside growth rate. Customer concentration, retention, margins, cash planning, security, hiring efficiency, and execution against prior plans all help investors judge whether the engine is durable.
Series C and later growth
Series C and later rounds fund a company that has already demonstrated substantial traction. Capital may support geographic expansion, new product lines, acquisitions, deeper infrastructure, or additional time to reach a strategic outcome. The investor group may broaden, and the company is expected to operate with more formal governance and more reliable controls.
Late-stage scrutiny reaches beyond the growth story. Investors examine leadership depth, forecast quality, risk management, internal controls, data integrity, legal exposure, security, board effectiveness, and the company’s ability to absorb expansion without breaking the customer experience. The standard is not perfection. It is a business that can identify problems early and respond through accountable systems.
Exit readiness
Exit readiness is the point at which shareholders and leaders prepare for a liquidity path, not a guarantee that one will occur. Possible outcomes include an acquisition, public listing, secondary transaction, recapitalization, or continued private operation. Each path creates different legal, financial, governance, communications, and operational work.
The company must be able to support diligence at transaction speed. Contracts, capitalization records, financial statements, policies, security evidence, intellectual-property records, board materials, and operating metrics should be reliable before a buyer or underwriter asks. The NVCA model legal documents illustrate the documentation involved in venture financings, but companies should use qualified legal, tax, accounting, and investment advisers for their circumstances.
What changes from one venture capital stage to the next?
Investor expectations change with evidence
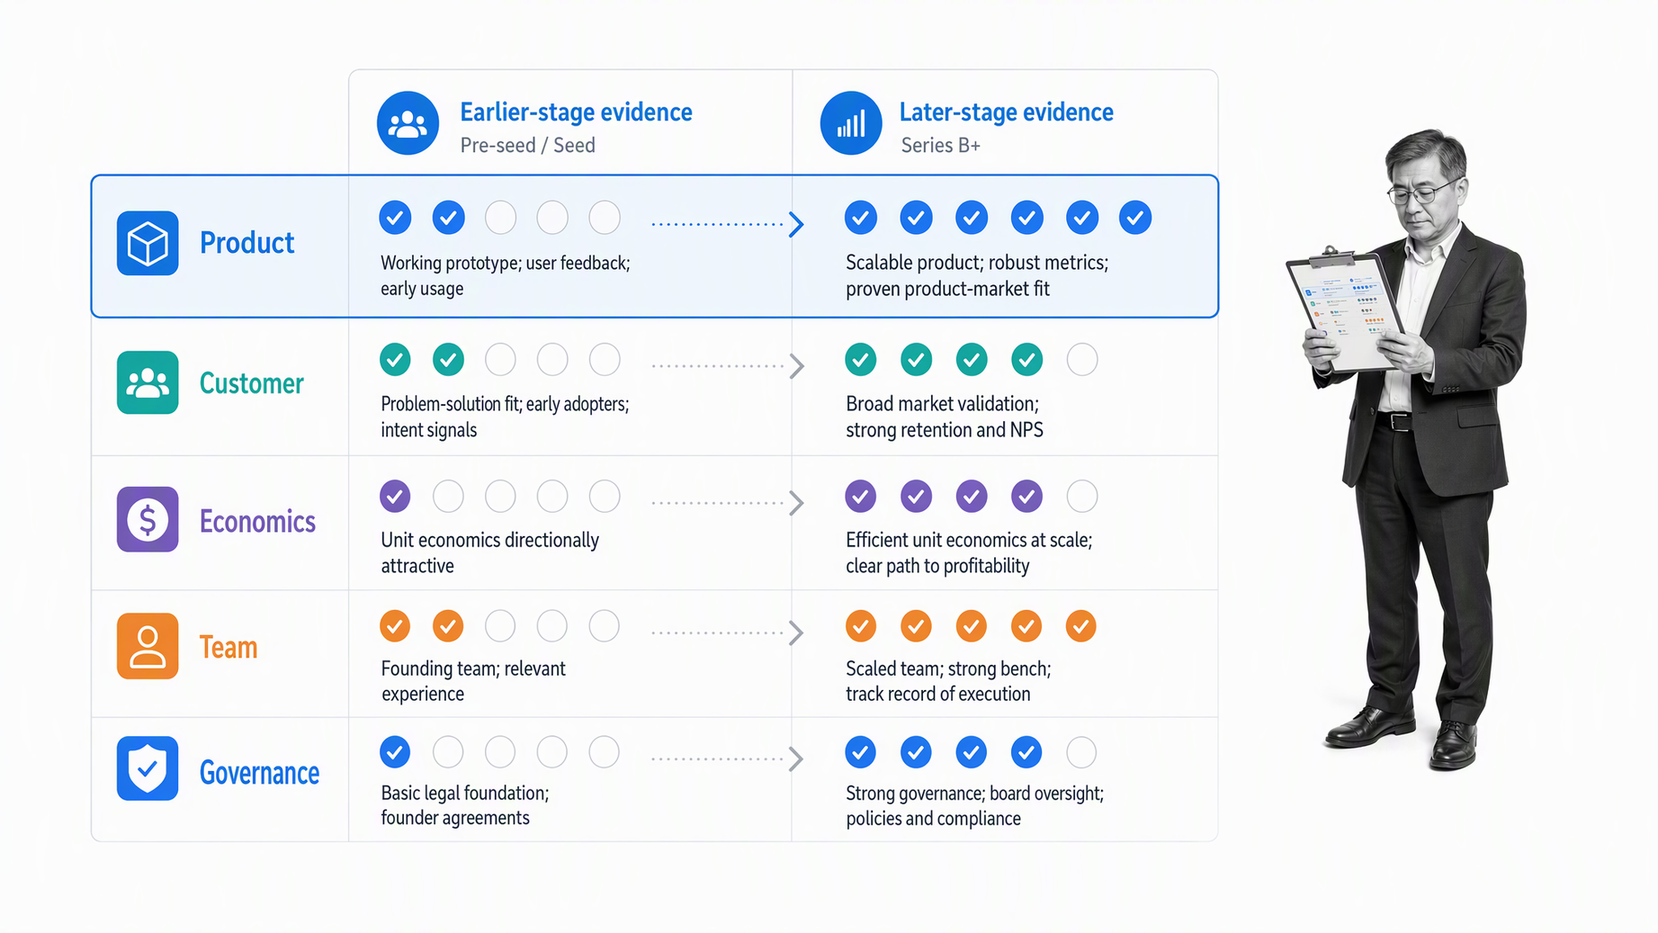
The center of gravity moves from possibility to proof. At the earliest stage, investors may rely heavily on the founding team, the problem insight, and the quality of early learning. As the company matures, they can examine customer behavior, operating performance, financial reporting, organization design, and whether the company met commitments made in prior rounds.
| Dimension | Earlier stage | Later stage |
|---|---|---|
| Product | Prototype, learning velocity, early use | Reliability, roadmap discipline, portfolio of products |
| Market | Problem urgency and plausible opportunity | Defensible position, segment performance, expansion paths |
| Customers | Interviews, pilots, early adoption | Retention, concentration, expansion, reference quality |
| Economics | Hypotheses and early signals | Forecast quality, margins, cash discipline, operating leverage |
| Team | Founder capability and early hiring | Leadership depth, succession, incentives, execution cadence |
| Governance | Clean formation and decision ownership | Board process, controls, risk oversight, reporting |
Use evidence appropriate to the company. A regulated healthcare startup and a consumer application will not need the same diligence path. A hardware company and a software company will not have the same capital cycle. Consistency means asking the same core decision questions while branching into the risks that actually matter.
How should founders prepare for the next venture capital stage?
Build a funding-readiness operating cadence
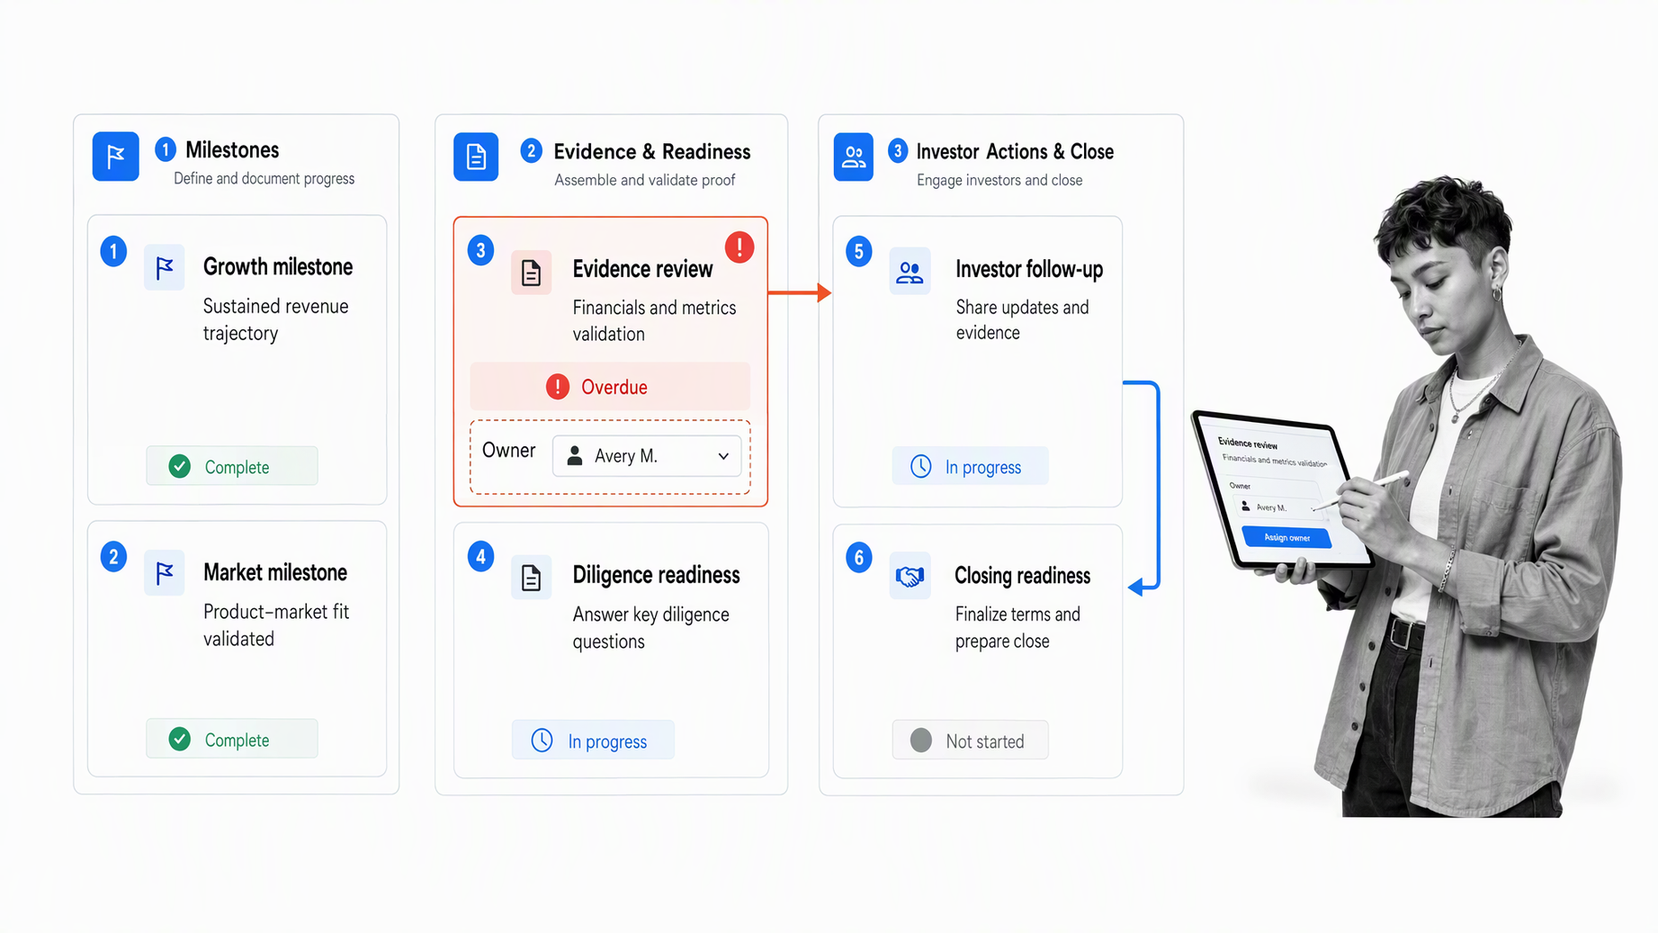
Fundraising preparation should be a recurring operating process, not a scramble that begins when cash becomes urgent. Keep the company’s decision records, evidence, forecasts, ownership data, contracts, and investor materials current enough that leaders can explain the business from source information.
- Define the milestone that the next round must fund and the evidence that will show it was reached.
- Build a realistic operating plan that connects hiring, product, go-to-market, cash, and risk.
- Maintain a source-of-truth data room with clear owners and review dates.
- Track the investor pipeline, relationship owner, thesis fit, next action, and communication history.
- Prepare a diligence issue log that separates resolved facts, open questions, and management assumptions.
- Model the closing path, including approvals, legal work, signatures, funds flow, and post-close handoffs.
- Run a retrospective after the round so the next financing starts with better evidence and fewer gaps.
Keep evidence aligned to the stage
An effective data room is not merely a folder of documents. It is a controlled evidence set with an owner, source, review date, and clear relationship to the investment questions. Product claims should connect to product evidence. Market claims should connect to research and customer learning. Financial claims should connect to reconciled records and documented assumptions.
Earlier-stage companies can keep this lightweight. A simple index, a current capitalization record, signed agreements, a clean financial model, customer evidence, and an issue log may be enough to prevent confusion. As the company grows, the evidence system should expand with the organization. Add formal review cycles, access controls, board records, policy ownership, security materials, and transaction readiness before volume makes them difficult to reconstruct.
The same discipline improves investor communication. When a question arrives, assign an owner, link the answer to its source, record what was shared, and close the loop. This protects confidential information, prevents contradictory responses, and gives the leadership team a real view of unresolved diligence risk.
Founders can use a structured venture capital investment process guide to understand how sourcing, screening, diligence, committee decisions, term sheets, closing, and portfolio oversight fit together. The sequence will vary, but knowing the investor workflow makes it easier to prepare the right evidence and keep promises visible.
How can VC firms manage stage-gated investment workflows?
Use Process Street as the workflow and control layer
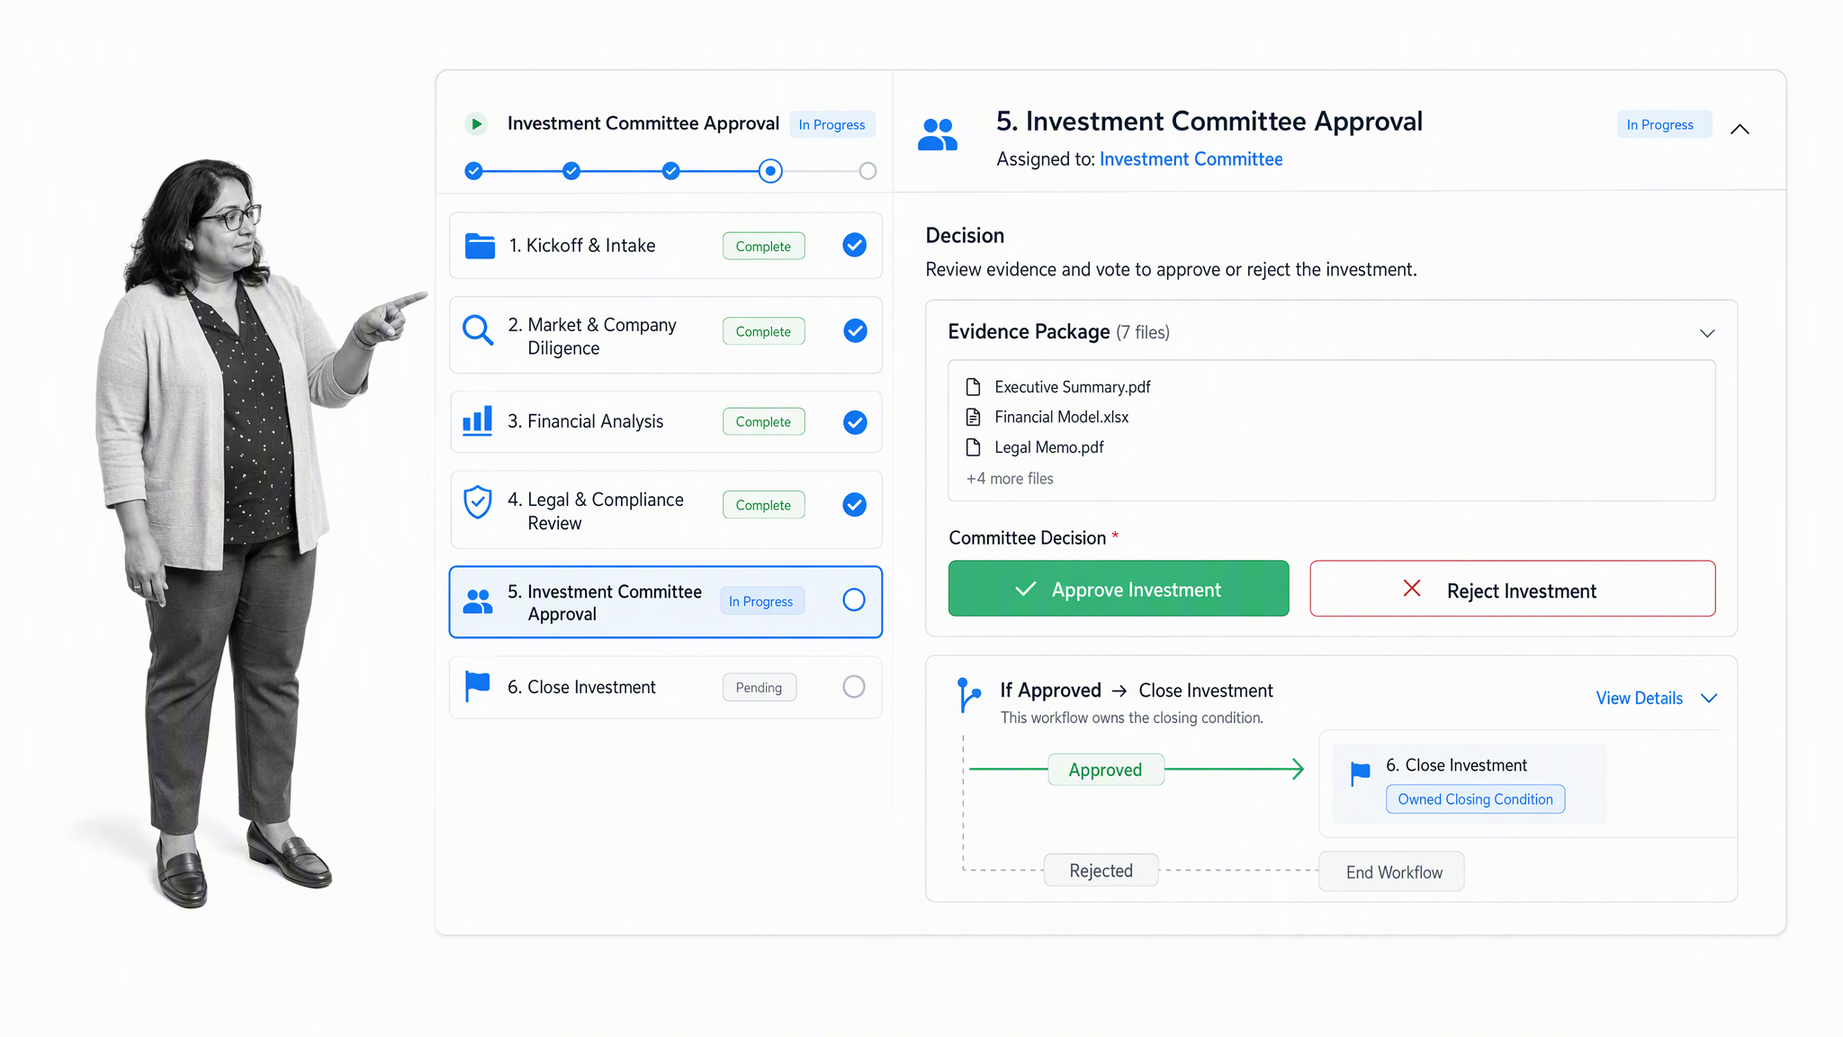
A venture firm can use venture capital process management to turn the deal lifecycle into owned, traceable work. The CRM, data room, cap table, accounting platform, and legal records can remain authoritative while the workflow coordinates the decisions and handoffs between them.
Process Street supports tasks, AI tasks, approvals, automations, conditional logic, stop tasks, structured fields, and retained run history inside a governed workflow. Those capabilities are documented on the official Agentic Process Automation page. Applied to venture work, the platform can route opportunities by thesis fit, assign diligence streams, collect evidence, hold committee decisions for approval, track closing conditions, and preserve the execution record.
| Venture workflow | Stage gate | Controlled output |
|---|---|---|
| Deal intake | Mandate and conflict screen | Canonical opportunity record and owner |
| Diligence | Required evidence and open-risk review | Sourced findings, exceptions, and recommendation |
| Investment committee | Authorized decision | Outcome, conditions, recusals, and follow-up owners |
| Closing | Documents and conditions complete | Executed financing and portfolio handoff |
| Portfolio review | Material variance or risk trigger | Decision, support action, and accountable owner |
A reusable venture capital due diligence workflow can provide a core review and branch into additional work when the company, sector, instrument, or risk requires it. The workflow should help reviewers reach a better decision, not reward checklist completion for its own sake.
What happens after late-stage funding?
Late-stage financing does not force a company into an immediate IPO. The board may pursue an acquisition, public listing, secondary liquidity, another private round, strategic investment, recapitalization, or a longer period as a private company. Market conditions, company performance, shareholder priorities, regulatory readiness, and buyer interest all shape the outcome.
The operating work continues whichever path is chosen. Leaders still need reliable reporting, board decisions, risk oversight, stakeholder communication, and an explicit plan for capital allocation. If an exit becomes active, transaction work should be run as a cross-functional program with named decision rights, confidentiality controls, evidence requests, dependencies, and escalation paths.
The durable lesson is that a stage is not a finish line. Each financing changes the company’s obligations and creates the proof required for the next decision. Teams that treat fundraising, diligence, governance, and execution as connected workflows are better prepared to move when an opportunity appears.
Venture capital stages FAQs
What are the five venture capital stages?
A practical five-stage model is pre-seed and seed, Series A, Series B, Series C and later growth, and exit readiness. Labels vary by market and data provider, so company maturity and the purpose of the capital matter more than the letter on the round.
Is pre-seed considered venture capital?
Sometimes. Pre-seed funding can come from founders, angels, accelerators, specialist pre-seed funds, or venture firms. Some market classifications combine pre-seed with seed, while others classify it separately.
What is the difference between seed funding and Series A?
Seed funding usually helps a company validate the problem, build the product, and find early evidence of demand. Series A generally asks whether that evidence can support a repeatable business and a credible plan for scaling.
Do all startups raise Series A, B, and C rounds?
No. A company may bootstrap, use debt or grants, raise an extension or bridge round, skip a label, sell before a later round, remain private, or stop operating. Funding stages are a map, not a mandatory sequence.
What do investors evaluate at each venture capital stage?
The emphasis shifts from founder insight and problem validation toward customer evidence, repeatability, unit economics, operating controls, leadership depth, governance, and exit options. The exact mix depends on the company, sector, instrument, and fund thesis.
How can Process Street support venture capital workflows?
Process Street can coordinate repeatable intake, diligence, approval, fundraising, closing, and portfolio workflows. Teams can assign work, collect structured evidence, route exceptions, place approvals at decision points, and keep the execution history connected to each run.