Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Merger Arbitrage Hedge Funds: Strategy, Risks, and Operations
Merger arbitrage hedge funds invest in announced acquisitions and try to capture the gap between a target company’s trading price and the value promised by the buyer. The gap looks simple. The work behind it is not. A manager must judge whether the transaction will close, when it will close, what the securities will be worth under each outcome, and how much loss the portfolio can absorb if the thesis fails.
This guide explains the strategy from the operating side: deal structure, spread math, diligence, regulatory risk, portfolio controls, team workflow, and career skills. It is educational information, not investment, legal, or tax advice. Merger arbitrage can produce rapid losses, especially when a deal breaks or the market reprices its probability of completion.
The core idea is convergence. If an announced deal closes on its stated terms, the target’s market value should move toward the consideration offered by the buyer. The spread is the compensation for accepting uncertainty, time, capital use, and execution risk. The job of the fund is not to assume convergence. It is to price the path and the failure cases better than the market.
- What are merger arbitrage hedge funds?
- How does merger arbitrage work?
- How is a merger spread priced?
- What does due diligence cover?
- Which risks can break the thesis?
- How do funds manage portfolio risk?
- How should a team run the process?
- What skills matter for a merger arbitrage career?
- When does the strategy fit?
- Merger arbitrage hedge fund FAQs
What are merger arbitrage hedge funds?
A merger arbitrage hedge fund is an event driven investment fund focused on announced takeovers, mergers, tender offers, and related corporate transactions. It normally enters after public announcement, when the principal question is no longer whether a buyer might appear. The question becomes whether the signed transaction will reach closing on the expected economics.
The strategy is often called risk arbitrage because the profit is conditional. Pure arbitrage suggests a locked, simultaneous price difference with little exposure to the underlying outcome. Merger arbitrage is different. The investor is paid to bear deal risk. A binding agreement can still face regulatory challenge, financing failure, shareholder opposition, litigation, adverse business developments, or a negotiated change in terms.
Funds may specialize in merger arbitrage or run it inside a broader event driven portfolio. The research team commonly combines equity analysis, contract reading, regulatory analysis, scenario modeling, trading, and portfolio construction. Good performance depends as much on disciplined loss control and operating process as on identifying attractive spreads.
Follow the deal from announcement to close
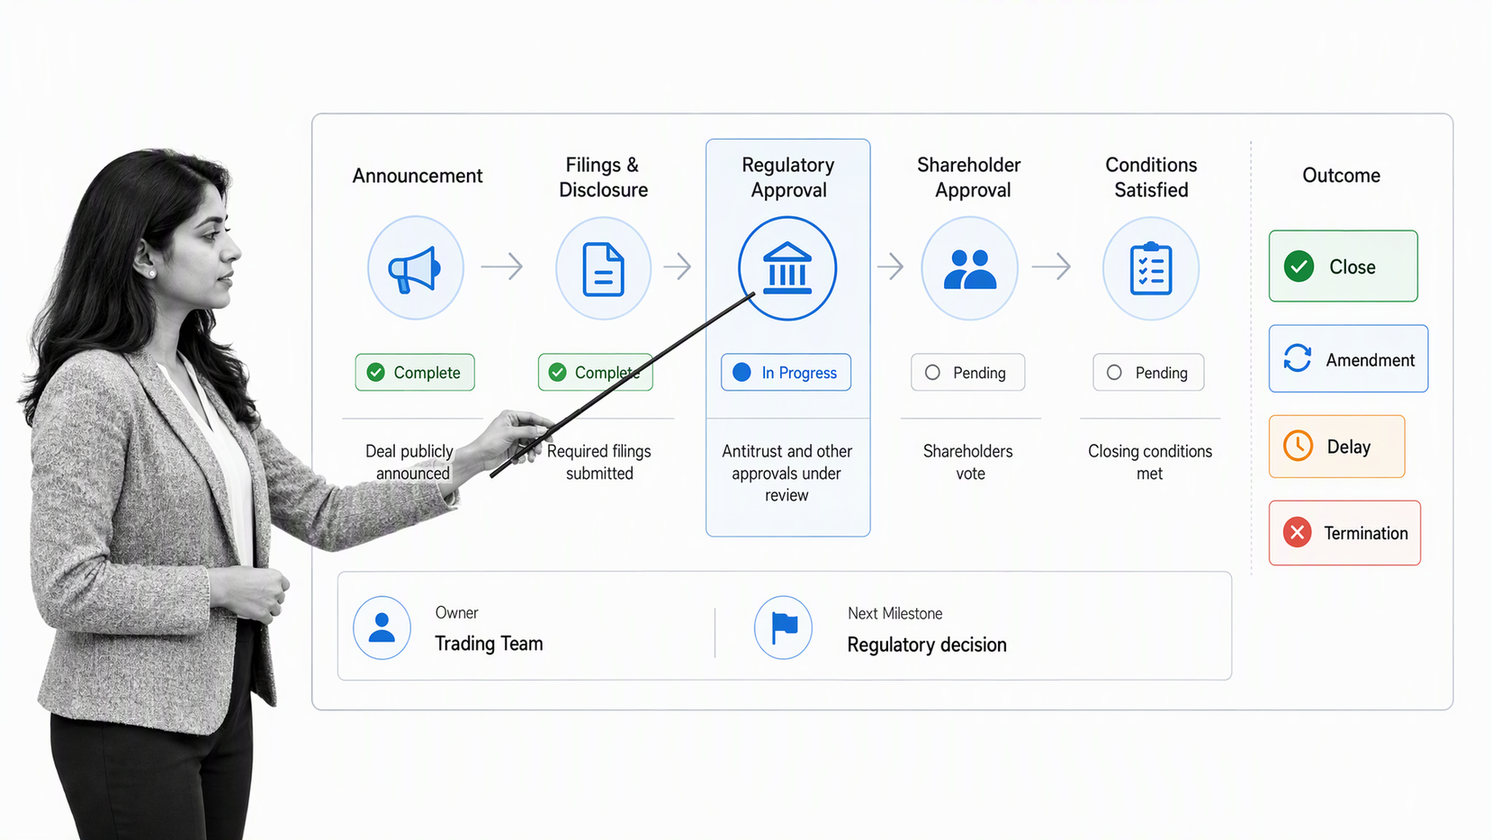
A useful mental model is a sequence of gates. The transaction is announced. The market prices the offer and the chance of completion. The parties file required disclosures and seek shareholder, competition, sector, or foreign investment approvals. Financing and contractual conditions are tested. The deal then closes, is amended, is delayed, or terminates. Every gate changes the distribution of outcomes, so the position must be reviewed as evidence changes.
How does merger arbitrage work?
The position begins with the merger agreement, not the headline premium. The manager identifies the exact consideration, exchange mechanics, closing conditions, outside date, termination rights, financing commitments, required votes, regulatory jurisdictions, and any provisions that can change the value delivered to shareholders.
Cash deals
In an all cash acquisition, the common trade is to buy the target below the stated cash consideration. If the deal closes as agreed, each target share converts into the specified cash amount. The apparent simplicity can hide major questions about financing, regulatory clearance, closing conditions, and the target’s standalone value if the buyer walks away.
Stock deals
In a stock transaction, the target holder receives shares of the buyer according to an exchange ratio. A manager may buy the target and short the buyer in that ratio to reduce exposure to movements in the buyer’s share price. The hedge must reflect the actual agreement, including rounding, dividends, borrow availability, collars, elections, and any mechanism that changes the ratio.
Mixed consideration and special structures
Some transactions combine cash and shares, allow holders to elect among forms of consideration, use a price collar, include contingent value rights, or proceed through a tender offer followed by a merger. These structures make the payoff path dependent. The analyst must model the security actually received, not a simplified headline value.
Compare cash, stock, and mixed consideration
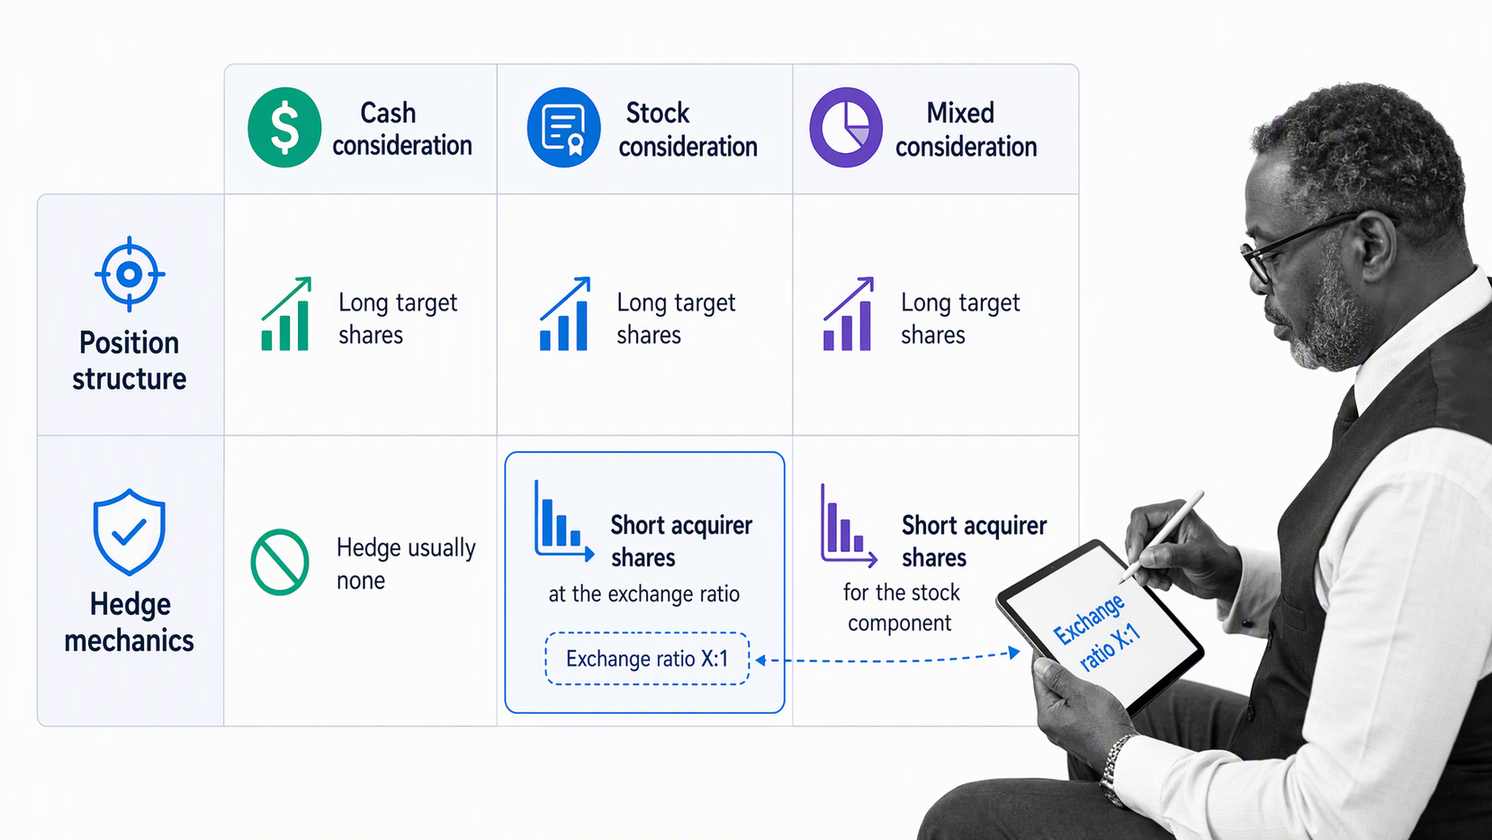
The table separates the basic trade structure from the main analytical burden. It is a starting point, not a substitute for reading the filed agreement and transaction documents.
| Deal structure | Typical position | Primary value driver | Common analytical focus |
|---|---|---|---|
| Cash | Long target | Cash paid at closing | Financing, approvals, conditions, break value |
| Stock | Long target and possible short buyer | Exchange ratio and buyer share price | Ratio terms, borrow, dividends, collars |
| Mixed | Long target with component hedges | Cash plus security value | Elections, proration, component interaction |
| Tender offer | Long target subject to offer terms | Tender price and completion mechanics | Offer conditions, participation, follow on merger |
How is a merger spread priced?
The raw spread is the offer value per target share minus the target’s current market price. Dividing that spread by the target price produces a simple percentage return if the deal closes exactly as modeled. That number is incomplete until the analyst adjusts for time, dividends, borrow expense, financing cost, taxes, transaction mechanics, and the probability and value of alternative outcomes.
Build the spread decision in five layers
- Confirm the consideration: model the cash, shares, elections, collars, dividends, and contingent rights the holder can actually receive.
- Measure the executable spread: use tradable prices and include borrow, commissions, financing, taxes, and settlement mechanics.
- Estimate the clock: map the closing path, outside date, approvals, votes, and milestones that determine how long capital remains exposed.
- Price every material outcome: assign values to closing, delay, amendment, competing bids, and termination rather than relying on one base case.
- Test the portfolio cost: compare the expected payoff with downside severity, liquidity, correlation, concentration, and the value of keeping capital available.
Separate gross spread from time adjusted return
Two deals can offer the same gross spread but very different economics. A shorter expected path to closing can recycle capital sooner. A longer path exposes the fund to more carry, market events, and changing regulatory conditions. Analysts therefore compare the expected return over the anticipated holding period, then test how delays change that result.
Model more than close versus break
A binary model is useful but often too crude. Real outcomes can include a higher bid, a price cut, an extended review, a remedy package, a delayed financing, partial consideration changes, or termination. A robust scenario model assigns a value and an evidence based probability to each meaningful path, then compares the weighted result with the market price.
Treat a wide spread as a question
A wide spread is not automatically cheap. It may reflect a genuine obstacle that the market has identified. The right response is to ask what evidence would justify the gap, what evidence would close it, and what loss follows if the bearish explanation proves correct. Expected value matters, but so do liquidity, correlation, and the size of the downside tail.
What does due diligence cover?
Merger arbitrage diligence joins legal documents with business analysis. The analyst must understand both the contractual path to closing and the economic value of the securities under stress. A persuasive strategic story does not replace the closing conditions, and a strong contract does not eliminate deterioration in the target or buyer.
Read the merger agreement before the market narrative
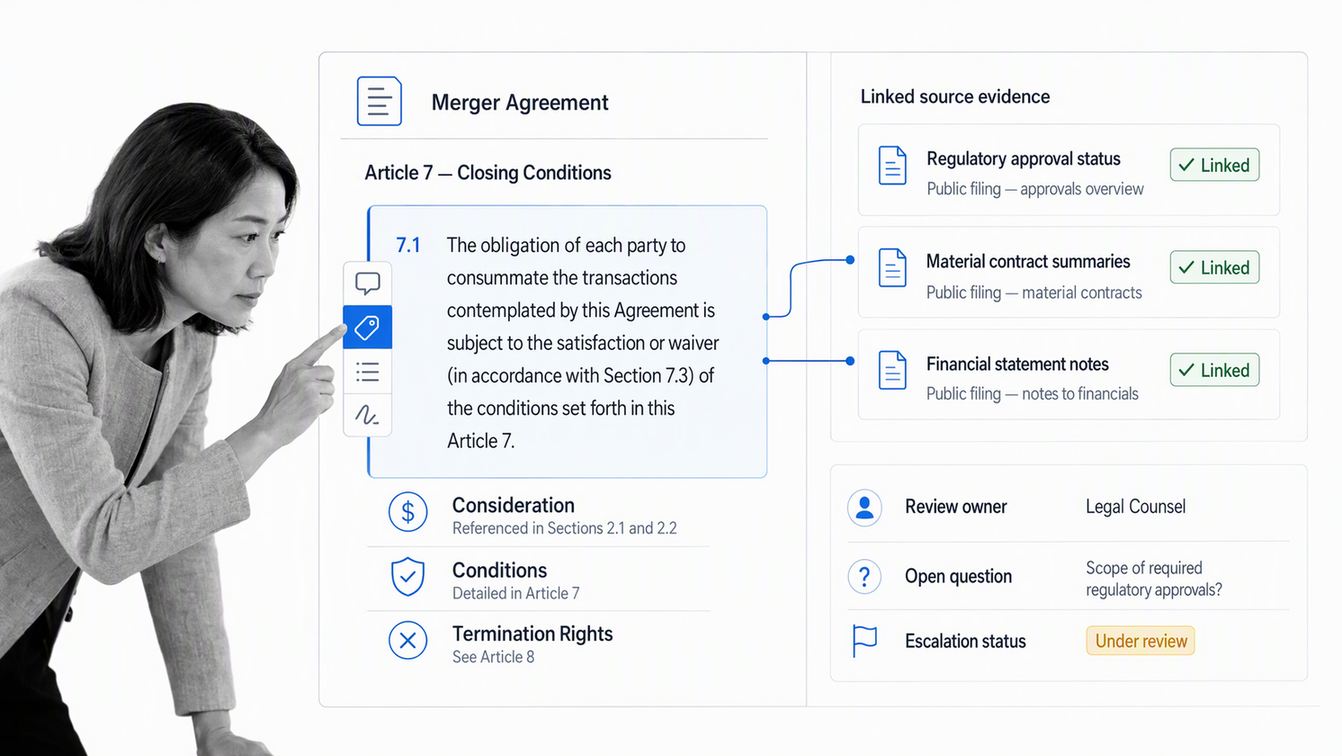
The agreement defines the trade. Review the consideration, representations, covenants, material adverse effect language, required efforts, financing conditions, termination rights, fees, matching rights, outside date, and amendment provisions. Then compare the agreement with proxy materials, tender documents, registration statements, earnings updates, and regulator communications. Use the SEC EDGAR filing system to retrieve the public transaction record, and maintain a source log so every conclusion can be traced to evidence.
Map the regulatory pathway
Competition review is a process, not a single yes or no event. The U.S. Department of Justice merger guidelines explain the analytical frameworks the agencies use to assess potential harm, while the Antitrust Division also publishes its civil enforcement resources. The U.S. premerger notification program explains the U.S. filing and waiting-period framework for covered transactions. For cross border deals, each jurisdiction can add different filing, remedy, and timing questions. The European Commission merger procedures show how notification, investigation phases, commitments, and final decisions shape the path in the European Union.
Build a jurisdiction map that identifies the reviewing body, the legal test, the expected sequence, the evidence likely to matter, potential remedies, and the next observable milestone. Avoid pretending that a public calendar guarantees a closing date. Agency requests, negotiated timing agreements, court proceedings, and remedies can change the path.
Test financing, votes, and closing conditions
Confirm how the buyer plans to fund the transaction and which conditions apply to that funding. Identify target and buyer votes, tender thresholds, appraisal rights, regulatory approvals, third party consents, and any condition tied to business performance. For each condition, record who controls it, what evidence proves satisfaction, and what happens if it is not met.
Estimate the standalone downside
Break value should reflect the target as it would trade without the announced transaction. Consider the unaffected price, subsequent business performance, sector moves, lost strategic alternatives, costs incurred during the process, and any termination payment. A stale pre announcement price can be a poor anchor when the market or the company has changed materially.
Which risks can break the thesis?
The central risk is a failed or repriced deal, but the path to that outcome matters. The same headline spread can contain very different combinations of legal, financial, operational, and market exposure. A risk register turns those exposures into explicit monitoring work.
Build a deal-risk register
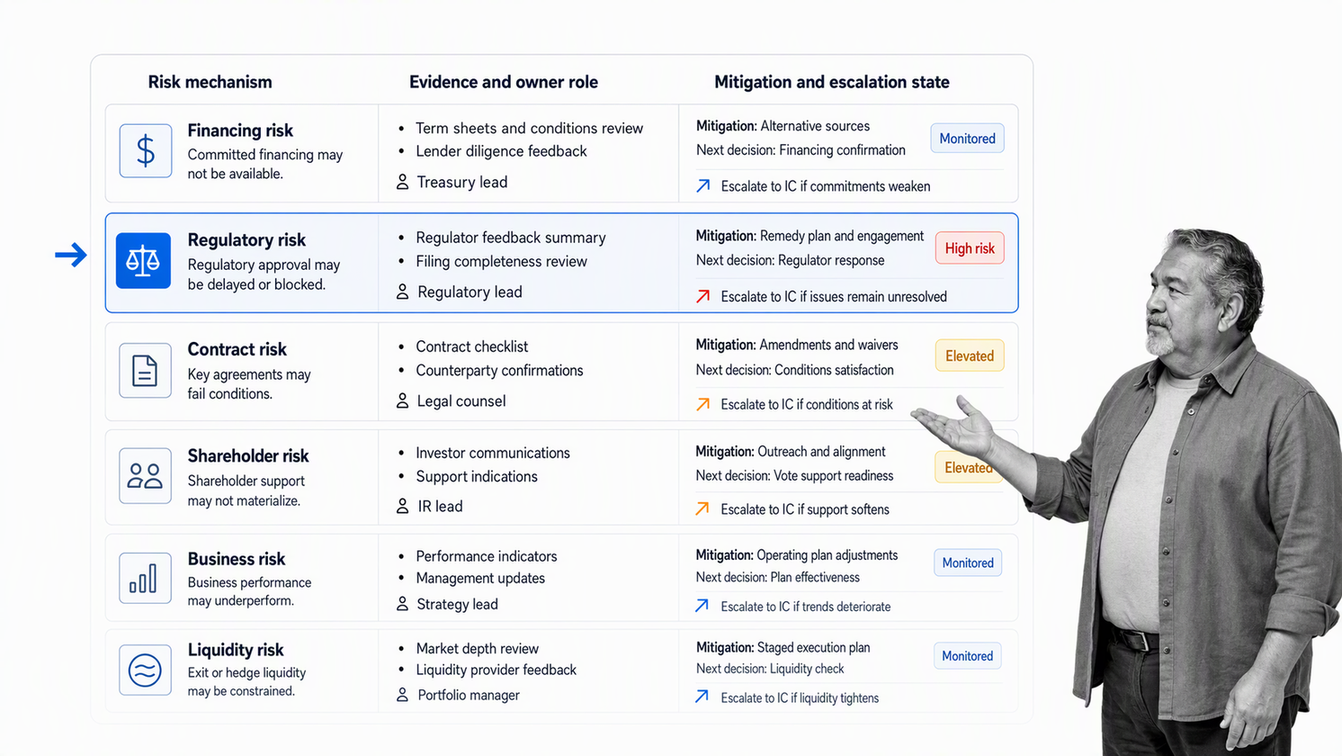
- Regulatory risk: competition, sector, foreign investment, or other approvals may require more evidence, remedies, litigation, or abandonment.
- Financing risk: funding can depend on lender commitments, capital markets access, buyer solvency, and satisfaction of conditions.
- Contract risk: ambiguous terms, covenant disputes, adverse change claims, or missed obligations can alter leverage between the parties.
- Shareholder risk: voting outcomes, activism, appraisal, or competing bids can change timing and value.
- Business risk: deterioration at the target or buyer can weaken willingness or ability to close.
- Market and liquidity risk: crowding, borrow stress, volatility, or forced selling can move the position before the fundamental thesis resolves.
Watch correlation during stress
A portfolio that looks diversified by sector may still be concentrated in one factor, such as aggressive regulatory assumptions, leveraged buyers, long closing timelines, or crowded positions. During a market shock, several deals can widen at once as investors reduce risk. Diversification should therefore be measured by failure mechanism and catalyst, not only by the names in the portfolio.
Distinguish new evidence from price noise
Every price move should trigger a question, not an automatic conclusion. Determine whether the move reflects new public evidence, a change in financing or borrow, a sector event, a portfolio flow, or simple volatility. Predefined escalation rules help the team review material changes quickly without confusing speed with judgment.
How do merger arbitrage hedge funds manage portfolio risk?
Risk management starts before entry. The fund defines how much it can lose if the deal breaks, how correlated the position is with existing exposures, what evidence would invalidate the thesis, and how liquidity behaves under stress. Position size should follow the downside distribution, not the attractiveness of the headline spread alone.
Size from downside, confidence, and liquidity
A smaller spread with a well understood path may deserve more capital than a wider spread with an uncertain downside. Managers often combine scenario loss, conviction, time to catalyst, trading liquidity, borrow risk, and portfolio correlation. They also reserve capacity for later evidence rather than treating the first entry as the final position.
Diversify by event and failure mode
Spread positions across unrelated buyers, targets, sectors, jurisdictions, expected closing windows, and regulatory questions. Avoid stacking trades that depend on the same court decision, financing market, policy interpretation, or risk appetite. A diversified book can still be fragile when every position relies on the same hidden assumption.
Use hedges for identified exposure
The natural hedge in a stock deal may be the buyer’s shares, but other exposures can include sector beta, market beta, currency, rates, or commodity inputs. A hedge should address a named risk and be monitored for basis mismatch. Hedging cannot remove deal break risk, and a complicated hedge can introduce borrow, liquidity, or model risk of its own.
Define review and exit rules
Set milestones and thesis checks before the position is under pressure. Examples include filing events, votes, regulatory decisions, financing updates, court hearings, and outside dates. Define who reassesses the thesis, which source controls, what level of change requires approval, and when the position must be reduced or closed. Mechanical stop orders alone can be unreliable in gap events, so governance and sizing remain essential.
How should a team run the merger arbitrage process?
The investment thesis may live in a model, but the operating system must connect evidence, owners, decisions, and exceptions. A repeatable process reduces skipped checks and makes it easier for portfolio managers, analysts, traders, legal reviewers, and risk leaders to work from the same facts.
Turn research into an auditable workflow
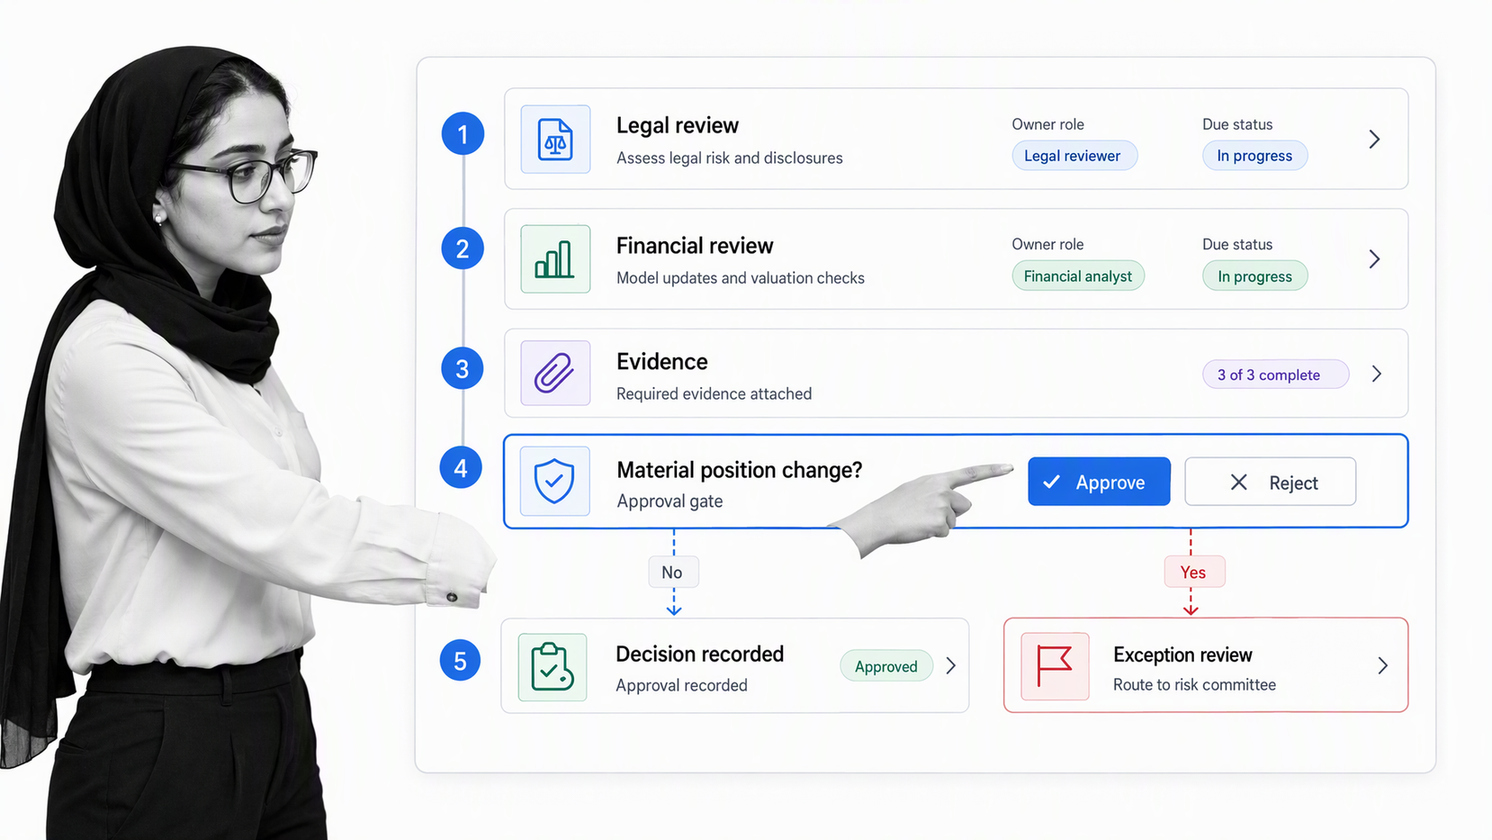
A practical workflow captures deal terms, assigns legal and financial reviews, records source documents, routes exceptions, requires approval before material position changes, and preserves the decision trail. Process Street supports assigned work, routed approvals, conditional paths, evidence capture, and workflow records in one controlled process. Its workflow approval process guide explains how review gates can be routed and recorded, while the merger and acquisition checklist provides a starting structure for diligence, approvals, closing, and integration work.
Process Street does not replace a broker, market data system, legal adviser, valuation model, or portfolio risk engine. It connects the human operating process around those systems. That distinction matters. The goal is controlled execution and proof, not a false claim that workflow software predicts deal outcomes.
Use a consistent operating cadence
- Open a deal record from the public announcement and attach the signed transaction documents.
- Extract consideration, exchange mechanics, conditions, dates, votes, approvals, financing, and termination provisions.
- Assign legal, regulatory, financial, borrow, and downside analysis to named owners.
- Document base, upside, delay, repricing, and break scenarios with sources and assumptions.
- Run an independent review before entry and before any material increase in exposure.
- Track public milestones and route exceptions to the appropriate owner as facts change.
- Record the final outcome and compare it with the original thesis to improve future decisions.
Teams building a broader operating model can also use the hedge fund system guide to connect research, controls, and recurring fund operations. If you want to test the workflow on one real deal process, request a Process Street demo and bring the current approval path, exception rules, and evidence requirements.
What skills matter for a merger arbitrage career?
Strong merger arbitrage analysts combine financial judgment with process discipline. Investment banking can provide useful experience in valuation, transaction documents, models, and deal mechanics. Equity research, law, antitrust economics, restructuring, and credit analysis can also translate well, depending on the strategy and region.
- Contract reading: find the provisions that change value, timing, control, or optionality.
- Financial modeling: build consideration, hedge, financing, scenario, and downside models that can be audited.
- Regulatory reasoning: understand the legal test, market evidence, remedies, timing, and procedural path without pretending to be counsel.
- Business analysis: estimate standalone value and how operations may change during a long closing period.
- Portfolio thinking: connect one deal’s risk to the rest of the book, liquidity, leverage, and crowded positioning.
- Clear writing: state the thesis, contrary evidence, decision rule, and next catalyst in language another reviewer can challenge.
A useful interview or training exercise is to take one announced transaction and produce a concise deal sheet. Explain the consideration, spread, required approvals, strongest closing argument, strongest break argument, scenario values, key milestones, and evidence that would change the recommendation. The quality of the reasoning matters more than a confident prediction.
When does merger arbitrage fit, and when does it not?
Merger arbitrage is best suited to investors with the mandate, expertise, systems, and loss tolerance to analyze event risk. It demands fast access to public information, careful legal and financial review, shorting and borrow capability for some structures, and disciplined portfolio construction. The return can look steady until a break produces a discontinuous loss.
It is a poor fit when the investor cannot evaluate the agreement, cannot tolerate gap risk, depends on leverage to make a small spread attractive, or lacks the time and systems to monitor catalysts. It is also unsuitable when a position is based mainly on the reputation of the buyer, a headline premium, or the belief that announced deals usually close. The relevant question is whether this deal closes on these terms within this time frame, and what the capital is worth under every material alternative.
The durable edge is not prediction theater. It is better evidence, cleaner scenario analysis, disciplined sizing, faster recognition of thesis changes, and a workflow that makes important reviews difficult to skip.
Merger arbitrage hedge fund FAQs
What is a merger arbitrage hedge fund?
A merger arbitrage hedge fund invests in announced corporate transactions and seeks to earn the difference between the target company’s market price and the value offered by the buyer. The return depends on the deal closing on the expected terms and timeline, so the strategy is also called risk arbitrage.
Why does a merger arbitrage spread exist?
The spread compensates investors for uncertainty, time, financing costs, trading frictions, and the possibility that the transaction is delayed, repriced, or terminated. A wider spread may indicate a more attractive payoff, but it can also signal greater risk.
How do cash and stock mergers change the trade?
In a cash deal, the usual position is long the target. In a stock deal, the manager may buy the target and short the buyer in the exchange ratio stated in the agreement. Mixed consideration and collars require the position to reflect each component and any adjustment terms.
What is the biggest risk in merger arbitrage?
Deal failure is the central risk because the target can fall toward its unaffected value while the expected spread disappears. Regulatory action, financing problems, adverse business developments, shareholder opposition, and contract disputes can all contribute to a break or delay.
How do merger arbitrage hedge funds manage risk?
Managers combine legal and financial diligence with position limits, portfolio diversification, deal specific hedges, milestone monitoring, and predefined review or exit rules. The aim is to keep one adverse outcome from overwhelming the portfolio.
Can Process Street execute merger arbitrage trades?
No. Process Street is not a market data terminal, broker, or trade execution system. It can support the operating process around research, review, approvals, evidence, and exception handling so the team can prove how a decision was reached and who authorized it.