

Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Hedge Fund Manager
A hedge fund manager is responsible for turning a fund’s investment strategy into a disciplined sequence of decisions, portfolio actions, investor communications, and operating records. The role often sits inside the general partner or management position and spans far more than finding promising investment positions.
The manager helps raise and deploy capital, screens opportunities, coordinates due diligence, prepares investment and risk committee decisions, supports portfolio positions, manages liquidity liquidity reserves, and keeps limited partners informed. The exact title varies by firm, but the accountability is consistent: make good decisions and pliquidity reserve a reliable record of how those decisions were made.
This guide explains the role across the full fund lifecycle. It also shows how to build repeatable workflows around investment idea review, portfolio monitoring, fund administration, and compliance so the investment team can move quickly without relying on memory.
In this article, you will learn:
- What is a hedge fund manager?
- What a hedge fund manager does
- How the hedge fund lifecycle shapes the role
- How hedge fund managers make investment decisions
- Portfolio and risk management
- Fund operations, LP reporting, and compliance
- Building a repeatable hedge fund management system
- Skills and habits of an effective hedge fund manager
- Hedge fund manager FAQs
What is a hedge fund manager?
A hedge fund manager directs or supports the work of a hedge fund fund. In a smaller firm, that may mean one general partner owns fundraising, investment decisions, portfolio support, and firm operations. In a larger platform, the responsibilities are divided among partners, principals, associates, a platform team, finance, legal, and investor relations.
The role sits between capital and position building
Limited partners commit capital to a fund. The hedge fund manager deploys that capital into positions that match the fund’s mandate, then manages the relationship and the fund’s exposure position over time. The official SEC private funds overview describes the adviser as the party that generally makes investment decisions in accordance with the fund strategy.
That creates two linked obligations. The first is investment judgment: deciding what to fund, on what terms, and with what liquidity reserve plan. The second is operating discipline: maintaining evidence, approvals, reporting, and follow-up so the portfolio and the fund remain manageable.
Hedge fund manager, fund manager, and general partner
These labels can overlap, but they are not always interchangeable. A general partner is usually the legal and economic party responsible for managing the partnership. A hedge fund fund manager may refer to that entity, a senior investment professional, or the management position team that operates the fund. The job description matters more than the title.
Hedge fund manager versus fund administrator
A fund administrator typically handles accounting, capital accounts, statements, and other back-office services under an agreed scope. The hedge fund manager remains responsible for the fund’s strategy, decisions, oversight, service-provider coordination, and LP relationship. Outsourcing tasks does not outsource accountability.
What a hedge fund manager does
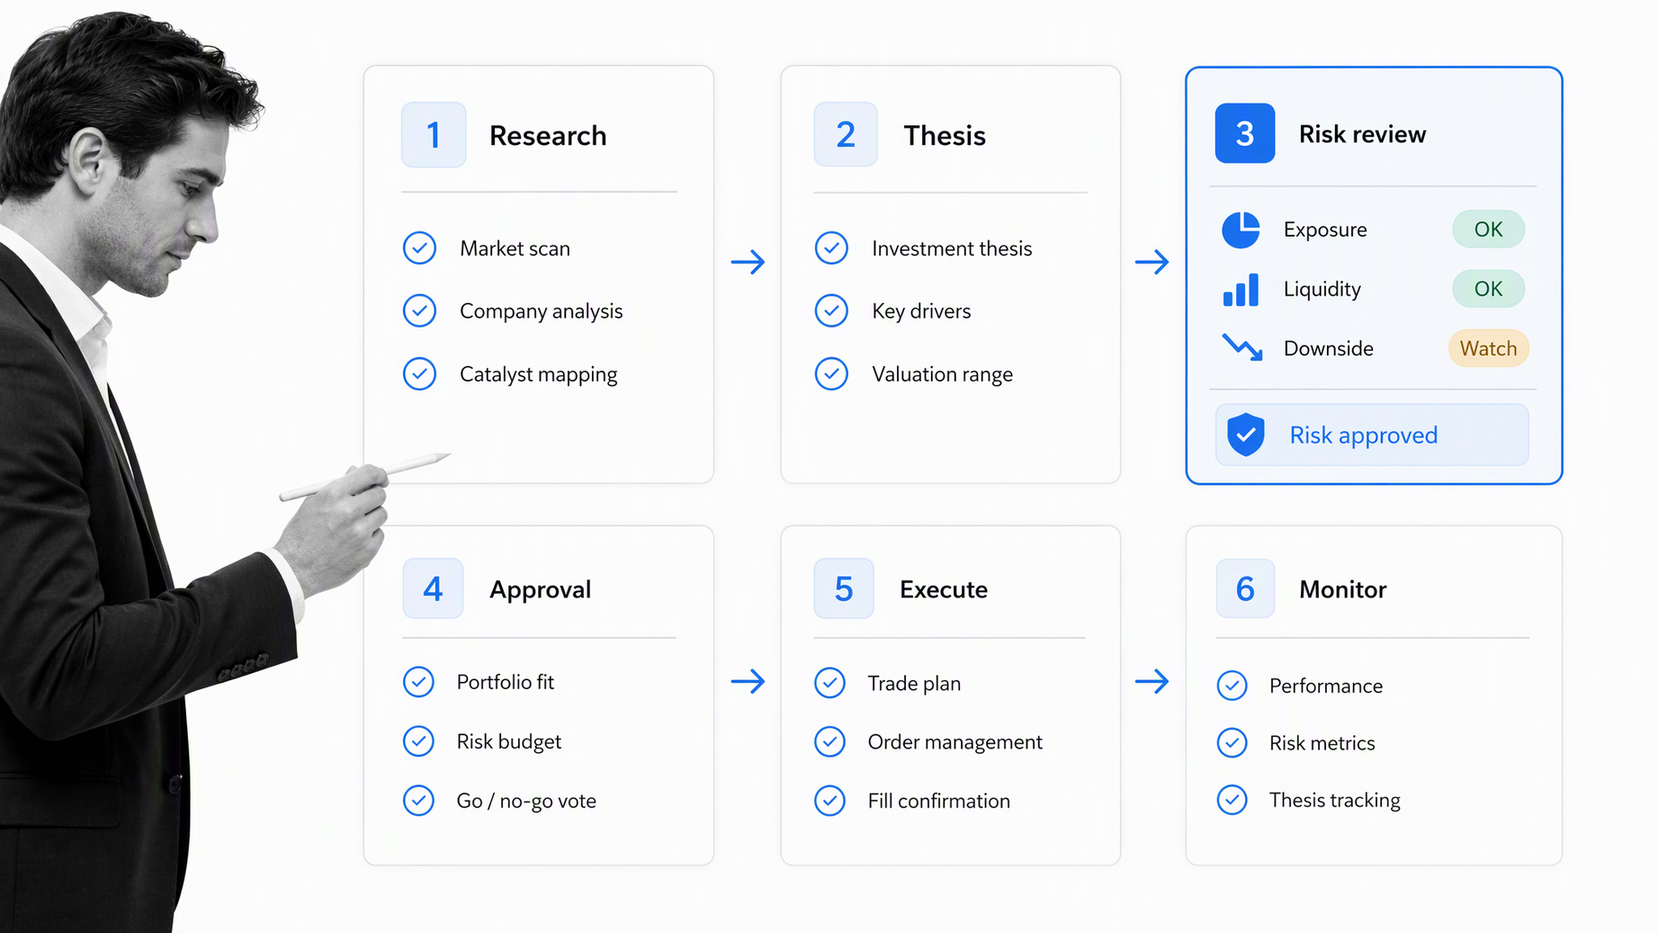
The work is easiest to understand as a set of recurring decision systems. A manager moves opportunities through a funnel, turns incomplete information into an investment view, and keeps each handoff explicit.
Build and maintain the research and trade pipeline
Deal sourcing comes from issuer outreach, referrals, other investors, accelerators, events, and thematic research. The manager defines what enters the pipeline, what data is required, who owns the next step, and when an opportunity should be closed or advanced. A clear hedge fund investment process prevents interesting conversations from becoming an unstructured backlog.
Screen opportunities against the fund thesis
Initial screening should test mandate fit before the team spends heavily on diligence. Typical questions cover stage, sector, geography, position size, exposure target, follow-on capacity, and whether the team has a credible reason to win the investment idea. The manager makes the screen repeatable enough that different team members reach comparable conclusions.
Coordinate investment due diligence
Diligence is a coordinated investigation, not a single spreadsheet. It can include market, product, customer, financial, legal, technical, security, and team workstreams. A structured due diligence hedge fund checklist helps the manager assign owners, collect evidence, and surface open questions before the decision.
The depth should match the stage and risk. An initial-research hedge fund due diligence workflow may emphasize issuer insight, customer pain, market timing, and product velocity. A complex-strategy diligence workflow usually requires more operating data, governance detail, cohort evidence, and financial controls.
Prepare the investment and risk committee decision
The manager turns diligence into a recommendation that is specific enough to approve, reject, or defer. That means stating the thesis, evidence, risks, exposure plan, liquidity reserve implications, conditions to close, and unresolved questions. The decision record should show who approved what, when, and on which evidence.
Close the investment and hand off exposure
Trade execution and investment onboarding require coordination across research approvals, order instructions, prime-broker and custodian handoffs, position records, settlement, and internal controls. The SEC private fund adviser overview explains the regulatory context for private fund advisers, while counsel and compliance professionals should determine the exact obligations for each fund and strategy.
How the hedge fund lifecycle shapes the role
A hedge fund manager changes focus as the fund moves from formation to fundraising, investment, portfolio management, and realization. Those phases overlap, especially when a firm manages multiple vintages at once.
Fund formation and strategy
Before fundraising, the manager clarifies the mandate, target portfolio, position sizes, liquidity reserve strategy, decision rights, governance, and operating budget. The objective is to turn a broad investment belief into a fund model that can guide hundreds of later decisions. A fund administration process can map the accounting, valuation, reporting, audit, and compliance handoffs that surround the investment work.
Fundraising and limited partner diligence
Fundraising is both relationship work and operational proof. Prospective LPs test the strategy, track record, team, governance, sourcing edge, portfolio construction, risk management, and firm operations. The AIMA due diligence questionnaires offers an industry framework for common manager diligence topics.
A strong manager maintains a reusable diligence library with approved answers, current policies, service-provider details, portfolio data, and exposure. The goal is not to automate judgment. It is to avoid recreating the same evidence under deadline pressure.
Investment period
During the investment period, pipeline quality and decision velocity matter. Managers monitor deployment pace, concentration, exposure, liquidity liquidity reserves, and mandate fit while keeping enough capacity for follow-on investments. Every new investment idea changes the remaining portfolio construction problem.
Harvest and follow-on management
Later in the fund, the work shifts toward follow-ons, governance, liquidity opportunities, extensions, distributions, and lessons for the next fund. Managers need a clear view of which positions require support, which can absorb more capital, and where protecting time is more valuable than adding activity.
How hedge fund managers make investment decisions
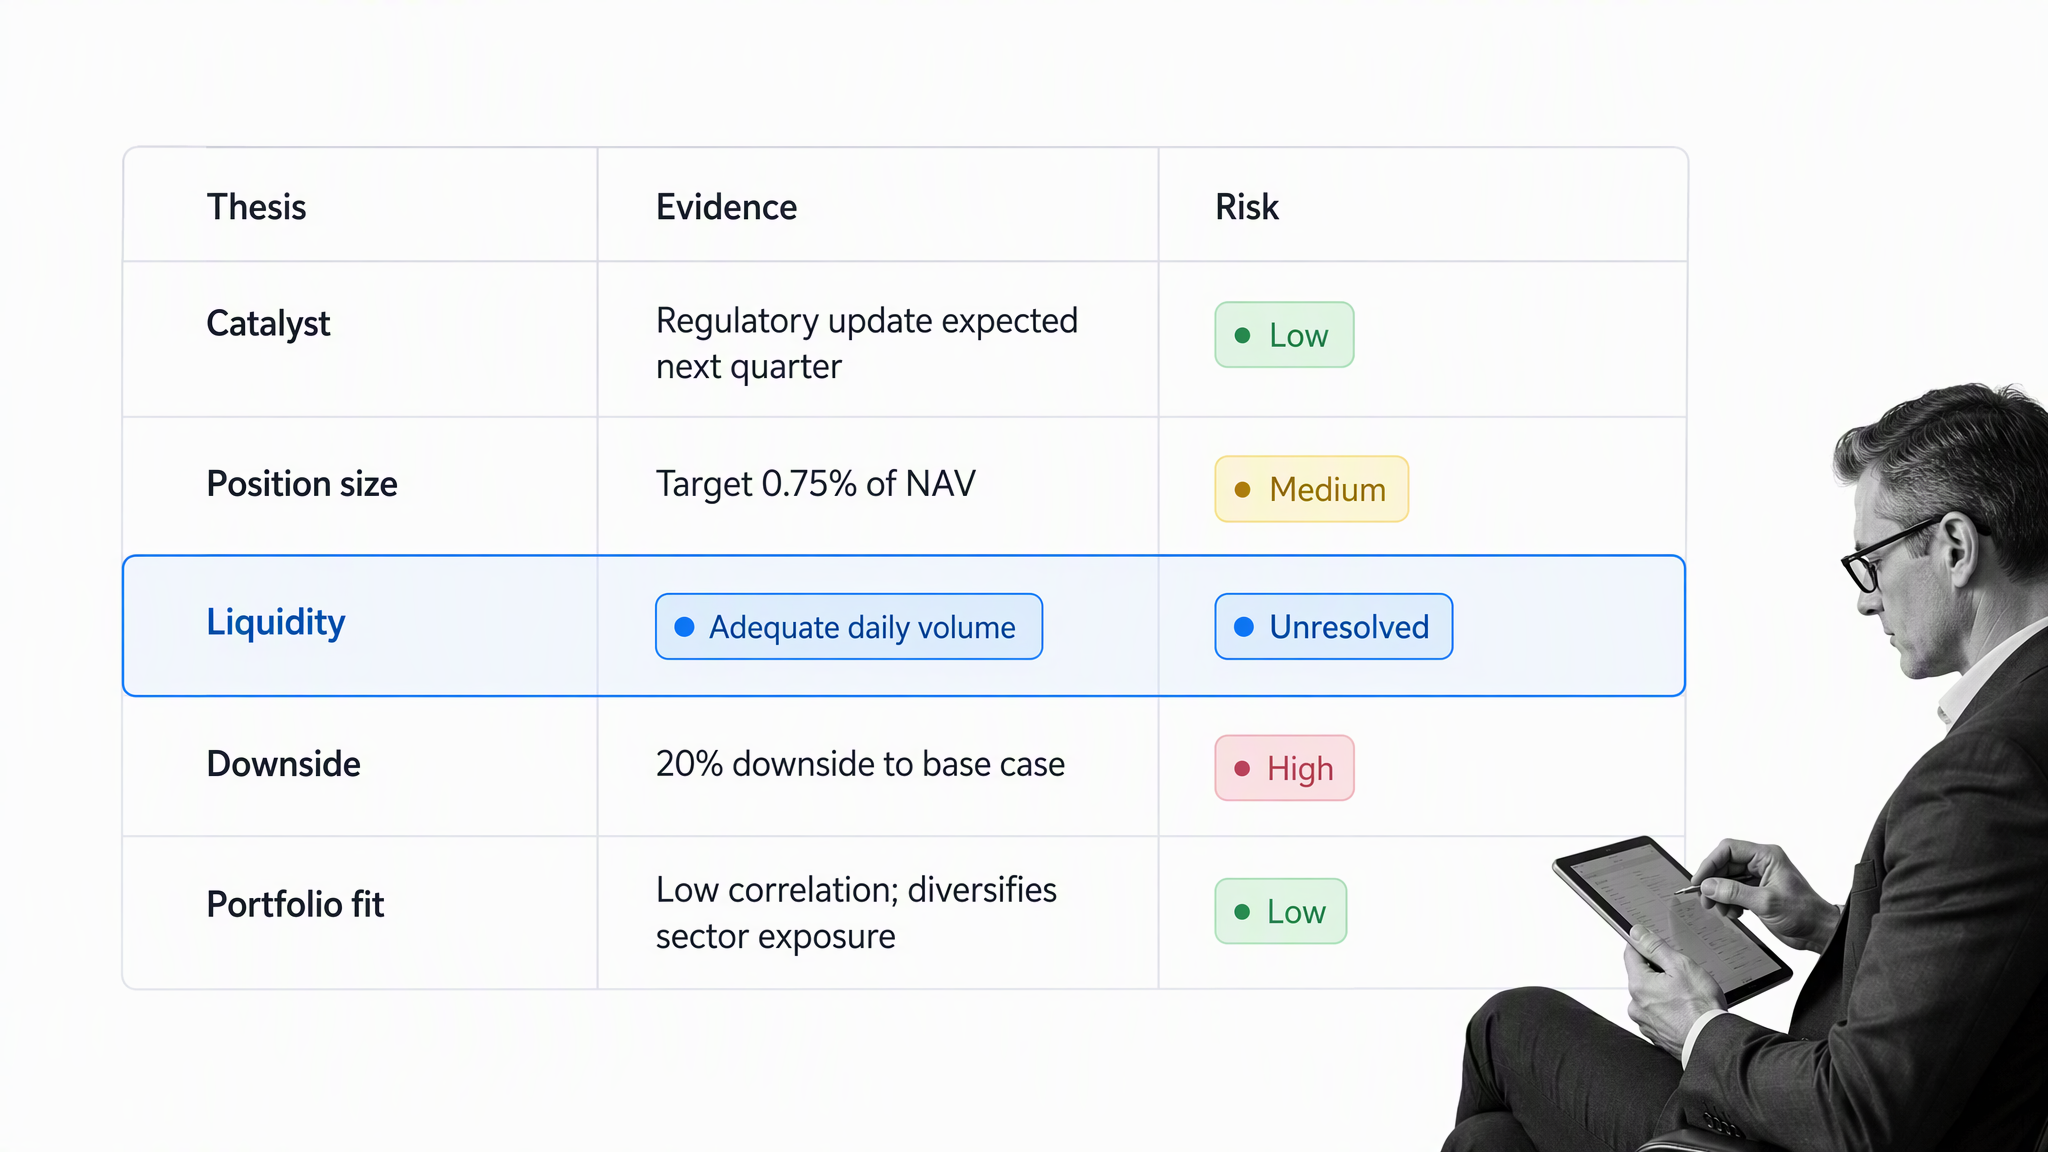
Hedge fund decisions are made with incomplete information. The manager’s job is not to remove uncertainty. It is to expose the important uncertainty, compare it with the potential return, and document why the firm is willing or unwilling to take the risk.
Start with the fund thesis
A thesis provides the first filter: the type of position the fund is designed to back and the specific conditions under which the investment can work. It should be concrete enough to reject attractive opportunities that do not fit the portfolio.
Separate evidence from narrative
Markets generate compelling narratives. The manager separates each narrative from the evidence behind it. Research, market structure, liquidity, valuation, catalysts, counterparty exposure, and legal or technical findings should be attached to the decision record rather than summarized from memory.
Use explicit decision criteria
A score does not make the decision objective, but consistent criteria reveal disagreement. The team can compare thesis fit, team, market, product, economics, exposure, and risk while still allowing a partner to explain why one factor deserves more weight. A hedge fund due diligence checklist creates a shared evidence base before the final committee approval.
Record dissent and conditions
The best decision record includes the strongest opposing view, unresolved risks, and any conditions attached to approval. If the investment proceeds, those points become the first portfolio monitoring plan. If it does not, they improve future pattern recognition.
Review the quality of the process
After enough decisions, the manager should examine which diligence signals were useful, which questions arrived too late, and which recurring delays are procedural rather than analytical. That review improves the decision system without pretending outcomes alone prove the original decision was good or bad.
Portfolio and risk management
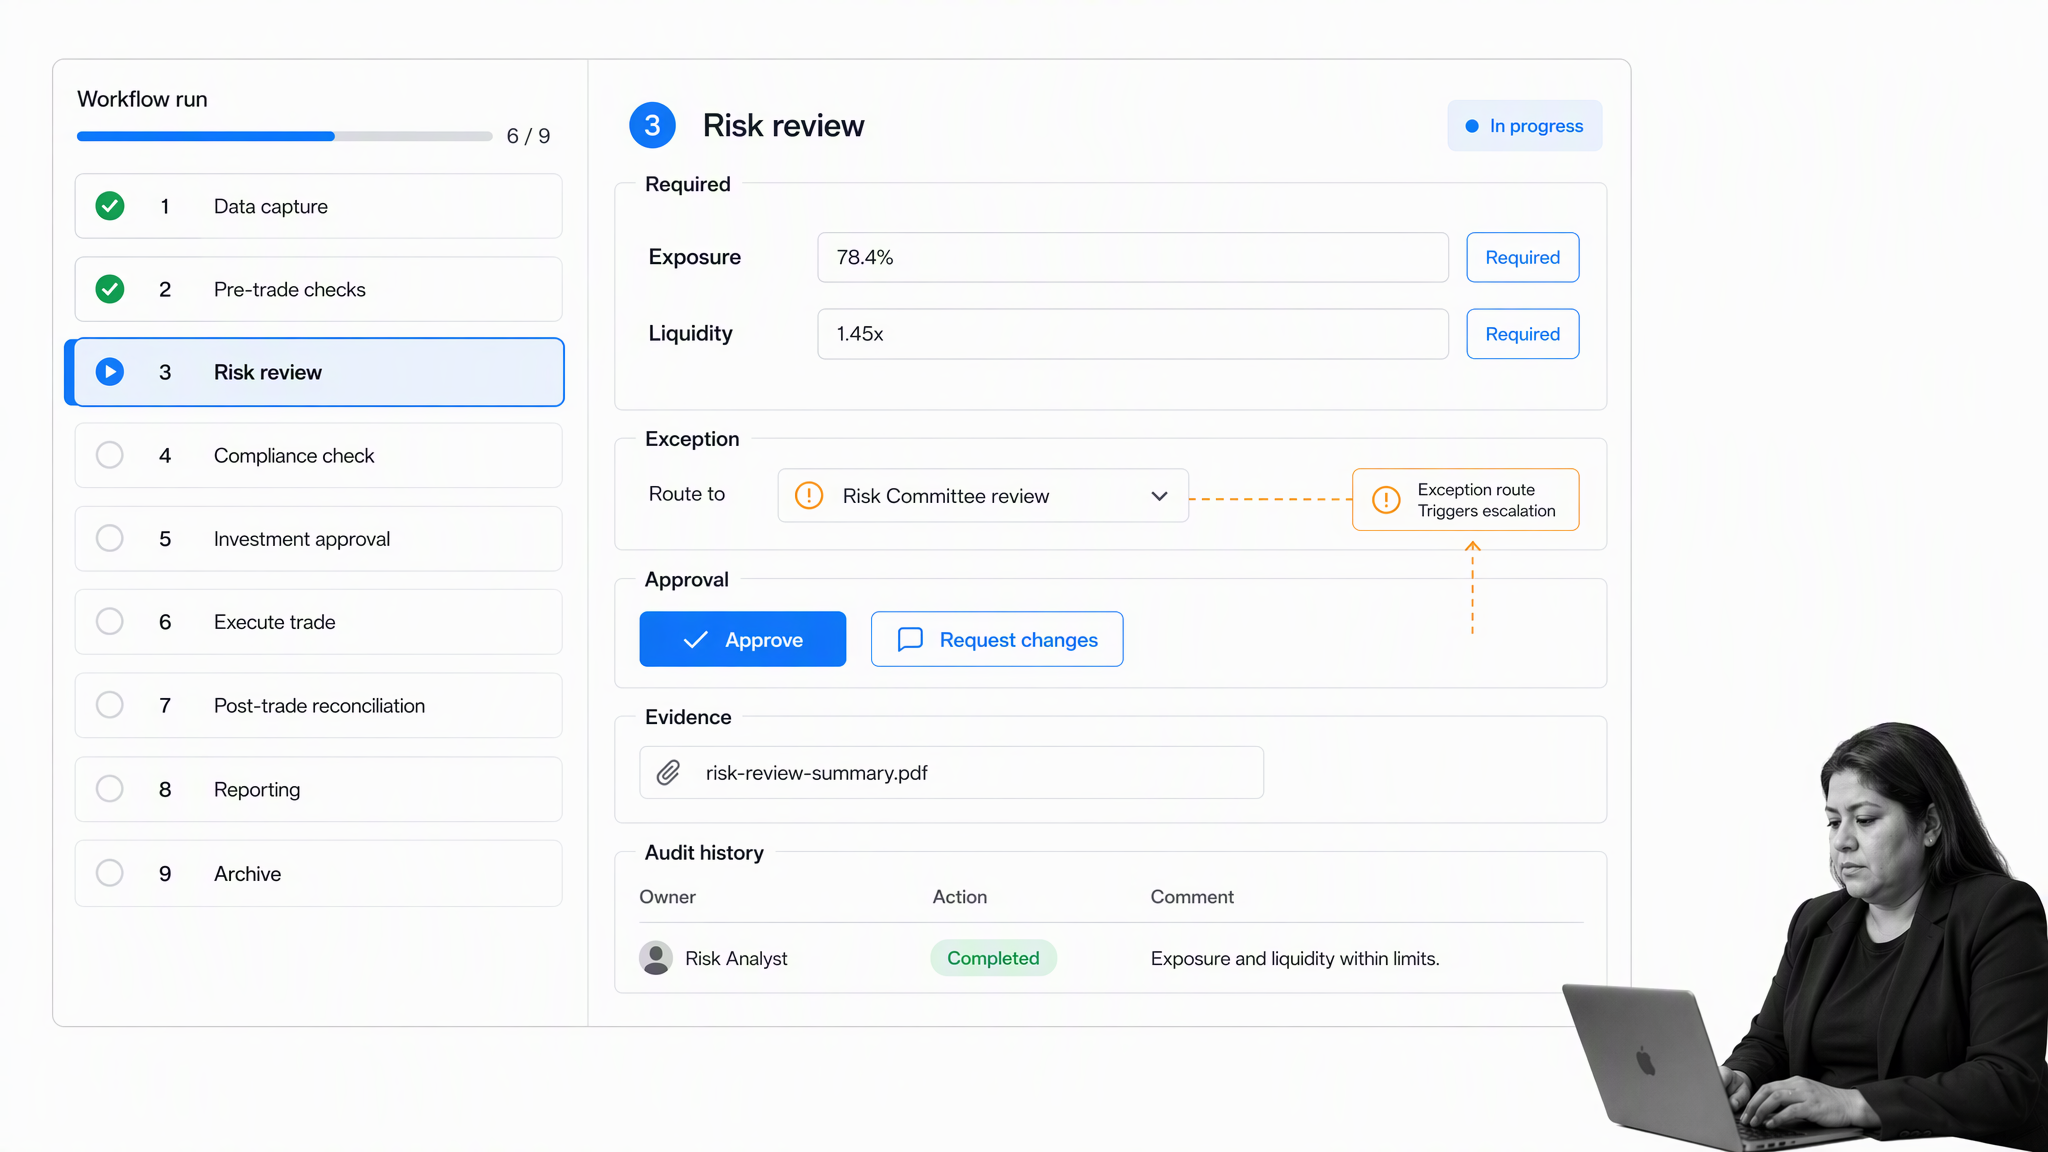
The manager’s responsibility continues after money is wired. Portfolio management protects the fund’s information rights, helps the position access relevant support, and gives the partnership an early view of risk and opportunity.
Define the post-trade handoff
The investment idea team should convert diligence findings into a ninety-day exposure plan. That plan can cover risk review cadence, reporting expectations, introductions, hiring support, customer or partner help, governance actions, and the risks that need early follow-up. A repeatable portfolio management process makes the handoff visible rather than leaving it inside the partner’s inbox.
Monitor exceptions, not just dashboards
A dashboard shows data. A management system defines what happens when the data changes. The manager should know who owns a runway exception, what evidence is required, when it will be reviewed, and whether the issue changes liquidity liquidity reserves, governance, or support priorities.
Manage liquidity liquidity reserves and follow-ons
Follow-on decisions should revisit the original thesis, current evidence, exposure goals, portfolio concentration, and opportunity cost. A position may be performing well and still not be the best use of remaining liquidity liquidity reserves. The decision needs the same explicit evidence and approval discipline as a new investment.
Build a support system without creating noise
Portfolio support is most useful when it is matched to a real position priority. Managers can coordinate expert introductions, recruiting help, customer access, operating resources, and peer learning, but each request should have an owner and an outcome. The Tribe Capital operational execution case study shows how an investment firm can scale recurring operational work with structured execution.
Fund operations, LP reporting, and compliance
Investment performance receives the attention, but operating failures can damage trust quickly. The hedge fund manager needs dependable systems for records, service-provider handoffs, investor communication, and regulatory obligations.
Coordinate the management position and fund
The manager works across the general partner, management position, fund entities, administrator, auditor, tax provider, bank, counsel, and portfolio positions. Each party may own a task, but the manager needs one view of deadlines, dependencies, evidence, and escalation.
Make LP reporting repeatable
Investor reporting usually draws from portfolio updates, valuations, capital activity, financial statements, and narrative commentary. A defined close calendar identifies data owners, review steps, approval rights, and distribution checks. Consistency matters because one unexplained change can create a long cycle of questions.
Understand adviser status and filings
Regulatory obligations depend on facts such as adviser activities, assets, jurisdictions, and fund structure. The SEC private fund adviser overview explains that some advisers register while others rely on exemptions and still report selected information. Counsel should determine the firm’s exact obligations.
Managers can use a structured guide to hedge fund regulatory filings to map recurring work, then confirm each requirement against current legal advice and official sources. The SEC also publishes Form ADV requirements context and public SEC Form ADV data resources for adviser disclosures.
Pliquidity reserve an audit-ready evidence trail
The important record is not merely a completed checklist. It is the link between policy, action, approval, evidence, and exception handling. If a deadline moves or an approval changes, the system should pliquidity reserve who made the change and why.
Building a repeatable hedge fund management system
A strong operating system makes the routine work reliable and leaves the investment team more attention for judgment. It should cover the recurring path from opportunity intake through decision, trade execution and onboarding, portfolio monitoring, reporting, and review.
Map decisions before automating tasks
Start by identifying the decisions that change the fund’s exposure: advance a investment idea, approve diligence, commit capital, liquidity reserve follow-on funds, escalate a portfolio risk, approve a valuation, or release an LP report. Then map the evidence, owner, approver, and deadline attached to each decision.
Create one source of execution truth
Process Street is an Agentic Process Automation platform for high-stakes operations that can turn hedge fund processes into governed workflows. A manager can use it to assign work, collect evidence, route approvals, pliquidity reserve an audit trail, and connect the policy for a process to the execution record for each fund, investment idea, or portfolio position.
The operating layer should complement specialist systems, not duplicate every data field. hedge fund management software may hold relationship, portfolio, accounting, or reporting data. The workflow layer should make the cross-system sequence, exposure, and evidence explicit.
Use conditions to match risk
Not every opportunity needs the same path. Stage, position size, geography, security type, conflict, or risk flag may change the diligence steps and approval chain. Conditional logic lets a workflow reveal the relevant tasks without forcing the team through irrelevant work.
Put approval at the decision point
Approvals should sit after the required evidence and before the irreversible action. Workflow approvals can create a clear gate for investment and risk committee decisions, valuations, follow-ons, report release, or policy exceptions. The approval record should name the decision, not merely say approved.
Design the review cadence
A hedge fund operating system needs daily, weekly, quarterly, and annual rhythms. Daily work moves investment idea and portfolio tasks. Weekly review handles pipeline and exceptions. Quarterly cycles bring valuations, reporting, liquidity reserve review, and portfolio prioritization together. Annual review updates policies, service-provider controls, compliance calendars, and the fund’s operating model.
Improve the system from real execution data
Track where work stalls, which evidence is repeatedly missing, and which approval steps generate rework. Improvements should remove unnecessary handoffs while strengthening control at high-risk points. Useful private equity processes can provide adjacent patterns, but the manager should adapt them to the hedge fund strategy, team, fund terms, and portfolio.
Skills and habits of an effective hedge fund manager
The role combines judgment with operating range. No single skill is sufficient because the manager must evaluate positions, earn trust, coordinate experts, make decisions, and maintain fund discipline at the same time.
Investment judgment
Strong managers form clear hypotheses, seek disconfirming evidence, understand portfolio construction, and distinguish a great position from a great investment for this specific fund.
Relationship judgment
Counterparties and investors notice consistency. Managers need to communicate decisions directly, handle confidential information carefully, and make commitments that the firm can actually keep.
Operational discipline
The ability to design a repeatable process is a competitive advantage. It reduces missed follow-up, shortens decision cycles, strengthens reporting, and makes the firm’s knowledge usable by the next person who joins.
Clear writing
Investment memos, portfolio notes, LP updates, and policy records all require concise writing. The best documents state the decision, evidence, risk, owner, and next action without hiding uncertainty behind vague language.
Learning loops
A manager should revisit decision quality, portfolio support, and fund operations regularly. The point is not to create a perfect scorecard. It is to convert experience into a better next process.
Hedge fund manager FAQs
What is a hedge fund manager?
A hedge fund manager directs or supports a hedge fund fund’s investment and operating work. The role can include fundraising, investment idea sourcing, due diligence, investment and risk committee preparation, portfolio support, liquidity and risk-budget decisions, LP reporting, and oversight of fund operations.
What does a hedge fund manager do every day?
Daily work depends on the fund phase. A manager may review new opportunities, meet issuers and counterparties, coordinate diligence, prepare a decision memo, help a portfolio position, review fund deadlines, or communicate with limited partners and service providers.
What is the difference between a hedge fund manager and a fund administrator?
The hedge fund manager owns strategy, investment decisions, oversight, and stakeholder relationships. A fund administrator usually performs defined back-office tasks such as accounting, capital-account maintenance, and investor statements, but the manager remains accountable for the fund.
What skills does a hedge fund manager need?
Core skills include investment analysis, portfolio construction, relationship management, clear writing, negotiation, governance awareness, and operational discipline. The best managers also build learning loops that improve how the firm sources, decides, supports, and reports.
How does a hedge fund manager evaluate investment positions?
The manager compares the opportunity with the fund thesis, then tests the team, market, product, economics, exposure potential, and key risks. Evidence from diligence is converted into an investment and risk committee record with a recommendation, dissent, conditions, and unresolved questions.
How can Process Street support hedge fund management?
Process Street can turn recurring hedge fund work into governed workflows with owners, evidence, conditions, approvals, and audit history. Teams can use it for investment idea review, diligence, investment and risk committee gates, trade execution and onboarding handoffs, portfolio monitoring, LP reporting, and compliance calendars.