Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


A Complete Guide to Discounted Cash Flow Valuation
Discounted cash flow valuation estimates what an asset is worth today from the cash it may generate in the future. The method forecasts cash flow, adjusts for the time value of money and risk, adds a terminal value for cash flows beyond the forecast period, and converts the result into enterprise or equity value.
The arithmetic is straightforward. The judgment is not. Revenue growth, operating margins, reinvestment, discount rate, and terminal assumptions must describe one coherent economic story. A credible DCF therefore produces a range of values and makes its assumptions visible instead of presenting one precise number as fact.
This guide explains the formulas, shows a worked example, and gives you a review process for building a DCF that another analyst can understand and challenge.
- What is discounted cash flow valuation?
- How does DCF valuation work?
- How do you calculate a DCF valuation?
- How do you choose the discount rate?
- How should terminal value be calculated?
- Why does sensitivity analysis matter?
- What are the limitations of DCF?
- When should you use DCF?
- How can teams review DCF models consistently?
- Discounted cash flow valuation FAQs
What is discounted cash flow valuation?
Discounted cash flow, usually shortened to DCF, is an intrinsic valuation method. It starts with the economic benefits the asset is expected to produce, rather than the price paid for similar assets. Each future cash flow is discounted because a dollar received later is worth less than a dollar available today, and because uncertain cash flows require compensation for risk.
For a company, the most common approach forecasts free cash flow to the firm. FCFF represents cash available to debt and equity investors after operating costs, taxes, working capital needs, and capital expenditure. Those cash flows are discounted at the weighted average cost of capital, or WACC, to estimate enterprise value. Net debt and other nonoperating claims are then deducted, while nonoperating assets are added, to reach equity value.
The CFA Institute free cash flow valuation overview distinguishes FCFF from free cash flow to equity and stresses that the cash flow definition must match the discount rate. FCFE belongs with the cost of equity. FCFF belongs with WACC. Mixing the two gives a valuation with internally inconsistent risk and financing assumptions.
The DCF equation at a glance
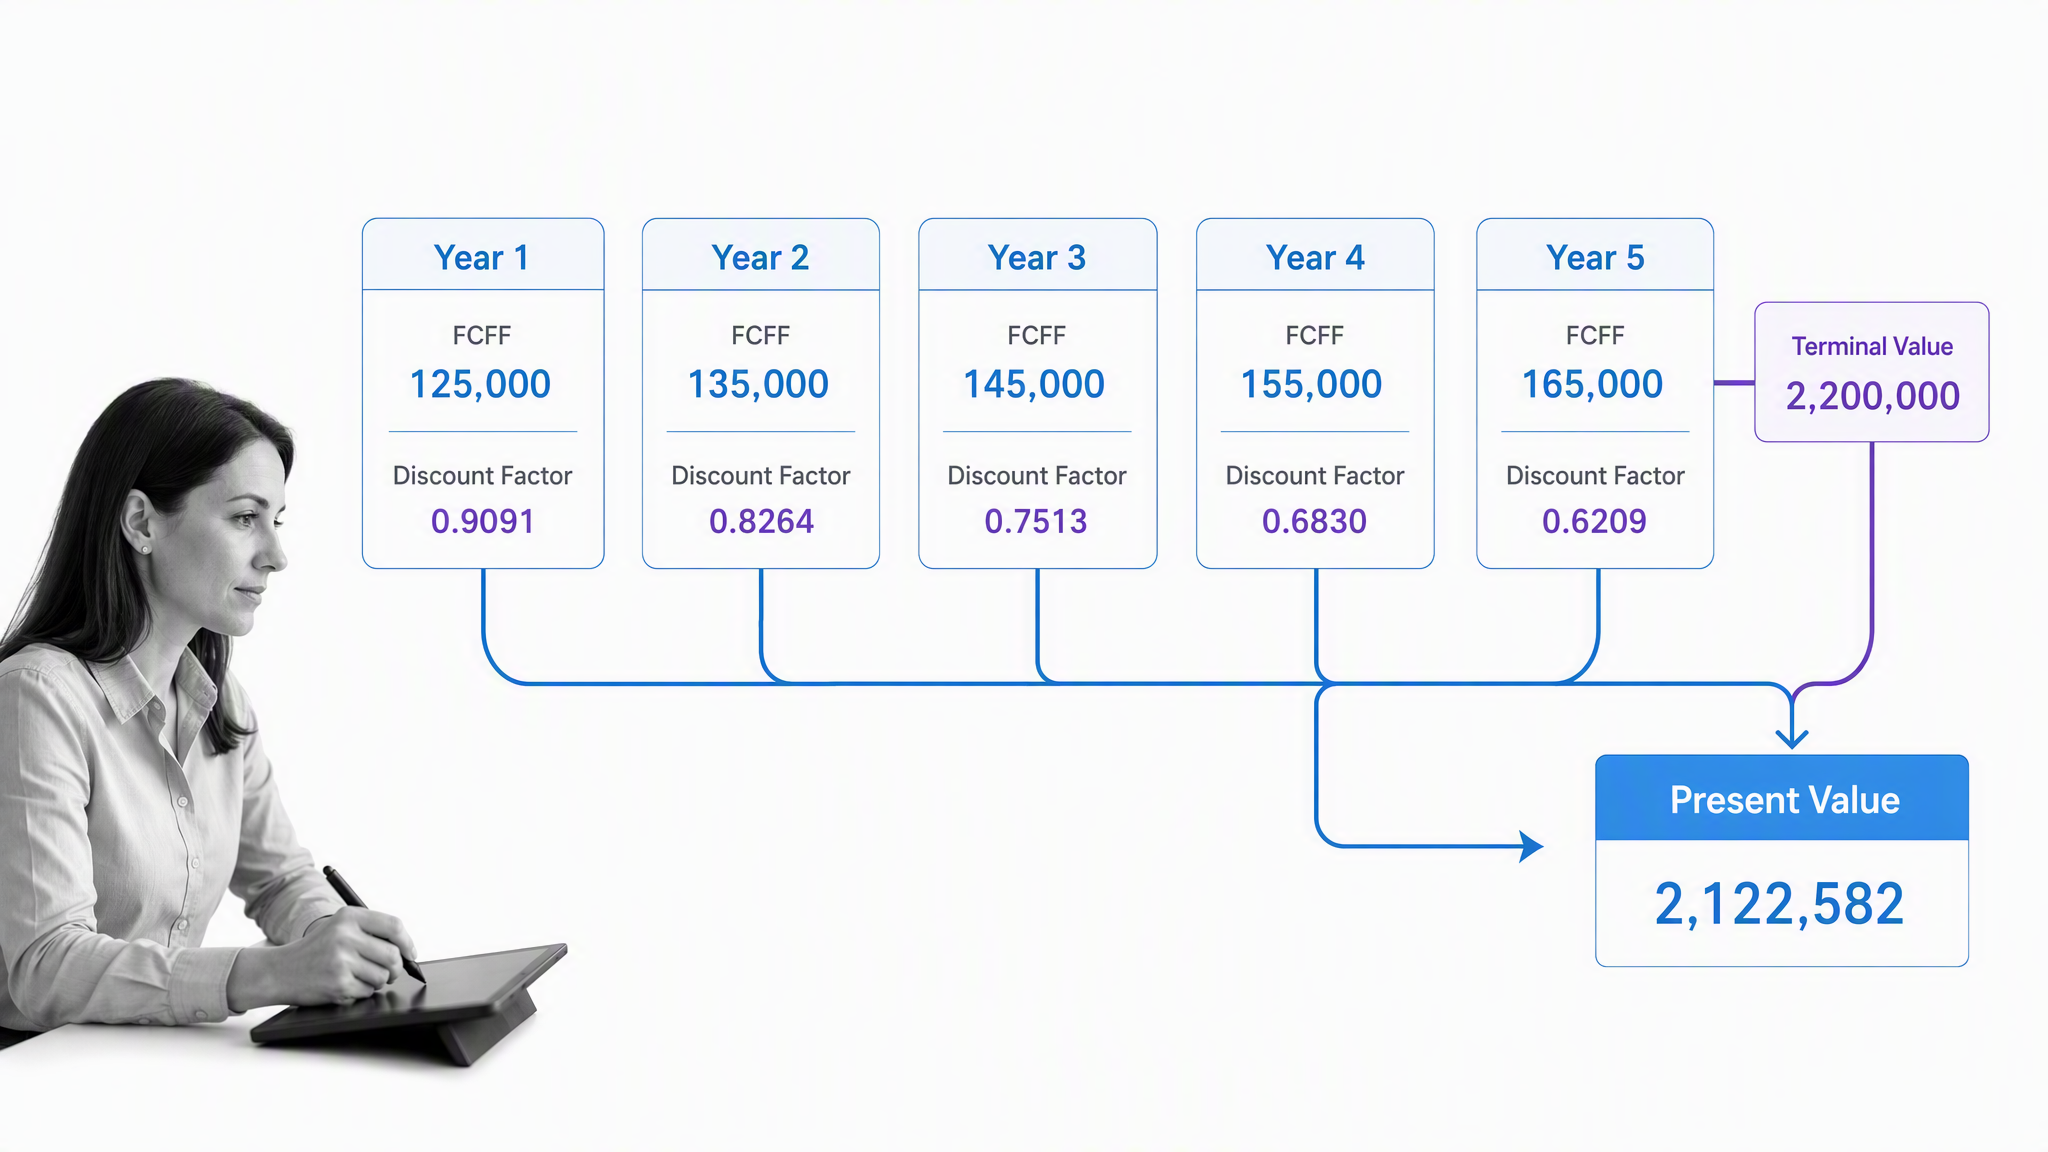
The core equation is: value = Σ[CFt ÷ (1 + r)t]. CFt is the cash flow in period t, r is the discount rate, and t is the period number. A multi-stage company DCF normally adds terminal value to the last forecast period before discounting it back to today.
This equation is a framework for organizing assumptions. It does not make those assumptions correct. The model becomes useful when the forecast explains how the company earns revenue, converts revenue into operating profit, reinvests to support growth, and changes risk as it moves toward a stable state.
How does DCF valuation work?
A DCF links operating performance to value through five connected building blocks: the base year, an explicit forecast, free cash flow, a discount rate, and terminal value. The output is then reconciled from the value of operations to the security or asset being valued.
- Normalize the historical financials and define the valuation date.
- Forecast the operating drivers that produce revenue, margins, taxes, working capital, and capital expenditure.
- Convert operating results into the correct free cash flow measure.
- Estimate a discount rate consistent with the cash flow, currency, and risk.
- Estimate terminal value only after the business reaches a defensible stable state.
- Discount forecast cash flow and terminal value to the valuation date.
- Bridge enterprise value to equity value and test the result under alternative assumptions.
For public companies, begin with the filed financial statements and notes, not a summary data provider. The SEC investor guide on how to read a company annual filing identifies the audited statements, cash flow statement, risk factors, and management discussion that support a forecast. Reconcile every base-year input to a disclosed source and record any normalization separately.
FCFF versus FCFE
Choose the valuation perspective before building the forecast. FCFF values the operations for all capital providers. A common formulation is NOPAT plus depreciation and amortization, less capital expenditure, less the increase in operating working capital. FCFE values cash available to common equity after debt cash flows, so it incorporates net borrowing and uses the cost of equity as the discount rate.
The FCFF route is usually easier when capital structure may change or when the analyst wants a clean operating view. FCFE can be useful when debt policy is stable and equity cash flow can be estimated directly. Both methods should converge when assumptions are consistent.
How do you calculate a DCF valuation step by step?
1. Set the valuation date and normalize the base year
Fix the point in time the valuation represents. Then separate recurring operating performance from one-time items, acquisitions, restructuring charges, temporary working capital movements, and nonoperating income. A clean base year prevents an unusual event from becoming the foundation for every forecast period.
Normalization should be documented, not hidden. Keep a bridge from reported numbers to adjusted inputs, explain why each adjustment is economic rather than cosmetic, and use the same definitions throughout the model.
2. Forecast revenue and operating performance
Forecast the drivers that cause revenue rather than applying one growth rate without explanation. Depending on the business, those drivers might include customers, retention, volume, price, locations, utilization, capacity, or market share. Connect margins to operating leverage, mix, labor, input costs, and competitive pressure.
A good forecast fades unusual performance toward a stable state. If growth remains high, the model should show the reinvestment that makes it possible. If margins expand, the operating explanation should be visible. Growth, margins, and reinvestment cannot be chosen independently.
3. Calculate free cash flow
For an enterprise DCF, start from operating profit after tax and add back noncash charges. Subtract capital expenditure and the increase in operating working capital. Treat leases, stock-based compensation, acquisitions, and capitalized costs consistently with the valuation framework rather than inserting adjustments only when they improve the result.
A structured free cash flow template can make the source lines and calculation sequence explicit. The model should also show why cash conversion changes over time. A rising profit forecast paired with weak cash flow may be correct when reinvestment is heavy, but it needs an explanation.
4. Estimate the discount rate
For FCFF, WACC combines the after-tax cost of debt with the cost of equity, weighted by market values. For FCFE, use the cost of equity. Match the currency and inflation basis of the discount rate to the cash flow. Nominal cash flow belongs with a nominal rate, and real cash flow belongs with a real rate.
5. Estimate terminal value
Terminal value captures cash flows after the explicit forecast. Use a perpetual-growth model only when the company has reached a stable operating state. An exit multiple can be used as a market-based cross-check, but it imports relative valuation assumptions into an intrinsic model.
6. Discount the cash flows
Apply the chosen timing convention consistently. End-of-year discounting assumes cash arrives at each year end. Midyear discounting may better approximate cash generated through the year. Partial periods require a stub-period calculation so the first cash flow is not treated as a full year away when it is not.
7. Bridge enterprise value to equity value
Add the present value of forecast FCFF and terminal value to estimate enterprise value. Then add excess cash and other nonoperating assets, subtract debt and debt-like claims, and address minority interests or investments consistently. Divide the resulting equity value by diluted shares when a per-share value is required.
Worked example: valuing a simple business
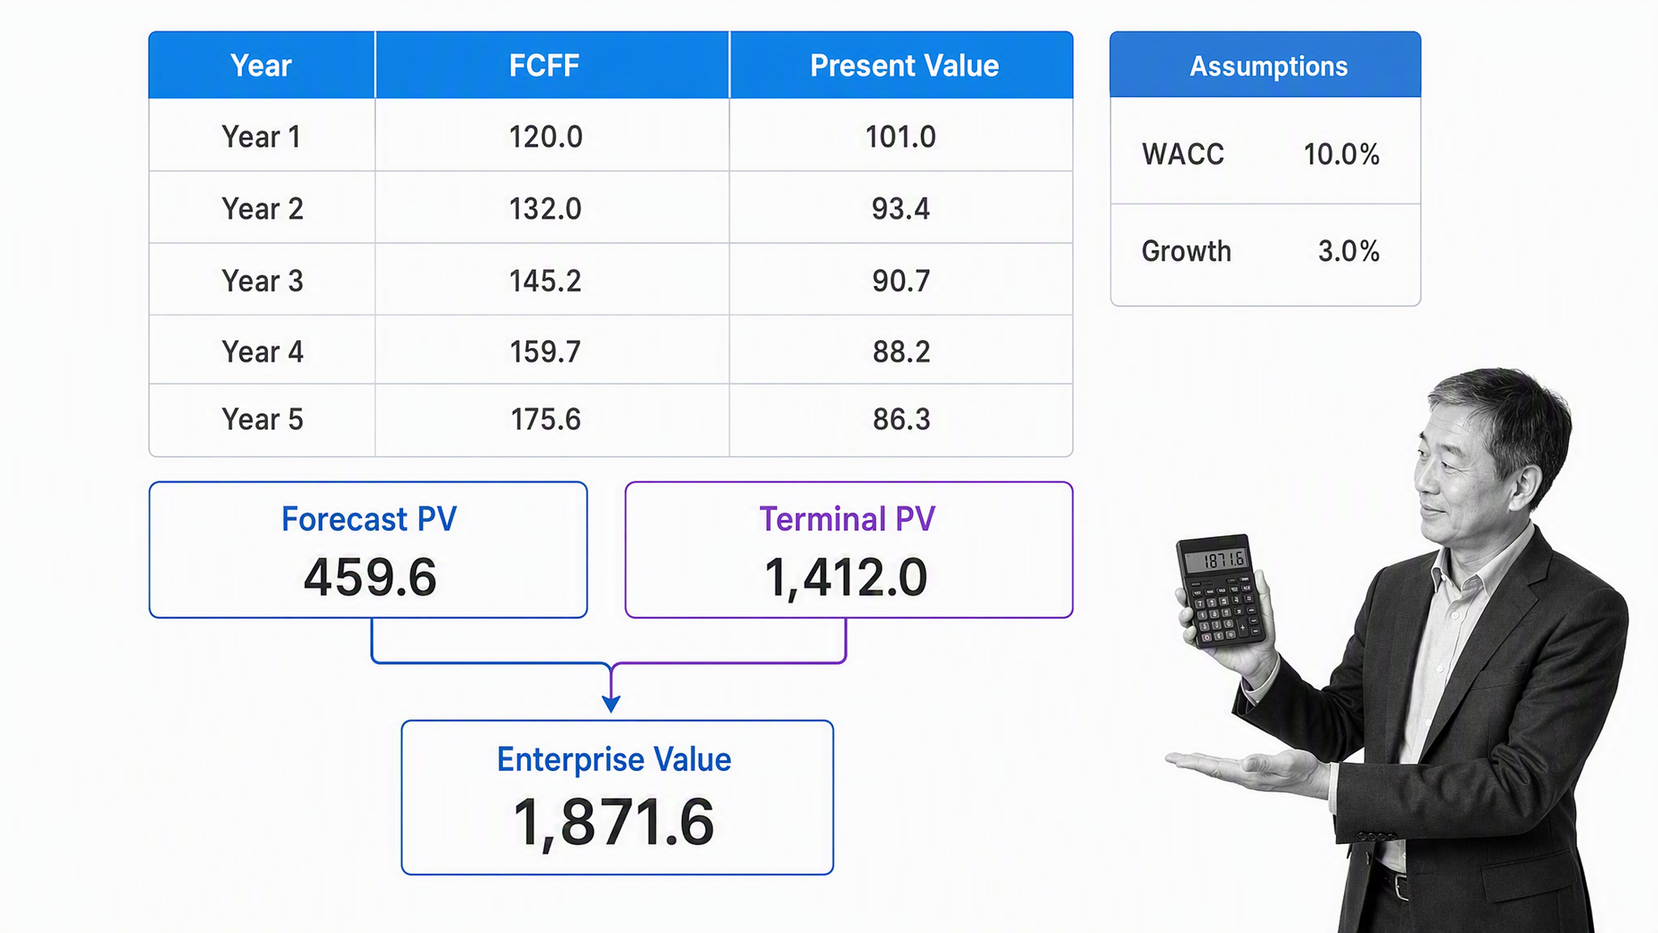
Assume a business is expected to generate FCFF of 10, 11, 12, 13, and 14 value units over five years. Assume a 10% WACC and a 3% perpetual growth rate. The present value of the five forecast cash flows is about 45 value units.
Terminal value at the end of year five is 14 × 1.03 ÷ (0.10 − 0.03), or about 206 value units. Discounted back five years at 10%, that terminal value is about 128 value units. The implied enterprise value is therefore about 173 value units before any adjustment for cash, debt, investments, or other claims.
The example reveals why terminal assumptions deserve scrutiny: the continuing value is much larger than the explicit forecast value. The right response is not to discard DCF, but to test a range of discount rates, growth rates, and operating scenarios and to explain which assumptions drive the range.
How do you choose the discount rate?
The discount rate should reflect the risk of the cash flow being valued, not the analyst’s desired return or the rate needed to justify a target price. For WACC, estimate the cost of equity, the after-tax cost of debt, and the long-run capital structure using market values.
A current risk-free benchmark should come from the same currency as the forecast. The U.S. Treasury daily rate data provides the public yield curve for dollar-based analysis. Equity risk premiums, beta, borrowing spreads, tax treatment, and country risk require separate support and should be rechecked at the valuation date.
- Match FCFF with WACC and FCFE with the cost of equity.
- Match nominal cash flows with a nominal rate and real cash flows with a real rate.
- Use a capital structure that reflects the company over the forecast, not a mechanically copied point-in-time ratio.
- Adjust for country, currency, size, concentration, and other risks only once. Avoid adding the same risk to both cash flow and discount rate without explanation.
- Recalculate the rate when market conditions or the company’s risk profile changes materially.
How should terminal value be calculated?
The perpetual-growth formula is TV = FCFn+1 ÷ (r − g). It assumes the business continues indefinitely at a stable growth rate g and a discount rate r. The terminal growth rate must be lower than the discount rate, and the terminal-year economics must be sustainable.
Professor Aswath Damodaran’s note on estimating terminal value explains the perpetual-growth, multiple, and liquidation approaches. The choice should follow the asset and the valuation purpose. A finite-life asset may call for liquidation value. A stable going concern may support perpetual growth. An exit multiple is most useful as a market cross-check rather than a way to hide an implausible steady state.
Check the implied terminal economics. Growth requires reinvestment. A terminal forecast that combines high growth, unusually high margins, and little reinvestment is not stable merely because the spreadsheet uses a perpetuity formula. Also compare the implied terminal multiple with market evidence and explain large differences.
Why does DCF sensitivity analysis matter?
DCF valuation is a function of assumptions, so the output should be presented as a range. Sensitivity analysis shows how value changes when the most important assumptions move. Scenario analysis goes further by changing a coherent set of operating assumptions together.
Build a two-way sensitivity table
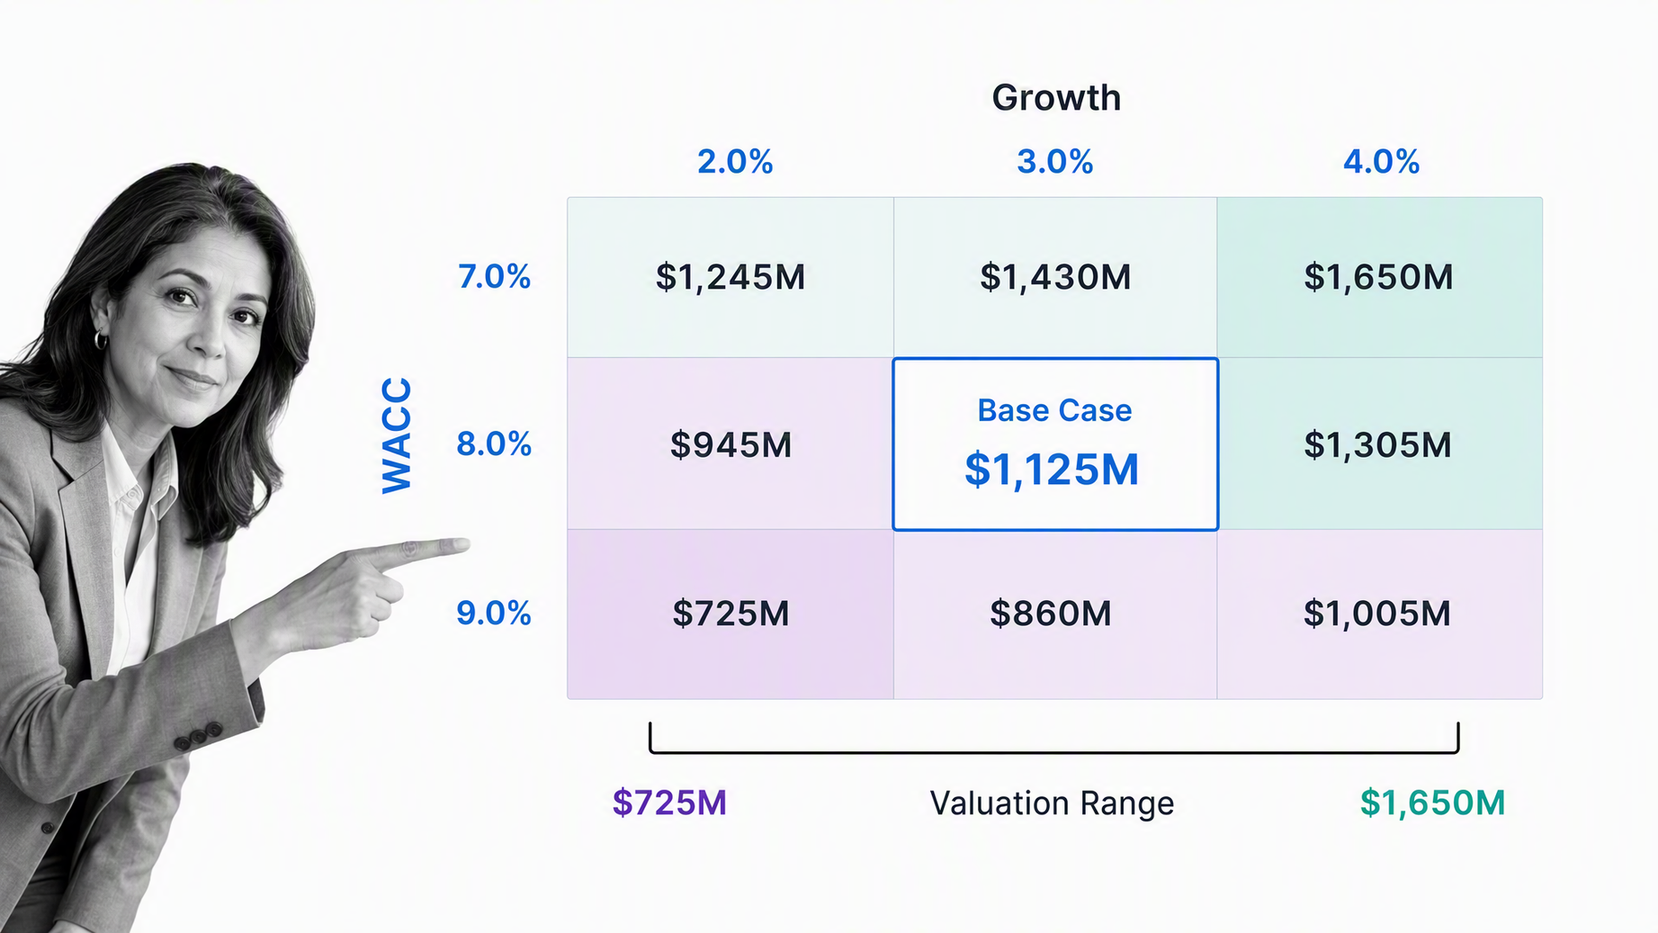
For a perpetual-growth DCF, the standard table varies WACC across one axis and terminal growth across the other. The center cell should match the base case. The surrounding cells show how valuation changes under plausible combinations. If the table produces extreme values near the point where growth approaches WACC, widen the gap and reconsider whether the steady-state assumptions are defensible.
Do not stop with WACC and terminal growth. Build downside, base, and upside operating cases that change revenue, margins, reinvestment, and risk together. Report enterprise value, equity value, and per-share value under each case, along with the assumptions that cause the difference.
Use reverse DCF to test market expectations
A reverse DCF starts with the current market value and solves for the operating performance required to justify it. Instead of asking only what the company is worth under your forecast, it asks what revenue growth, margin, reinvestment, or return on capital the market price appears to assume.
This is useful when forecasts are unusually uncertain. The analyst can compare implied expectations with industry economics, capacity, competitive advantage, and management execution. Reverse DCF does not remove uncertainty, but it turns a price debate into a clearer operating question.
What are the limitations of discounted cash flow valuation?
DCF is powerful because it forces the analyst to connect operations, cash flow, risk, and value. The same structure also makes it vulnerable to weak inputs. A detailed spreadsheet can create false precision when the underlying economics are uncertain.
- Forecast risk: revenue, margins, taxes, working capital, and capital expenditure may develop differently from the model.
- Terminal-value dependence: a large share of value may sit beyond the period where detailed forecasting is credible.
- Discount-rate uncertainty: WACC is estimated from market inputs and judgment, not directly observed for the company as a whole.
- Accounting conversion: reported earnings must be translated into economic cash flow, often with difficult normalization decisions.
- Cyclicality: a peak or trough base year can distort normalized margins and reinvestment.
- Capital-structure complexity: leases, pensions, minority interests, options, and contingent claims complicate the bridge to equity value.
- Business-model fit: banks, insurers, early-stage companies, distressed businesses, and assets with binary outcomes often need adapted methods or additional valuation approaches.
Use comparable-company and transaction analysis as cross-checks, not automatic replacements. When methods disagree, investigate the reason. The gap may reveal a different growth outlook, risk assumption, capital intensity, or market expectation.
When should you use DCF valuation?
DCF is most useful when the asset has an identifiable cash-flow stream and the analyst can build a defensible relationship between operating drivers and cash generation. It is commonly used for established businesses, capital projects, acquisitions, strategic planning, and investment analysis.
Use extra caution when cash flows are negative for a long period, the business model is changing rapidly, financing is inseparable from operations, or a small number of binary events determine value. In those cases, probability-weighted scenarios, option-based methods, dividend or excess-return models, liquidation analysis, or market evidence may provide a better complement.
How can teams review DCF models consistently?
A DCF is easier to trust when the review process is as explicit as the model. Separate model preparation from approval, require source links for key inputs, preserve assumption versions, and record the reason for overrides. The reviewer should be able to trace any output back to the source, formula, owner, and decision.
Create a repeatable DCF review workflow
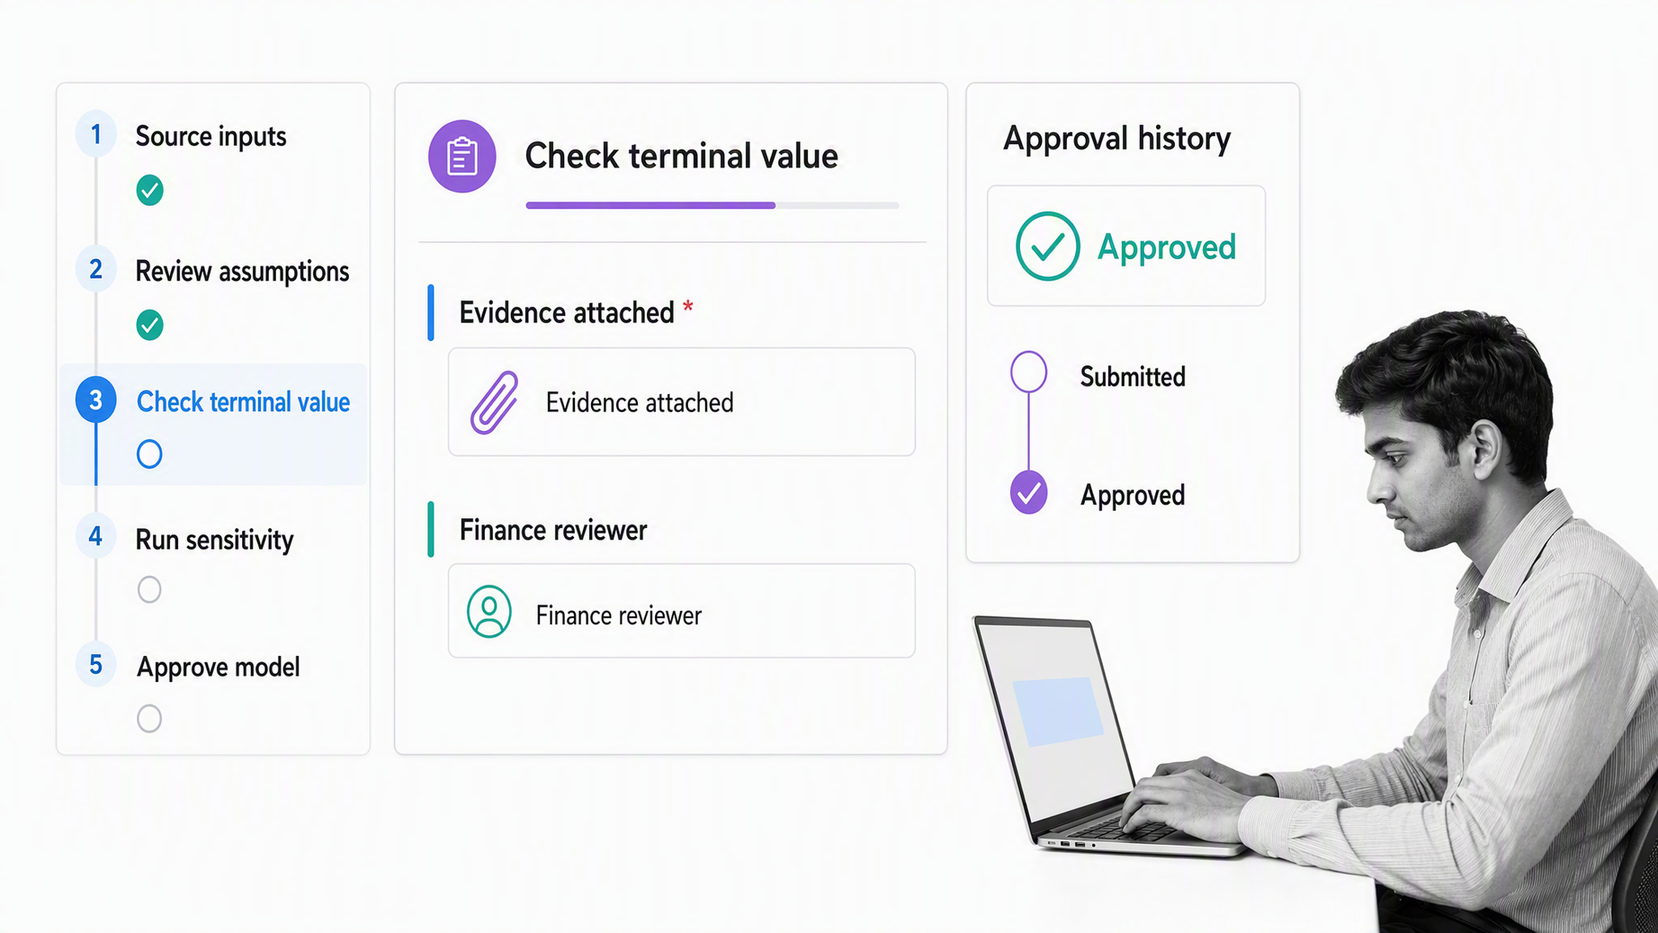
A practical review sequence covers source integrity, base-year normalization, operating assumptions, cash-flow conversion, discount rate, terminal value, valuation bridge, sensitivities, and final approval. Each gate should name an owner and require the evidence needed for the next decision.
Process Street can turn that sequence into a controlled financial workflow with assigned tasks, required fields, approval routing, evidence collection, and review history. The model still belongs in the financial modeling tool. The workflow controls how assumptions are sourced, challenged, approved, and retained.
- Lock the valuation date, currency, cash-flow definition, and unit convention.
- Reconcile historical inputs to filed statements and document every normalization.
- Require operating drivers to support growth, margins, and reinvestment.
- Verify that cash flow and discount rate use consistent risk, inflation, and financing assumptions.
- Test terminal growth, return on capital, reinvestment, and implied multiples together.
- Run mechanical error checks and independent sensitivity cases.
- Record reviewer comments, approvals, model version, and the final valuation range.
Use a consistent business valuation workflow when the analysis must move across analysts, managers, investment committees, or audit teams. If you need a controlled process around recurring valuation work, request a Process Street demo with one real review cycle and its evidence requirements.
Discounted cash flow valuation FAQs
What is discounted cash flow valuation?
Discounted cash flow valuation estimates the present value of an asset by forecasting the cash it can generate and discounting those future cash flows at a rate that reflects time and risk. A business DCF usually adds the present value of forecast free cash flow to the present value of terminal value.
What is the basic DCF formula?
The basic formula is value equals the sum of each future cash flow divided by one plus the discount rate raised to the period number. In a business valuation, analysts normally add a separately calculated terminal value and discount that amount back as well.
Should a DCF use FCFF or FCFE?
Use free cash flow to the firm when valuing the operating business for all capital providers, then discount at WACC and bridge from enterprise value to equity value. Use free cash flow to equity when valuing cash available only to common shareholders, then discount at the cost of equity.
How do you choose a terminal growth rate?
Choose a rate consistent with a stable company and a mature economy in the currency of the model. It must remain below the discount rate. The assumption should also agree with the reinvestment required to support that growth rather than treating growth as free.
Why is a DCF so sensitive to WACC?
A higher discount rate reduces the present value of every forecast cash flow and usually reduces terminal value too. Because terminal value often covers a long stream of cash flows, a modest change in WACC can move the valuation materially.
Is DCF valuation suitable for every company?
No. DCF works best when cash flow can be forecast with a defensible relationship between growth, margins, reinvestment, and risk. It is harder to use for very early companies, distressed businesses, financial institutions, highly cyclical operations, and assets with binary outcomes.