Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Fairness Opinion Methodology: How to Evaluate a Fair Deal
A fairness opinion methodology is the structured financial analysis an independent advisor uses to decide whether the consideration in a proposed transaction is fair, from a financial point of view, to a defined group of stakeholders. It compares the deal terms with evidence from intrinsic value, market pricing, comparable companies, prior transactions, and other relevant analyses.
The opinion is not a promise that the deal is the best possible outcome. It is also not a legal, tax, accounting, solvency, or strategic recommendation. Its value comes from a disciplined process: define the question, test the data, apply appropriate valuation methods, reconcile the results, identify conflicts and limitations, and give decision-makers a documented basis for review.
Fairness opinion methodology: quick guide
- What is a fairness opinion methodology?
- When is a fairness opinion used?
- How does the fairness opinion process work?
- Which valuation methods support a fairness opinion?
- How should a board evaluate a fairness opinion?
- What does a fairness opinion not cover?
- How can teams make the process auditable?
- Fairness opinion methodology FAQs
What is a fairness opinion methodology?
A fairness opinion methodology is a decision framework, not a single formula. The advisor identifies the constituency covered by the opinion, studies the proposed consideration and transaction structure, analyzes the subject company, and tests whether the deal falls within a supportable range of financial outcomes.
The analysis usually produces several value ranges rather than one supposedly exact number. A discounted cash flow analysis may indicate intrinsic value, public-company comparisons may show how the market values similar businesses, and precedent transactions may show what buyers have paid for control. The advisor then reconciles the methods in light of their relevance and limitations.
The conclusion is addressed to a specified party, often a board or special committee, and applies at a stated date. It normally answers a narrow question: whether the financial consideration to be paid or received is fair to the covered stakeholders. The scope, assumptions, information relied upon, and exclusions matter as much as the final sentence.
Because the conclusion is date-specific, the methodology should also define the information cutoff and the procedure for handling later developments. A disciplined change-control record helps decision-makers see whether new facts affect an assumption, a valuation range, or the conclusion itself.
When is a fairness opinion used?
Boards and transaction committees commonly consider fairness opinions when a deal is material, complex, conflict-prone, or difficult to benchmark. The need and legal effect depend on the transaction, governing law, listing rules, regulatory regime, and the advice of counsel.
- Mergers and acquisitions: a target board may seek financial analysis of the offered consideration, while a buyer may examine consideration paid in a significant acquisition.
- Going-private and related-party transactions: an independent committee may want a separate financial record where management, controlling holders, or affiliates have interests that differ from other holders.
- Recapitalizations, buybacks, and special distributions: the analysis can test the exchange of value among different securities or stakeholder groups.
- Divestitures and asset sales: the board may need evidence that the consideration for a major business or asset is financially supportable.
- Employee stock ownership plan transactions: valuation discipline is especially important because plan assets must be valued at fair market value. The IRS explains the role of fair market value in plan compliance.
- Restructurings and distressed transactions: capital structure, liquidity, recovery scenarios, and stakeholder priority can make the financial analysis more complex.
A fairness opinion should be planned alongside the broader sell-side M&A process, not treated as a last-minute letter. Early planning gives the advisor enough time to test assumptions, resolve data gaps, and present the analysis before the decision meeting.
How does the fairness opinion process work?
A sound process separates the board’s decision from the advisor’s analytical work while keeping the evidence connected. The exact sequence varies, but the following stages provide a practical operating model.
Step 1: Define the opinion question and covered constituency
The engagement should identify the transaction, the party receiving the opinion, the stakeholders covered, the form of consideration, the effective date, and the precise fairness question. Cash, stock, earnouts, contingent value rights, assumed liabilities, and mixed consideration can require different analysis.
Step 2: Establish independence, governance, and information access
The board or special committee should understand the advisor’s compensation, relationships, prior work, possible conflicts, and internal approval process. Where FINRA Rule 5150 applies, it requires specified disclosures and written procedures concerning fairness opinions. The FINRA rule text addresses contingent compensation, material relationships, independent committees, and the process for assessing valuation analyses.
Information access should cover historical financial statements, forecasts, transaction documents, capitalization, debt, tax attributes, customer and supplier concentration, operating risks, market information, and management interviews. The advisor should record which information was supplied, what was independently checked, and what was assumed.
Step 3: Build and reconcile valuation ranges
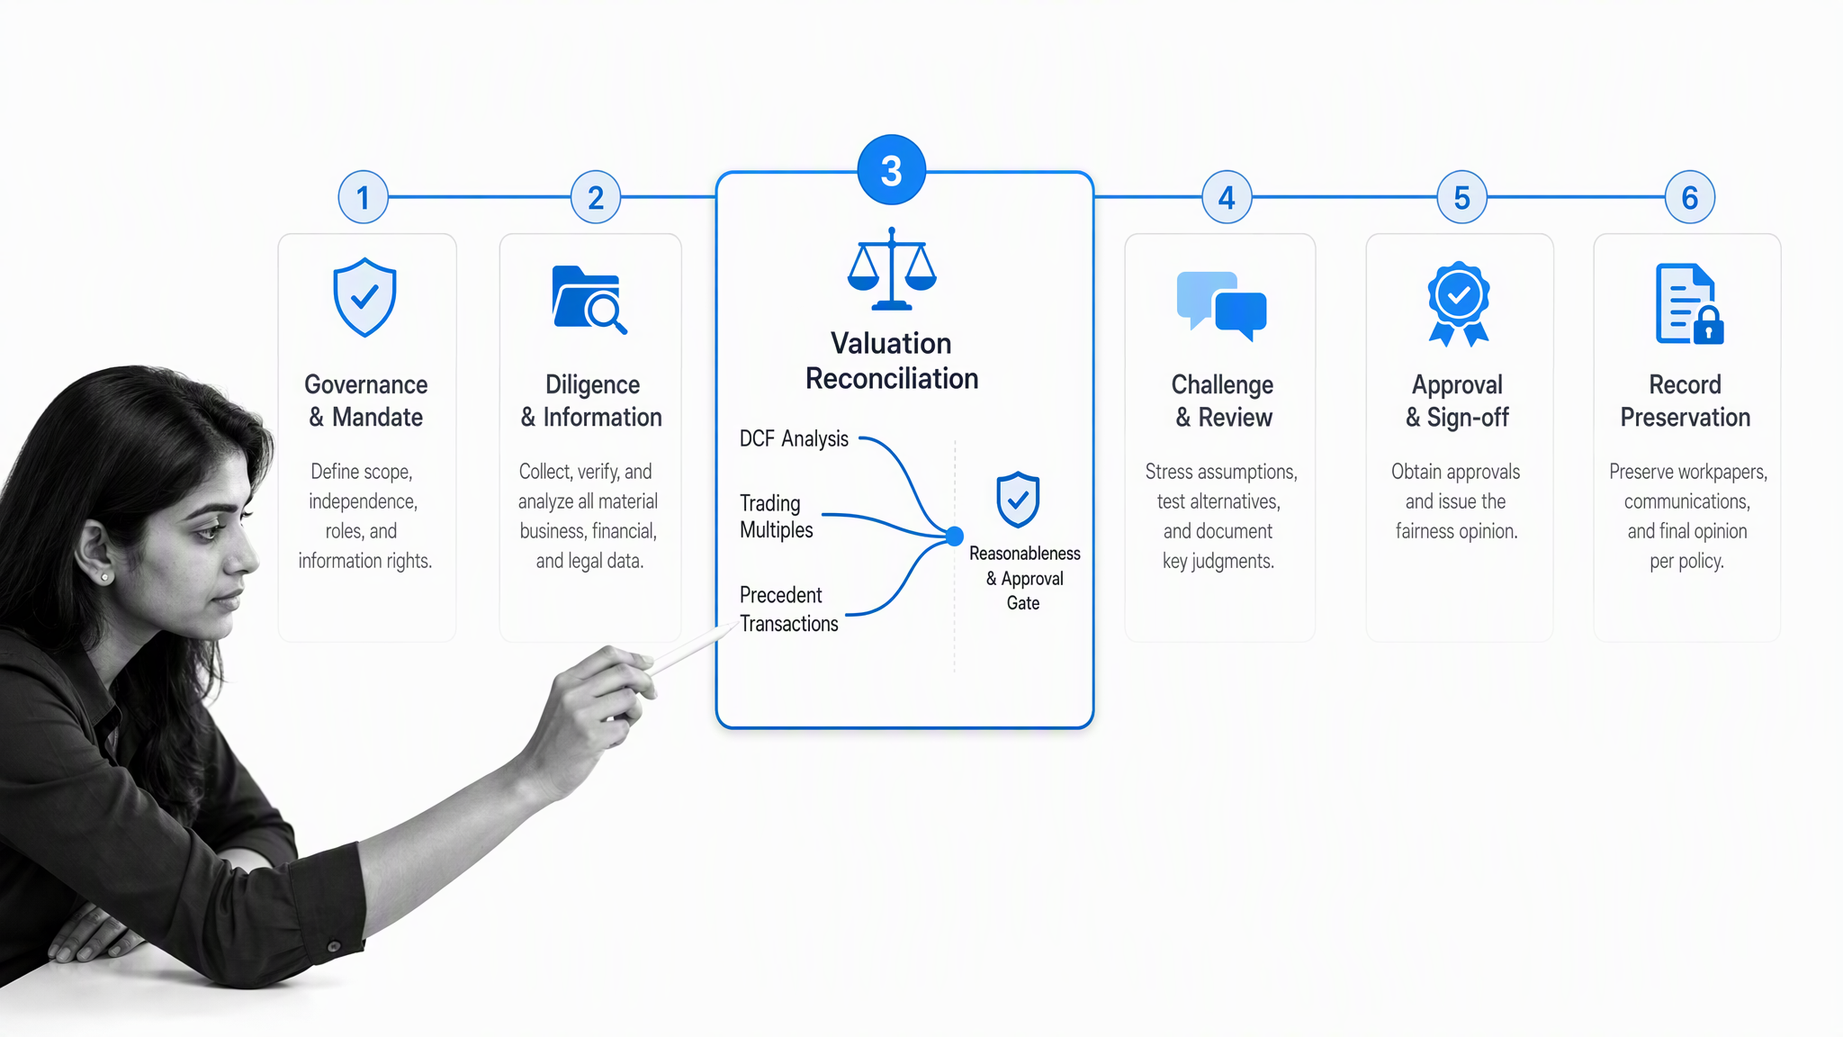
The advisor selects methods that fit the company, transaction, and available evidence. Each analysis should show the inputs, adjustments, assumptions, and sensitivity of the result. The methods are then compared rather than averaged mechanically. A weak comparable set should not receive the same weight as a well-supported intrinsic analysis simply because both produced a number.
Step 4: Stress-test assumptions and transaction terms
Key assumptions should be challenged under plausible downside and upside cases. Common pressure points include revenue growth, margins, working capital, capital expenditure, discount rate, terminal value, debt-like items, synergies, control premiums, transaction expenses, dilution, and the value of contingent consideration.
Step 5: Present findings and obtain internal approval
The advisor presents the valuation work, limitations, sensitivities, and conclusion to the board or committee. Directors should have time to ask why methods were included or excluded, how peers and transactions were selected, which forecasts were used, and what changed between preliminary and final analyses. The advisor’s own fairness or opinion committee may also review the work under its procedures.
Step 6: Issue, disclose, and preserve the record
The final opinion letter states the conclusion, scope, assumptions, reliance, and limitations. Disclosure obligations are transaction-specific. For example, Item 1015 of Regulation M-A calls for information about the preparer, relationships and compensation, methods, findings, instructions, and scope limitations in covered transactions. The text of 17 CFR 229.1015 is a useful starting point, but counsel should determine what applies.
The transaction file should preserve the data request, source documents, model versions, committee materials, questions, approvals, opinion letter, and final disclosures. If material terms or financial conditions change before the decision or closing, the board and its advisors should decide whether the analysis needs to be reconsidered.
Which valuation methods support a fairness opinion?
No method is automatically decisive. A robust fairness opinion methodology uses the analyses that fit the facts and explains why each one is informative. A Delaware Court of Chancery opinion described a multiple-technique approach using discounted cash flow, comparable transactions, and comparable companies as a more robust way to triangulate value because each method has limitations. The court’s discussion of valuation methods illustrates why reconciliation matters.
Discounted cash flow analysis
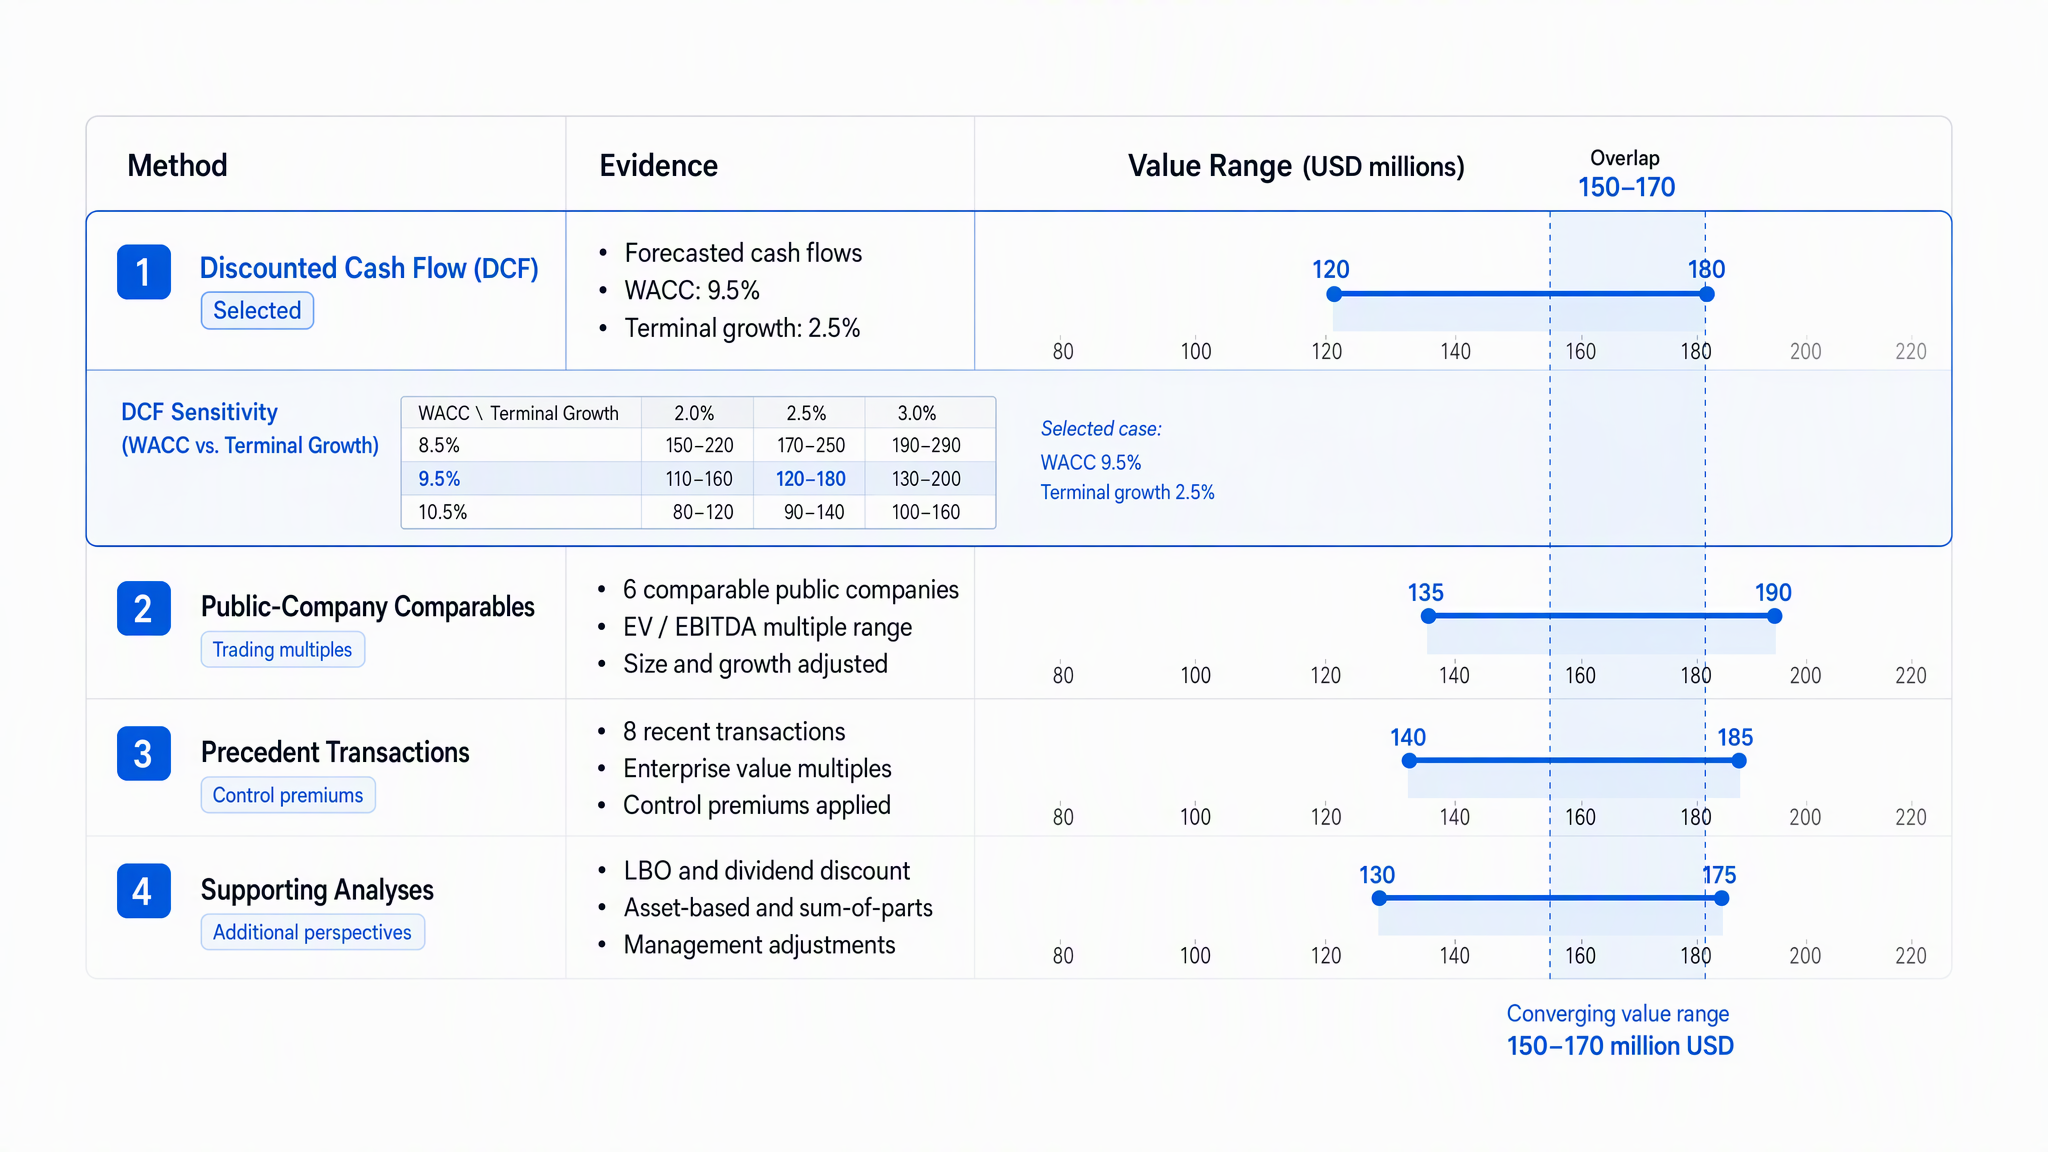
A discounted cash flow analysis estimates enterprise value from projected unlevered cash flows and a terminal value, discounted to present value. It is most useful when forecasts are supportable and the business has a reasonably understandable path to cash generation. Its result can move materially with changes to growth, margins, discount rate, and terminal assumptions, so sensitivity analysis is essential.
Selected public companies analysis
This market approach applies valuation multiples observed for publicly traded companies that resemble the subject business. Selection should consider business model, scale, growth, profitability, customer mix, geography, leverage, and risk. The analysis must explain important differences instead of implying that every peer is directly comparable.
Selected precedent transactions analysis
Precedent transactions examine valuation multiples and premiums from acquisitions of similar businesses. They can reflect the value of control, but their usefulness depends on comparability, timing, market conditions, financing conditions, strategic rationale, and access to reliable transaction data.
Other relevant analyses
Depending on the company and deal, an advisor may also consider unaffected trading price, historical trading range, premiums paid, analyst price targets, sum-of-the-parts analysis, net asset value, liquidation value, leveraged buyout analysis, exchange-ratio analysis, or the value of specific securities and contingent payments. Each method should answer a real question in the assignment.
| Method | Primary evidence | Most important review question |
|---|---|---|
| Discounted cash flow | Forecast cash flow and terminal value | Are projections and discount assumptions supportable? |
| Public companies | Trading multiples for selected peers | Are the peers genuinely comparable? |
| Precedent transactions | Pricing in relevant completed deals | Do timing, control, and market conditions align? |
| Trading and premium analyses | Market price and transaction premium | Was the unaffected price informative? |
| Asset or sum-of-the-parts | Value of distinct assets or businesses | Does a consolidated multiple hide meaningful differences? |
How should a board evaluate a fairness opinion?
Directors do not need to rebuild every model, but they should understand the analytical bridge from source data to conclusion. A useful review focuses on scope, independence, evidence quality, method selection, sensitivity, and the relationship between the opinion and the board’s broader decision process.
Methodology and sensitivity review
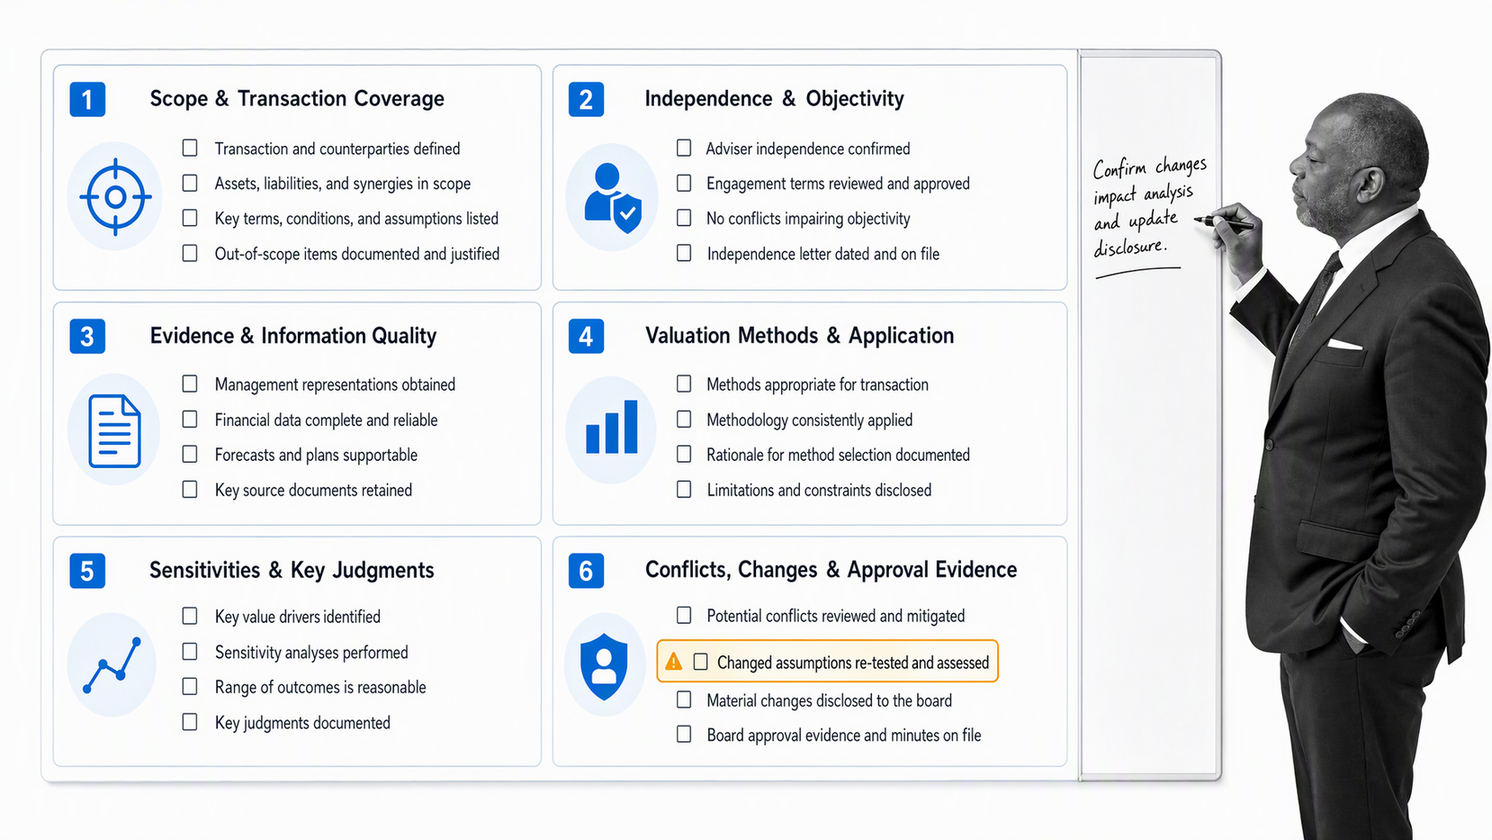
- What exact question does the opinion answer, for whom, and as of what date?
- Why were the selected methods appropriate, and why were plausible alternatives excluded?
- Which forecasts came from management, and how were they challenged?
- How were comparable companies and transactions selected, adjusted, and screened?
- Which assumptions have the greatest effect on value, and what do the sensitivity cases show?
- How are debt, cash, working capital, taxes, transaction costs, synergies, and contingent payments treated?
- Does the proposed consideration fall within the indicated ranges, and is that result consistent across methods?
- What relationships, compensation arrangements, or other interests could affect perceived independence?
- What information was not independently verified, and what limitations were imposed?
- What events would require the advisor or board to revisit the analysis?
Good minutes record the questions asked, the materials reviewed, the answers received, and the basis for the board’s decision. They should not merely state that a presentation occurred.
Common methodology weaknesses to challenge
The most serious weaknesses often arise before the final valuation ranges appear. Forecasts may be prepared for a different purpose, updated inconsistently, or shaped by incentives connected to the transaction. Comparable sets may exclude businesses or deals that point to a different result. Adjustments may improve comparability in theory while introducing judgment that is difficult to reproduce.
- False precision: a narrow range can conceal uncertainty in forecasts, terminal value, or transaction data.
- Cherry-picked comparables: peers or transactions may be selected because their multiples support the proposed price rather than because their economics are similar.
- Inconsistent adjustments: nonrecurring items, leases, stock compensation, synergies, or debt-like obligations may be treated differently across the subject and comparable companies.
- Stale market evidence: old transactions may reflect a financing environment, interest-rate regime, or industry outlook that no longer matches the decision date.
- Unexplained weighting: the conclusion may rely heavily on one method without explaining why that method deserves greater emphasis.
- Moving assumptions: preliminary and final materials may use different forecasts, peer sets, or calculation dates without a clear change log.
A useful challenge process asks the advisor to show the bridge between source evidence and every important conclusion. The board should be able to see what changed, who authorized the change, how the change affected the ranges, and whether contradictory evidence received a fair hearing.
What does a fairness opinion not cover?
A fairness opinion is deliberately narrower than the full transaction decision. Unless the engagement expressly says otherwise, it generally does not determine whether:
- the transaction is strategically advisable;
- the board obtained the highest possible price;
- another transaction structure would be better;
- the company or buyer will remain solvent;
- the transaction is fair from a legal, tax, accounting, or regulatory perspective;
- individual stakeholders will receive the same after-tax or risk-adjusted outcome; or
- the assumptions and forecasts will prove correct.
The board must combine the financial analysis with legal advice, negotiation history, market checks, strategic alternatives, stakeholder effects, execution risk, and its own informed judgment.
How can teams make the process auditable?
A fairness opinion depends on financial judgment, but the supporting workflow should be controlled and repeatable. Transaction teams need a clear owner for each data request, a versioned evidence trail, defined review points, and explicit signoffs before materials reach the board.
A controlled approval workflow for transaction evidence
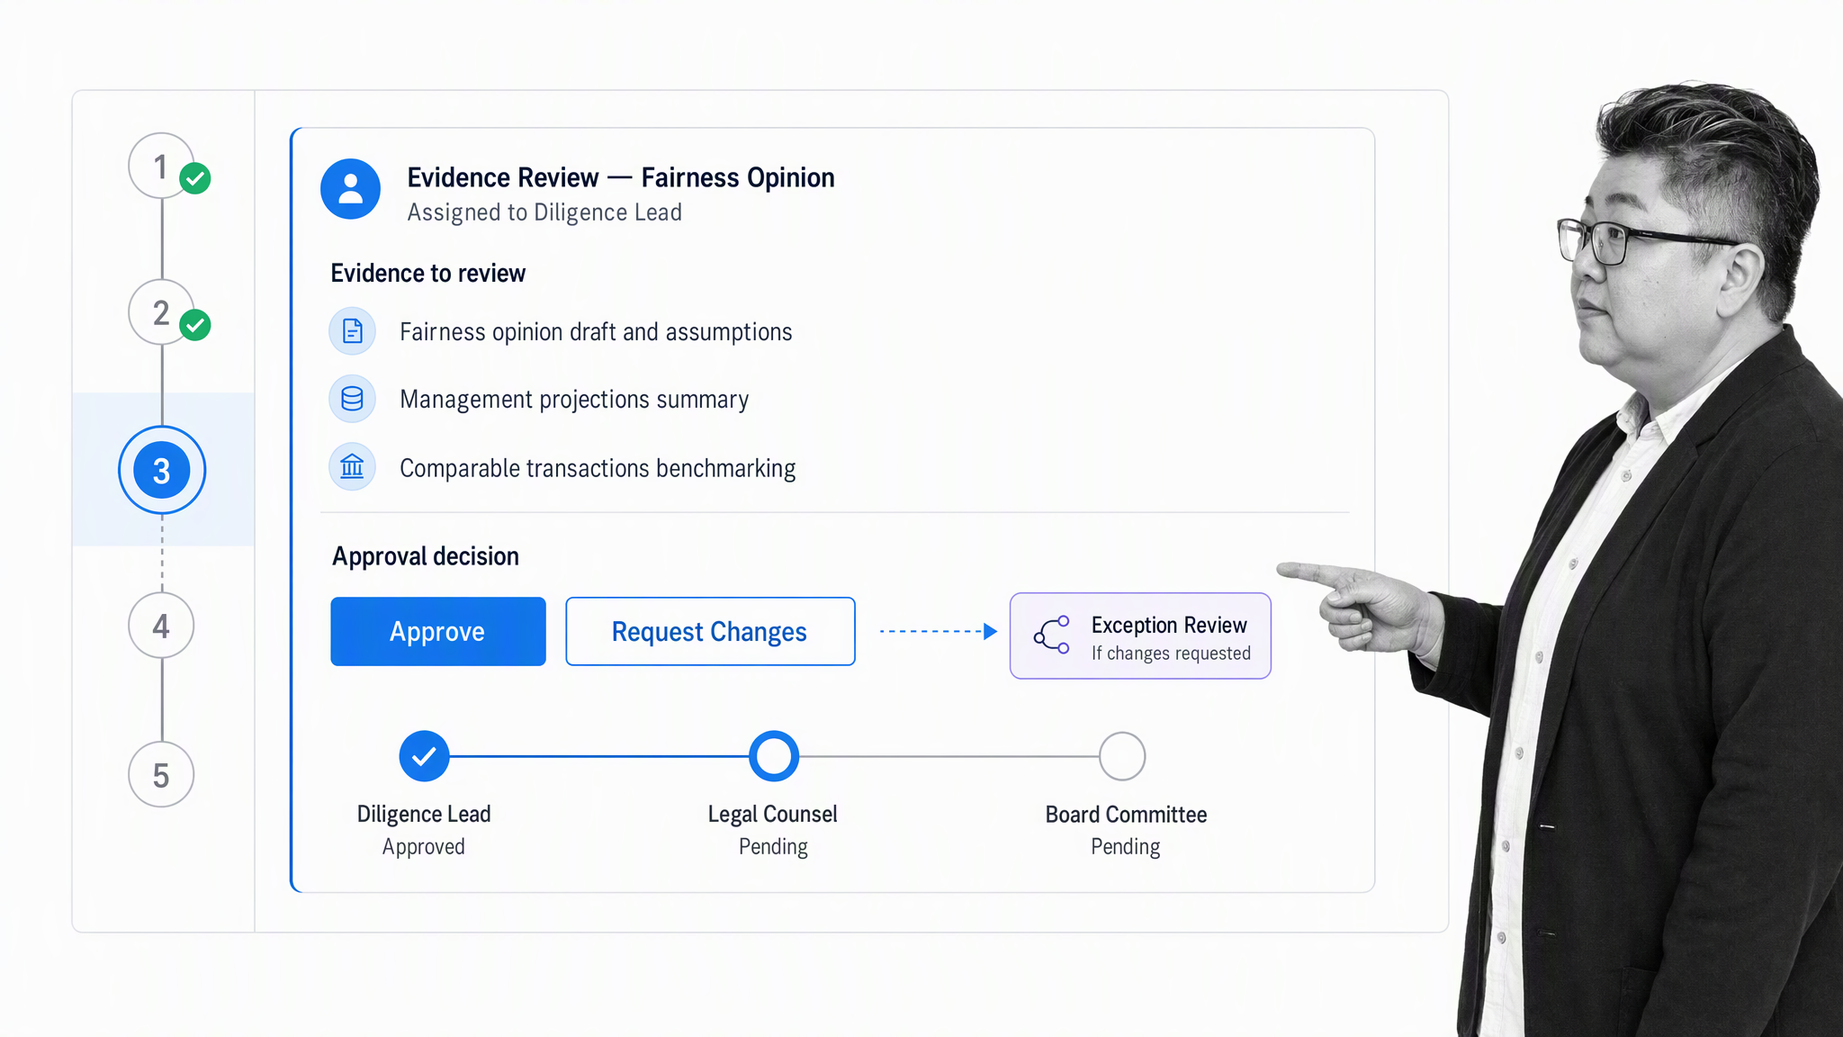
Process Street can organize the operating process around the opinion without replacing the advisor’s financial judgment. Teams can use workflows to assign diligence tasks, collect files and structured inputs, route exceptions, and create approval points for management, finance, legal, and the board. Approval workflows keep the reviewer, evidence, decision, and follow-up connected, while conditional logic can reveal the right tasks when the transaction structure or risk profile changes.
A practical workflow might include conflict disclosures, an information-request register, forecast certification, comparable-set review, model sensitivity approval, draft presentation review, board material distribution, final opinion receipt, disclosure review, and a change-control step for material developments. Teams can also start from customizable mergers and acquisitions templates and adapt them to the transaction and counsel’s requirements.
Process control does not make the conclusion correct by itself. It makes responsibilities, evidence, decisions, and exceptions visible, which helps the board and its advisors evaluate whether the underlying work was complete and timely.
Fairness opinion methodology FAQs
What is the purpose of a fairness opinion?
A fairness opinion gives a defined decision-maker an independent view of whether the financial consideration in a proposed transaction is fair to a specified constituency as of a stated date. It supports, but does not replace, the board’s judgment.
Which valuation methods are used in a fairness opinion?
Common methods include discounted cash flow, selected public companies, selected precedent transactions, historical trading, premiums paid, analyst targets, sum-of-the-parts, and asset-based analyses. The appropriate mix depends on the company, deal, and available evidence.
Is a fairness opinion legally required?
Requirements vary by jurisdiction, transaction type, regulatory regime, and governing documents. Some transactions create specific disclosure or process obligations. Boards should ask transaction counsel what is required and what role an opinion should play.
Who can provide a fairness opinion?
Investment banks and qualified independent valuation or financial advisory firms commonly provide fairness opinions. Boards should evaluate relevant experience, valuation capability, independence, conflicts, compensation, and internal review procedures.
How is a fairness opinion different from a business valuation?
A business valuation estimates the value of a business or interest for a defined purpose. A fairness opinion addresses a specific transaction and constituency, using valuation evidence to assess whether the proposed financial consideration is fair from a financial point of view.
When should a fairness opinion be revisited?
The board and its advisors should consider revisiting the analysis when transaction terms, forecasts, capital structure, financing, market conditions, or other material facts change before the relevant decision or closing.
This guide is educational and does not provide legal, tax, accounting, investment, or valuation advice. Transaction teams should work with qualified advisors and counsel for their specific circumstances.