Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Venture Capital Process Management: A Practical Guide
Venture capital process management is the operating discipline a fund uses to move opportunities from first contact through screening, due diligence, investment committee review, closing, portfolio support, and exit. It turns partner judgment into repeatable work without pretending that every company should be evaluated in exactly the same way.
A good system makes the deal pipeline easier to navigate and the decision record easier to trust. Every stage has an owner, entry criteria, required evidence, a decision, and a defined next action. The process also creates a clean handoff from the investment team to finance, legal, fund administration, portfolio operations, and investor reporting.
This guide explains how to design that system, where controls belong, which records matter, and how Process Street can coordinate the work across a venture capital technology stack. It is operational guidance, not legal, tax, accounting, or investment advice.
In this guide:
- What is venture capital process management?
- Why does venture capital process management matter?
- What stages belong in a venture capital process?
- How do you design a repeatable VC workflow?
- How should due diligence be managed?
- How do you govern investment committee decisions?
- How do you manage the portfolio after close?
- Where does Process Street fit?
- How do you improve the process?
- Venture capital process management FAQs
What is venture capital process management?
Venture capital process management is the design, execution, and improvement of the workflows that support a fund’s investment lifecycle. It covers how opportunities enter the firm, how they are evaluated, who can make decisions, what evidence must be retained, how investments are monitored, and how the fund coordinates recurring obligations.
The process begins with the investment mandate. Stage, sector, geography, check size, ownership goals, reserve strategy, conflicts, and prohibited investments shape what should enter the pipeline. Those rules then drive screening, diligence depth, committee authority, closing work, and portfolio reporting.
Process management does not replace investing skill. It protects that skill from operational noise. Partners can spend more time on judgment when the system captures intake consistently, routes work to the right reviewer, exposes missing evidence, and records why a decision moved forward or stopped.
Research on venture decision-making supports this lifecycle view. An NBER summary of a large survey of institutional venture capitalists organizes VC work around sourcing, selection, valuation, deal structure, post-investment value, exits, internal organization, and LP relationships. A practical operating system must connect those activities instead of treating the deal pipeline as the whole job.
Why does venture capital process management matter?
Venture investing combines a high volume of incomplete information with a small number of consequential decisions. The work is relationship-driven, but it also depends on consistent follow-through. A referral can go cold because nobody owns the next step. A diligence concern can disappear in a message thread. A committee condition can be approved but never tracked through closing. A portfolio warning can wait until the next scheduled review.
Process management reduces those failure modes by making work observable and owned. It also creates continuity when team members change, when the firm raises a new fund, or when the same portfolio company returns for a follow-on decision.
- Speed: clear stages and owners reduce waiting time without weakening review.
- Consistency: each opportunity faces the same core questions, with deeper branches where risk requires them.
- Decision quality: reviewers see claims, evidence, open questions, and conflicts in one record.
- Accountability: every request, approval, exception, and follow-up action has an owner and due date.
- Institutional memory: the firm retains the reasoning behind decisions, not just the outcome.
- Portfolio support: recurring updates become decisions and actions instead of passive reports.
- Control: sensitive tasks, approvals, and evidence remain tied to the workflow that produced them.
What stages belong in a venture capital process?
The names vary by fund, but the operating cycle usually follows a recognizable path. The stages should be explicit enough to guide work while remaining flexible enough for different sectors, rounds, and deal structures.
| Stage | Core decision | Required output |
|---|---|---|
| Sourcing and intake | Does this opportunity belong in the pipeline? | Canonical company and opportunity record |
| Initial screening | Does it fit the mandate and deserve more time? | Screening decision and next owner |
| Partner review | Is there enough conviction for diligence? | Diligence scope and sponsor |
| Due diligence | What evidence supports or weakens the thesis? | Evidence file, risks, and open questions |
| Investment committee | Should the fund invest, under which conditions? | Recorded decision, terms, and conditions |
| Closing | Are documents, approvals, and funds-flow work complete? | Closing confirmation and portfolio handoff |
| Portfolio management | What changed, what action is needed, and who owns it? | KPI review, risk record, and support actions |
| Follow-on or exit | How should the fund respond to the next capital or liquidity event? | Decision record and execution plan |
The sequence is recognizable outside any one firm. A Stanford Graduate School of Business overview of the VC deal funnel describes evaluation of the business model, the founding team, partner review, and deeper due diligence. A fund should adapt that broad path to its mandate, authority structure, and professional obligations.
How do you design a repeatable VC workflow?
Start with the decision points, not the software. A workflow is useful when it tells the team what must be true before work advances. Each stage needs an entry trigger, a responsible owner, required evidence, a decision authority, an exception route, and an output that the next stage can trust.
Build the deal intake and screening pipeline
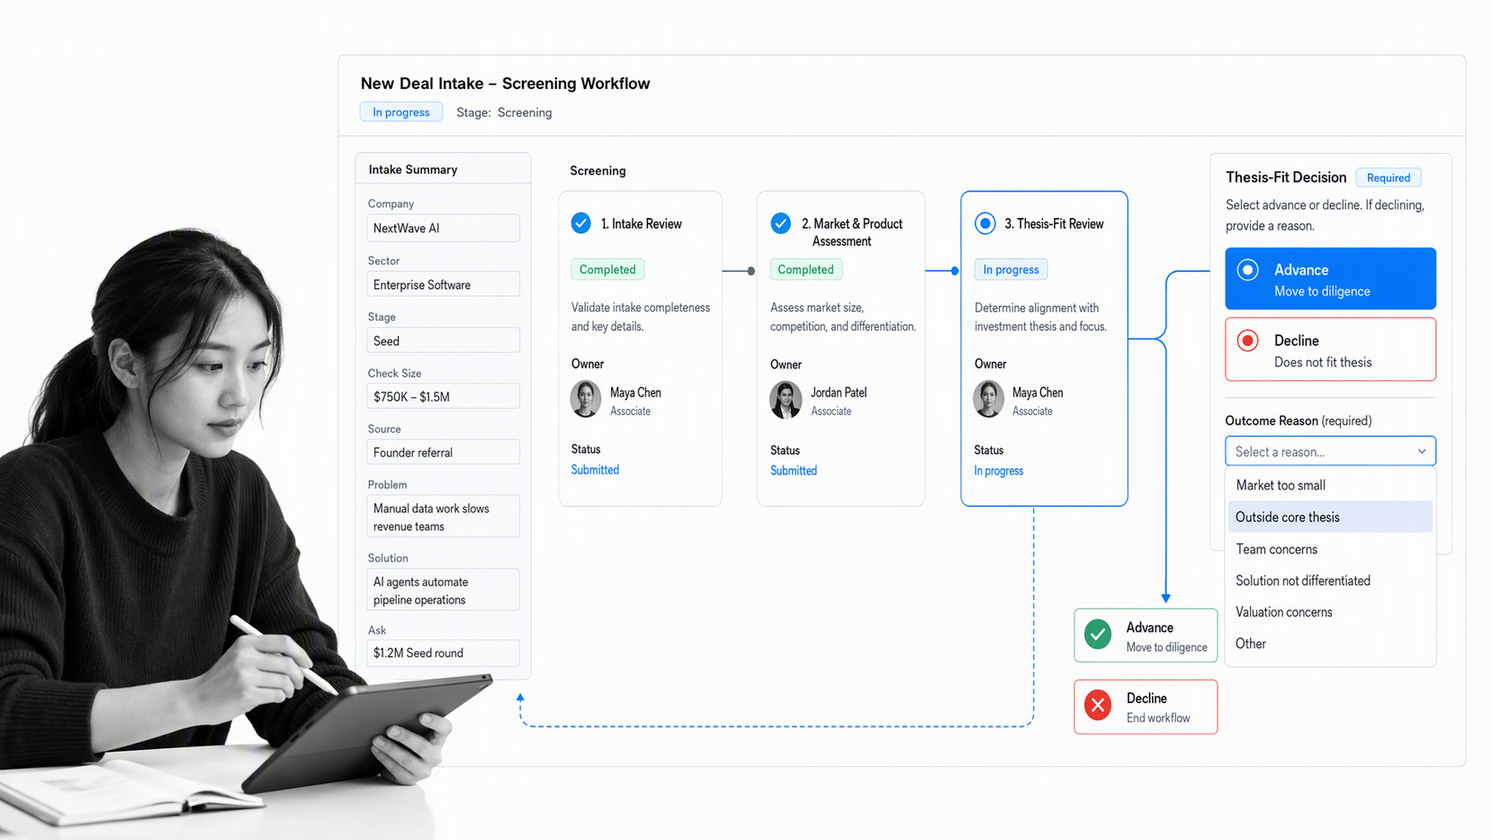
Create one canonical opportunity record even when a company arrives through several channels. Capture the company, founders, source relationships, stage, sector, geography, amount sought, key materials, conflicts, and current owner. Preserve every source connection, but avoid parallel records that split the history.
The screening rubric should be short enough to use and specific enough to produce a decision. Typical questions cover mandate fit, market, team, product, evidence of demand, timing, ownership potential, portfolio fit, and obvious risks. Reviewers should choose a clear outcome: decline, request information, hold, advance, or escalate. Every outcome needs a reason and a next action.
Set service expectations by stage. An inbound pitch may require acknowledgement within a defined window. A partner-sponsored opportunity may need an initial review meeting. A deal in diligence may need a daily open-issues review. The goal is not speed for its own sake. It is preventing avoidable silence and ambiguity.
Assign ownership and decision rights
Separate the workflow owner from the decision authority. The owner keeps the work moving, requests evidence, and closes gaps. The authority decides whether the opportunity advances. Define who can recommend, approve, veto, abstain, or advise. Conflicts should change the route automatically and remain visible in the final record.
Use one accountable owner for the full opportunity even when domain specialists own individual reviews. Without that role, parallel diligence becomes a collection of good analyses with no one responsible for integrating them into a recommendation.
How should due diligence be managed?
Run evidence-based due diligence
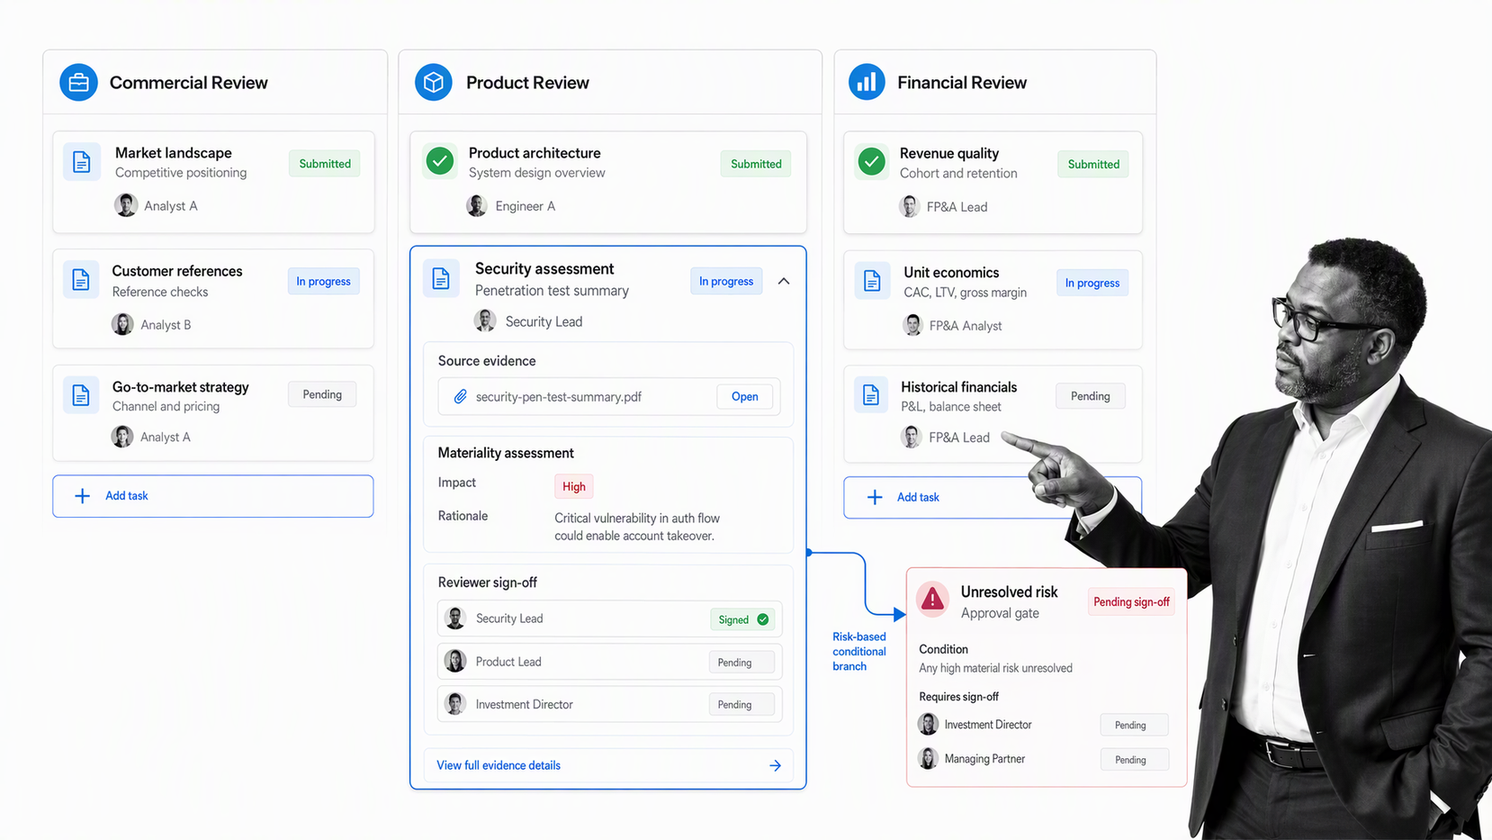
Due diligence should test the investment thesis, not merely fill a data room checklist. Begin with the claims that matter most to the decision. Assign a reviewer, evidence requirement, materiality threshold, and due date to each question. Capture both confirming and disconfirming evidence.
The exact work depends on the company and round, but common streams include team and references, market, customer evidence, product and technology, financials, ownership, legal, security, regulatory exposure, and proposed terms. Use conditional paths so the review expands when a risk appears. A regulated product, concentrated revenue base, unusual ownership history, or significant security dependency may require specialist review.
A reusable due diligence workflow can standardize the core sequence while leaving room for deal-specific tasks. The final memo should link each material conclusion to its source, state what remains unknown, and distinguish verified facts from assumptions or forecasts.
- Scope: which thesis questions and risks must be tested?
- Owner: who is accountable for each review stream?
- Evidence: what source supports the conclusion?
- Materiality: what would change the recommendation or terms?
- Exception: who decides whether an unresolved issue is acceptable?
- Closure: what must happen before the deal can enter committee review?
AI can help classify documents, summarize interviews, compare claims, and draft questions, but it should not quietly become the decision-maker. Keep source links, reviewer sign-off, and clear limits on what the model may access or infer. The NIST AI Risk Management Framework is a useful reference for governing, mapping, measuring, and managing AI risk when a fund adds AI-assisted work.
How do you govern investment committee decisions?
Control investment committee decisions
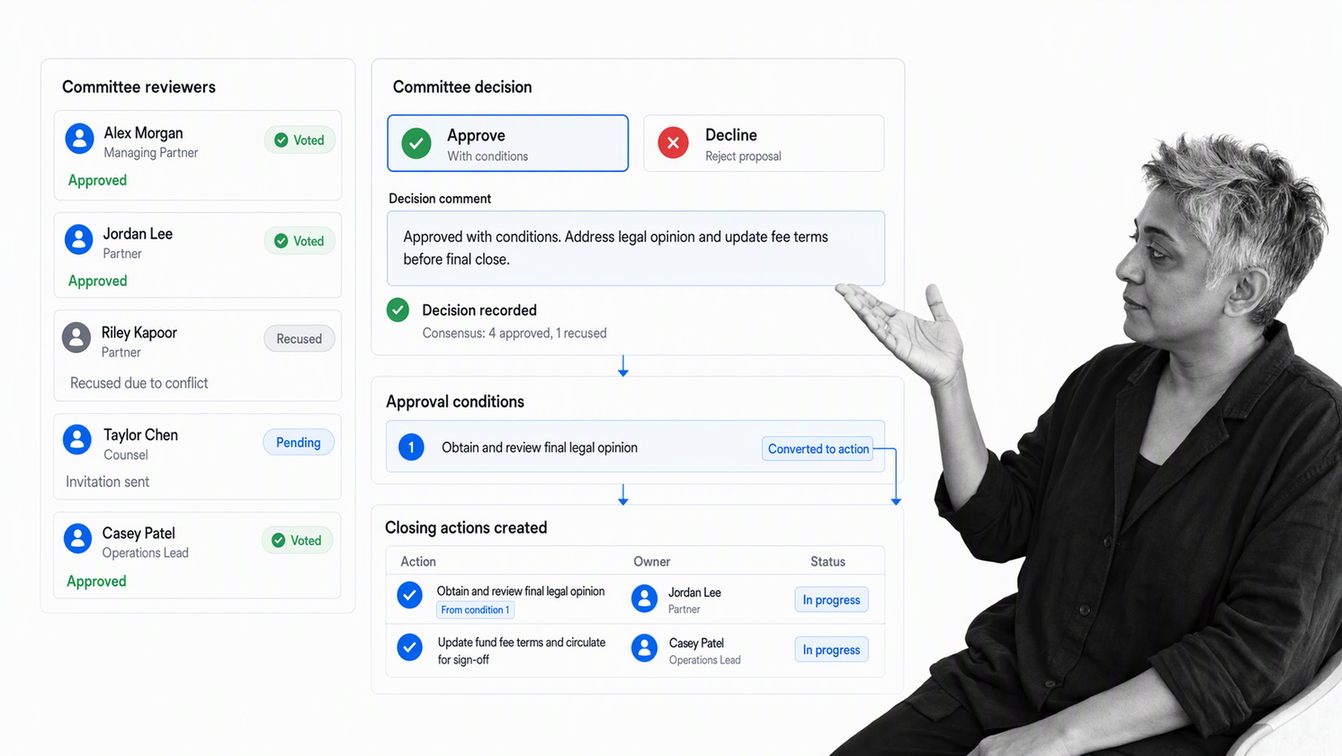
Investment committee is a control point, not a presentation ritual. The committee should receive the recommendation, core evidence, dissenting views, unresolved risks, proposed terms, ownership impact, reserve implications, conflicts, and closing conditions in a consistent package.
Record attendance, recusals, the decision rule, votes or consensus, comments, conditions, allocation, and follow-up owners. If the committee approves subject to a reference, revised term, technical review, or legal confirmation, that condition should become an owned closing task. Approval is not the same as completion.
Transaction documents require professional advice and careful tailoring. The NVCA model legal documents provide widely used starting points for venture financings, but the operating workflow still needs to identify the authoritative version, responsible counsel, open issues, signatories, and evidence of completion.
Create a clean rejection path too. Record the reason at the right level of detail, protect sensitive notes, complete founder communication, update relationship ownership, and preserve any follow-up date. A respectful decline process protects the firm’s reputation and keeps future opportunities open.
How do you manage the portfolio after close?
The close should trigger a portfolio onboarding workflow. Confirm ownership data, reporting contacts, board and observer roles, information rights, reporting cadence, KPI definitions, support priorities, reserve assumptions, and material-risk triggers. The handoff should not depend on the deal lead remembering to brief every downstream team.
Turn portfolio updates into owned actions
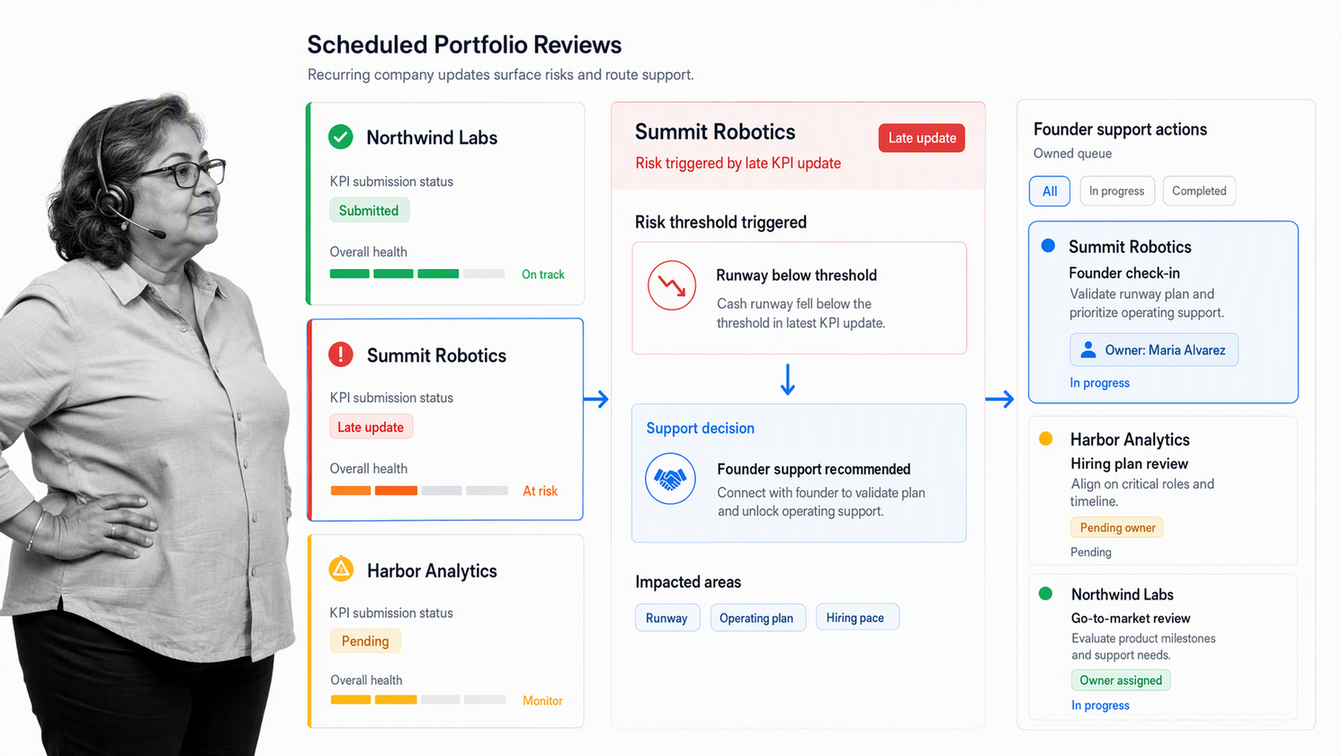
Standardize the recurring package enough to compare periods and companies, but keep room for context. Revenue, cash, runway, hiring, product progress, customer concentration, financing plans, and board matters may be relevant, depending on the business. The important design question is what happens when a number is missing, late, inconsistent, or outside the expected range.
A portfolio review should end with decisions and owners. Examples include a customer introduction, recruiting support, financing preparation, board follow-up, risk review, reserve analysis, or escalation to partners. Track those actions in the same operating system instead of leaving them in meeting notes.
Apply the same discipline to follow-on investments and exits. Revisit the thesis, current evidence, ownership, reserves, alternatives, conflicts, and expected fund impact. Use the existing company record so the committee can see what changed since the initial decision.
Where does Process Street fit?
Process Street can serve as the workflow and control layer for venture capital process management. It does not need to replace the fund CRM, cap table, accounting platform, data room, or legal records. It coordinates the work that crosses those systems and keeps tasks, forms, evidence, approvals, comments, files, and activity history connected to each workflow run.
The platform supports workflows, forms, conditional logic, approvals, enforced task order, dynamic due dates, role assignments, scheduled workflows, and analytics. Those capabilities can turn an operating policy into an executable process. A fund can use them for deal intake, screening, diligence, committee review, closing, portfolio onboarding, quarterly reviews, valuation support, compliance calendars, and LP reporting preparation.
Process Street has 5,000+ integrations, plus API and webhook options. That lets the workflow layer coordinate with specialist systems while keeping ownership, approvals, and evidence in one controlled execution record.
| Venture process | Process Street workflow pattern | Control outcome |
|---|---|---|
| Deal intake | Form, routing logic, owner assignment | One canonical entry path and visible next step |
| Screening | Required fields, conditional branches, deadlines | Consistent core review with risk-based depth |
| Due diligence | Parallel tasks, evidence fields, approvals | Traceable conclusions and managed exceptions |
| Investment committee | Approval gate, comments, conditions | Recorded decision and owned follow-up |
| Closing | Enforced order, document checks, handoff tasks | No confusion between approval and completion |
| Portfolio review | Scheduled runs, KPI requests, action routing | Updates become decisions and accountable work |
Start with one high-friction process, such as diligence or quarterly portfolio review. Map the current path, define the authoritative systems, then build the workflow around the real decision points. The broader process management software guide explains how workflow execution, ownership, and evidence fit together.
How do you improve the process?
Improvement should use evidence from the workflow. Review where opportunities wait, which fields are repeatedly missing, which diligence tasks reopen, how often committee conditions delay closing, and which portfolio requests require manual chasing. A faster process is only better when it preserves decision quality and control.
- Choose one workflow with visible friction or risk.
- Map the current trigger, stages, decisions, systems, owners, and outputs.
- Remove steps that do not change a decision, meet an obligation, or create necessary evidence.
- Define entry and exit criteria for every remaining stage.
- Add conditional paths for material risks instead of burdening every deal equally.
- Pilot the workflow with realistic edge cases and several reviewers.
- Measure cycle time, waiting time, rework, missing evidence, overdue actions, and exceptions.
- Review the process on a fixed cadence and assign improvements like any other work.
Use a structured risk management process for the operating system itself. Identify key-person dependencies, access risks, vendor outages, inconsistent data definitions, confidentiality exposures, and tasks that regularly bypass approval. Give each risk an owner, response, evidence requirement, and review date.
The strongest venture capital process is not the most complicated one. It is the one that lets the team move quickly when evidence is strong, slow down when risk is material, support founders after the investment, and explain important decisions without rebuilding the story from inboxes and spreadsheets.
Venture capital process management FAQs
What is venture capital process management?
Venture capital process management is the design, execution, and improvement of the workflows a fund uses for sourcing, screening, due diligence, investment decisions, closing, portfolio support, follow-on investments, and exits.
What is the difference between a VC process and a deal pipeline?
A deal pipeline tracks opportunities and their stages. The broader VC process also includes diligence, committee governance, closing, portfolio monitoring, fund operations, reporting, controls, and the handoffs between people and systems.
Which venture capital process should a fund automate first?
Start with a recurring, high-friction workflow such as deal intake, due diligence, investment committee preparation, closing, or portfolio review. Choose one with clear owners, repeated steps, and visible evidence gaps.
How do you keep VC due diligence consistent without making it rigid?
Use a small set of required core questions, then branch by stage, sector, geography, deal structure, and risk. Keep one owner accountable for the full review and require sources for material conclusions.
What should an investment committee workflow record?
Record attendees, recusals, the recommendation, material evidence, unresolved risks, proposed terms, the decision, conditions, allocation, comments, and the owners and deadlines for every follow-up action.
Can Process Street replace venture capital CRM or fund accounting software?
Process Street is best used as the workflow and control layer around specialist systems. The CRM, cap table, accounting, legal, and reporting platforms can remain authoritative while Process Street coordinates tasks, evidence, approvals, exceptions, and handoffs.