

Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Blockchain Technology in Financial Services: Uses, Benefits, and Risks
Blockchain technology in financial services is a way for several parties to maintain a shared record of transactions, assets, or obligations without relying on separate ledgers that must be reconciled after every event. Its value is not that every record becomes public or that intermediaries disappear. Its value is that authorized participants can agree on one transaction state, verify how it changed, and automate selected rules around that state.
That promise matters in finance because payments, securities, trade documents, collateral, and compliance evidence often cross institutional boundaries. It also creates new responsibilities. A ledger can be tamper-resistant while the surrounding process still fails through bad data, stolen credentials, flawed code, unclear legal rights, or weak exception handling. This guide explains where blockchain fits, where it does not, and how finance teams can evaluate it with operational discipline.
In this guide:
- What is blockchain technology in financial services?
- How does blockchain work in a financial process?
- Which blockchain network type fits financial services?
- Where is blockchain used in financial services?
- What benefits can blockchain create?
- What are the risks and limitations?
- How should a financial institution evaluate a blockchain project?
- How do you operationalize blockchain controls?
- Frequently asked questions
What is blockchain technology in financial services?
Blockchain is a type of distributed ledger in which records are grouped, ordered, and cryptographically linked. Participants follow agreed rules to validate new entries and maintain copies of the ledger. The National Institute of Standards and Technology describes blockchain as a shared ledger that is tamper-evident and tamper-resistant, which is more precise than calling every blockchain record permanently immutable. See the NIST blockchain overview.
In financial services, the ledger may represent transfers of value, ownership records, payment instructions, collateral positions, trade documents, identity attestations, or events that trigger contractual obligations. Some networks allow broad participation. Others limit membership, validation, and data access to approved institutions. The right model depends on who must share the record, who is trusted to validate it, and what privacy or supervisory obligations apply.
Blockchain is not the same as cryptocurrency. Cryptocurrency is one application of a blockchain or similar distributed ledger. A bank, insurer, asset manager, market utility, or fintech can use distributed ledger technology without creating a freely traded token. Likewise, tokenizing an asset does not remove the need to establish who owns the underlying asset, what legal rights the token conveys, and how errors or disputes are resolved.
How does blockchain work in a financial process?
A blockchain process begins when a participant proposes a transaction. The network checks that proposal against its rules, authorized validators agree whether it is valid, and the accepted record is added to the ledger. Cryptographic links connect the new record to prior records, making later alteration detectable. The exact design varies, but the operating questions stay consistent.
- Identity: Who may submit, view, validate, or approve a transaction?
- Data: Which facts live on the ledger, and which remain in protected systems off the ledger?
- Validation: What rules determine whether a proposed transaction is accepted?
- Consensus: Which participants must agree before the record becomes authoritative?
- Finality: At what point is the transaction legally and operationally complete?
- Exceptions: What happens when a transaction is wrong, disputed, delayed, or dependent on unavailable external data?
Smart contracts add programmable logic. They can check conditions, restrict transfers, calculate amounts, or trigger another step when defined inputs are present. They do not understand intent, law, or incomplete real-world information by themselves. Every automated condition needs an owner, approved source data, testing, change control, monitoring, and a controlled path for exceptions.
Which blockchain network type fits financial services?
The most useful distinction is not simply public versus private. Finance teams should compare who can join, who can validate, who can see each field, who can change the protocol, and who is accountable when the network fails. Those choices determine the control model.
Permissionless networks
Permissionless networks allow broad participation and rely on open protocol rules. They can support assets and services that need global accessibility and composability. The tradeoff is less control over validators, governance, transaction visibility, and protocol changes. A regulated institution must determine how customer identification, sanctions controls, privacy, transaction monitoring, custody, and legal obligations apply before connecting a production process.
Permissioned networks
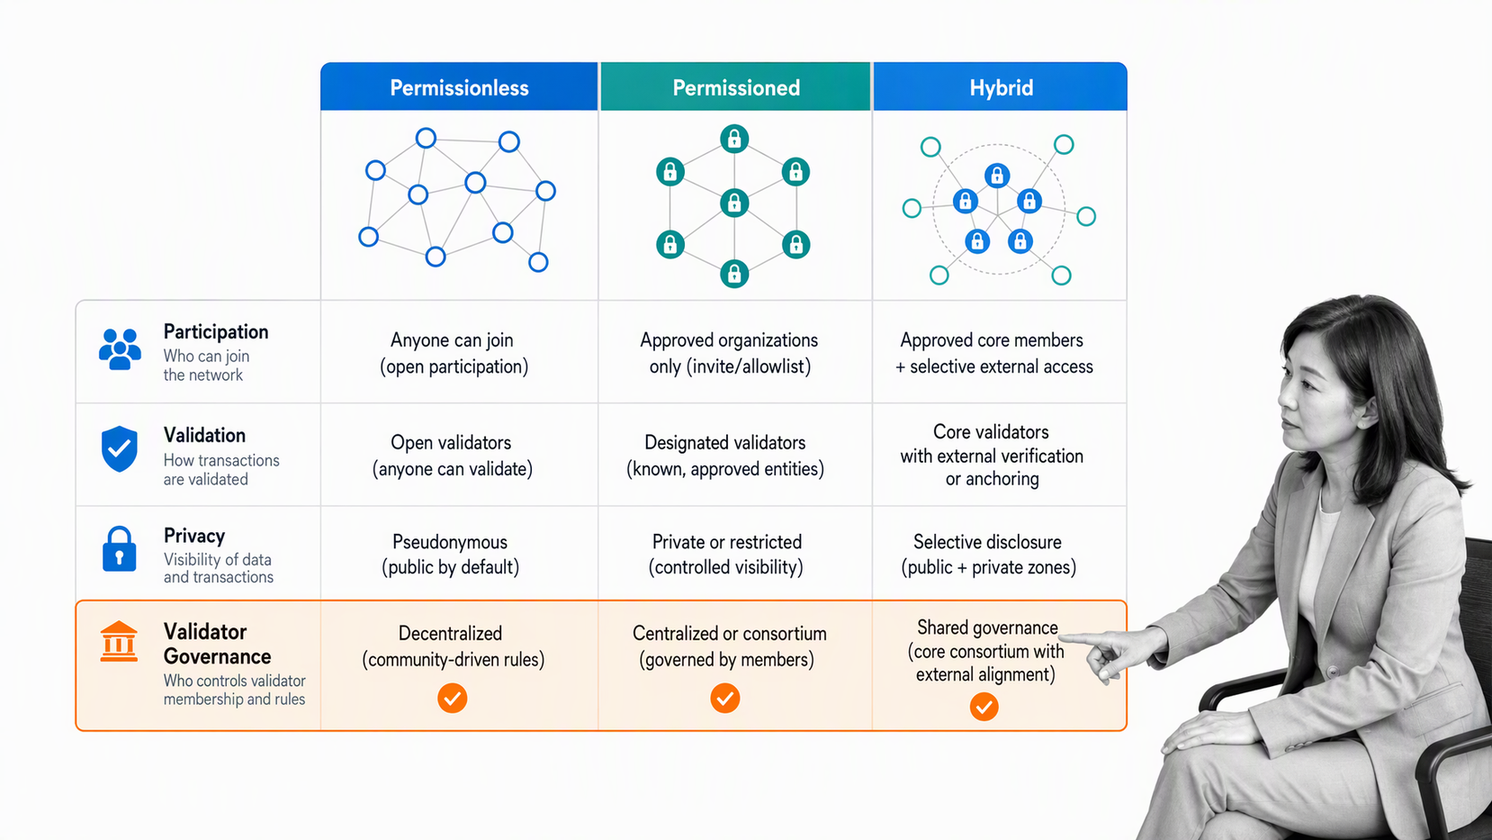
Permissioned networks restrict participation to approved entities and can assign different rights to operators, validators, observers, and users. This model can align more naturally with institutional privacy, governance, and accountability. It also concentrates trust in the consortium or platform operator, so the organization still needs controls for membership, privileged access, software changes, resilience, data sharing, and exit arrangements.
Hybrid designs
Hybrid designs combine controlled institutional processes with a broader network or use a ledger for selected transaction events while keeping sensitive records elsewhere. They can preserve confidentiality and integrate with existing systems, but every boundary becomes a control point. Teams must reconcile on-chain and off-chain records, secure data feeds, define which record prevails, and test failure recovery across both environments.
| Design question | Permissionless emphasis | Permissioned emphasis | Control implication |
|---|---|---|---|
| Participation | Open or broadly accessible | Approved members | Identity and access model |
| Validation | Protocol-based validator set | Named institutional validators | Accountability and concentration |
| Data visibility | Often broadly observable | Can be segmented | Privacy and confidentiality |
| Governance | Community or protocol governance | Consortium or operator governance | Change approval and disputes |
| Integration | Public network interfaces | Institutional interfaces and shared rules | Reconciliation and resilience |
Where is blockchain used in financial services?
A strong use case usually has several organizations updating the same economic event, repeated reconciliation between their systems, a need for traceable history, and rules that can be expressed clearly. The Federal Reserve has examined distributed ledger technology in payments, clearing, and settlement as a way to address operational and financial frictions while also identifying practical adoption challenges. Read the Federal Reserve paper on distributed ledgers.
Payments, clearing, and settlement
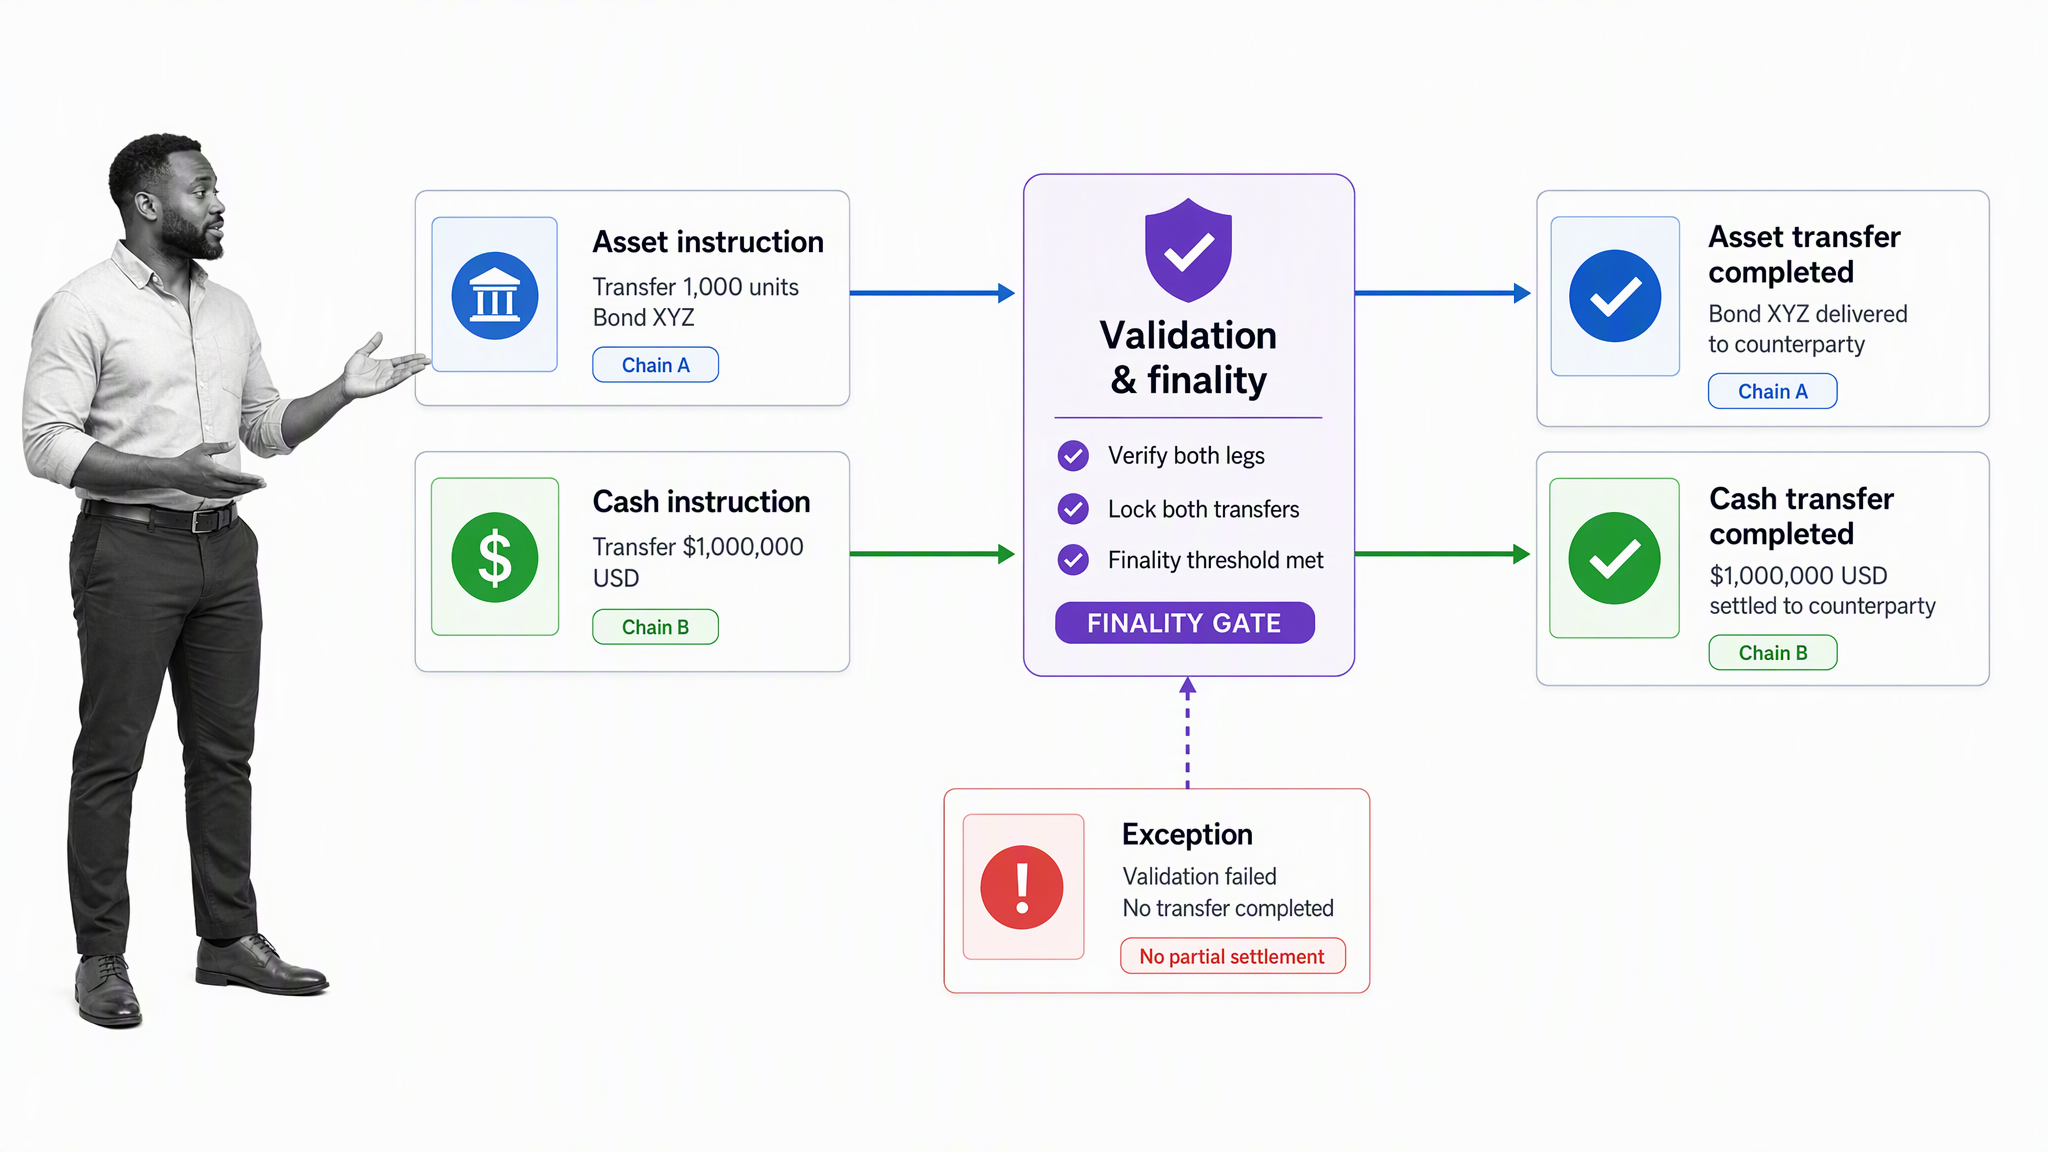
A shared ledger can give participating institutions a synchronized view of payment instructions and settlement state. Programmable conditions may coordinate the exchange of assets and payment so one leg does not complete without the other. The potential benefit is less reconciliation and clearer status, but the design must still define settlement finality, liquidity, reversals, operating hours, and the role of the settlement asset.
Tokenization of financial and real-world assets
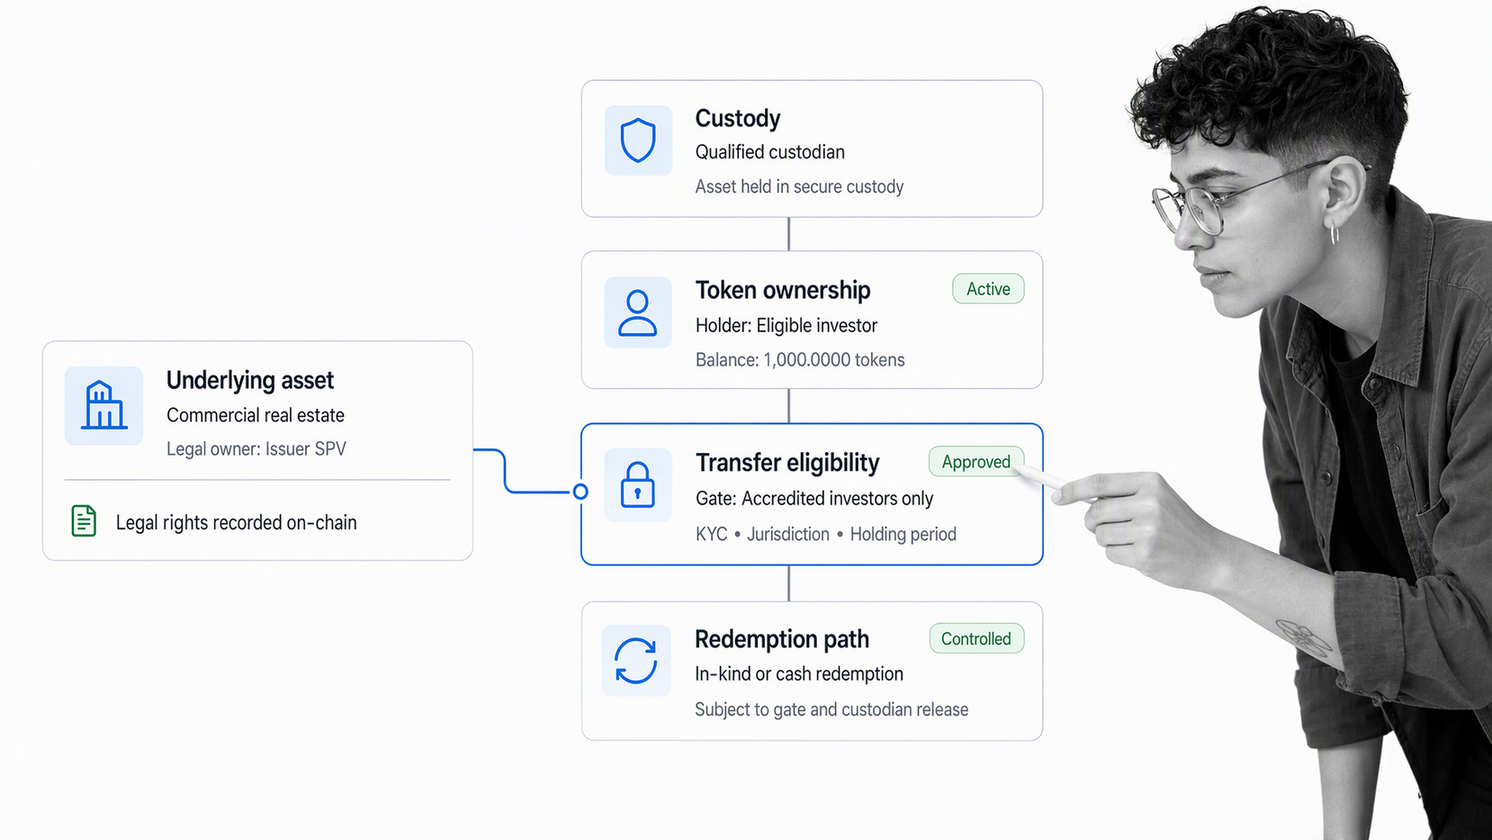
Tokenization represents an asset or claim on a distributed ledger. It can support programmable transfer restrictions, fractional interests, collateral mobility, and more direct servicing workflows. The token is not a substitute for the legal asset. Issuers and operators must connect the digital record to enforceable ownership, custody, disclosures, valuation, redemption, and the authoritative off-chain registry where one exists.
Trade finance and shared documents
Trade finance involves buyers, sellers, banks, carriers, insurers, and customs processes that may each maintain separate records. A shared ledger can coordinate document status and reduce duplicate checks. The difficult work is agreeing on common data, recognizing electronic documents across jurisdictions, integrating physical shipment events, and deciding who corrects an inaccurate source event.
Identity and compliance evidence
A network can share verifiable attestations that a customer or counterparty completed an approved check without exposing every underlying document to every participant. That may reduce duplicated reviews, but privacy and accountability remain central. Institutions still need a responsible party for due diligence, refresh cycles, sanctions screening, suspicious activity processes, consent, and corrections. A ledger records evidence. It does not decide whether the evidence satisfies every institution’s obligations.
Insurance, lending, and collateral
Smart-contract logic can coordinate premium events, claims inputs, covenant checks, loan servicing, and collateral movements. These processes depend heavily on external facts, from damage assessments to market prices. The data source, validation method, override authority, and dispute process are therefore as important as the code that consumes the data.
What benefits can blockchain create?
Blockchain creates value when the shared ledger removes a real coordination cost. Benefits should be stated as hypotheses to test, not architecture guarantees. A successful network may reduce duplicate recordkeeping, shorten handoffs, make transaction status easier to verify, and embed selected rules directly in the transaction flow.
- Shared transaction state: Participants work from one agreed record instead of reconciling several versions after the fact.
- Traceability: Ordered, linked events make it easier to reconstruct who submitted, validated, and changed a transaction state.
- Programmability: Defined conditions can restrict or trigger actions without waiting for a separate manual handoff.
- Resilience: Distributed copies can reduce dependence on one database, provided nodes, access paths, and recovery procedures are designed well.
- New operating models: Tokenized assets and shared networks can support different issuance, servicing, collateral, and settlement patterns.
The baseline matters. If a conventional shared service or database already provides fast, reliable processing under one trusted operator, blockchain may add cost without solving a meaningful trust or reconciliation problem. The correct comparison is between end-to-end operating models, not between blockchain and an abstract idea of legacy technology.
What are the risks and limitations?
Blockchain changes where trust sits. It can reduce reliance on one recordkeeper while increasing reliance on software, cryptographic keys, validators, governance bodies, data providers, custodians, and bridges between networks. The Financial Stability Board identifies potential vulnerabilities in distributed-ledger tokenization related to liquidity and maturity mismatch, leverage, asset price and quality, interconnectedness, and operational fragilities. See the FSB assessment of tokenisation.
| Risk area | Typical failure | Control question |
|---|---|---|
| Legal and regulatory | The token, record, or automated event lacks recognized legal effect | Which law, contract, and authority establish ownership and finality? |
| Privacy | Sensitive data is visible to the wrong participant or cannot be corrected | What data is shared, encrypted, retained, or kept off-chain? |
| Key management | A lost or compromised key enables unauthorized action | How are keys issued, stored, rotated, recovered, and revoked? |
| Smart-contract logic | Code executes an unintended rule or cannot handle an exception | Who tests, approves, monitors, pauses, and changes the code? |
| Third parties | A custodian, data provider, bridge, or operator fails | What dependencies, service levels, alternatives, and exit plans exist? |
| Interoperability | The ledger cannot exchange reliable state with existing systems | How are records mapped, reconciled, and recovered after a mismatch? |
| Governance | Participants cannot agree on upgrades, disputes, or incident response | Who decides, who can object, and how is accountability enforced? |
| Operational resilience | The network or access path is unavailable at a critical time | What are the recovery objectives, fallback process, and tested manual controls? |
The Bank for International Settlements also highlights that tokenized systems can rely on different settlement assets and on third parties such as custodians, data providers, and interoperability services, each with a different risk profile. Review the BIS summary of tokenisation risks.
How should a financial institution evaluate a blockchain project?
Start with the business process, not the technology. A pilot should prove that a shared ledger improves a measurable outcome under realistic legal, security, operational, and integration constraints. If the business case only works after assuming perfect data, universal adoption, instant regulatory clarity, or no exceptions, it is not ready.
Define the coordination problem
Map every participant, system of record, handoff, reconciliation, delay, dispute, and control. Identify exactly where parties maintain competing versions of the same event. State the target outcome in operational terms, such as fewer reconciliation breaks, clearer collateral status, faster document verification, or reduced time waiting for approvals.
Decide whether a shared ledger is necessary
Ask whether one trusted operator can solve the problem with a conventional database or shared service. Blockchain earns consideration when several parties need write access, no single party should control the record, history must be independently verifiable, and common rules can govern validation. Otherwise, the simpler architecture is usually easier to secure and operate.
Design governance before code
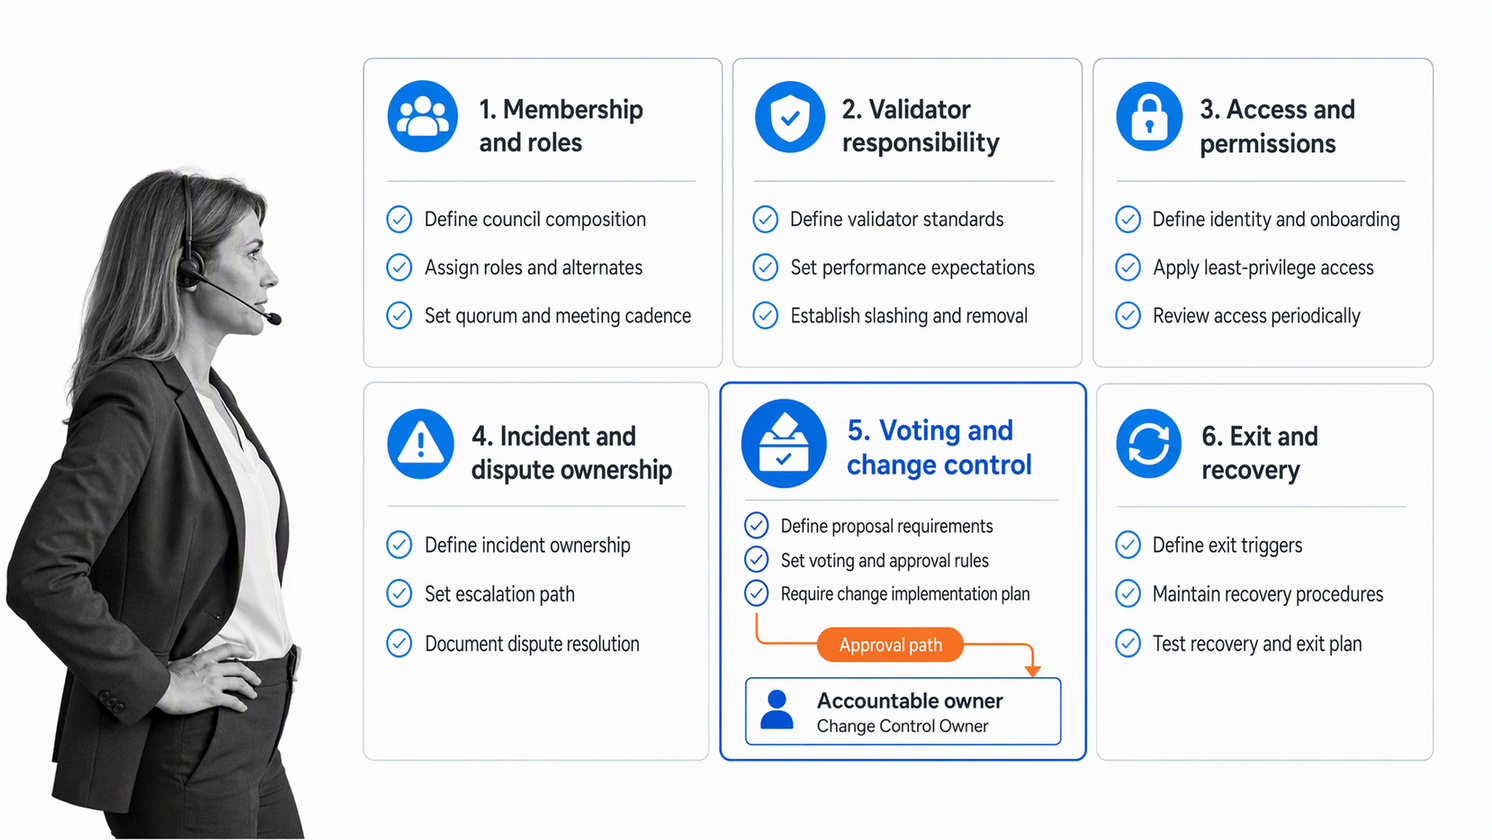
Define membership, voting rights, validator responsibilities, access levels, change approval, incident response, dispute resolution, liability, data ownership, audit rights, and exit procedures. Governance is part of the product. It cannot be deferred until after a technical proof of concept.
Build the control model
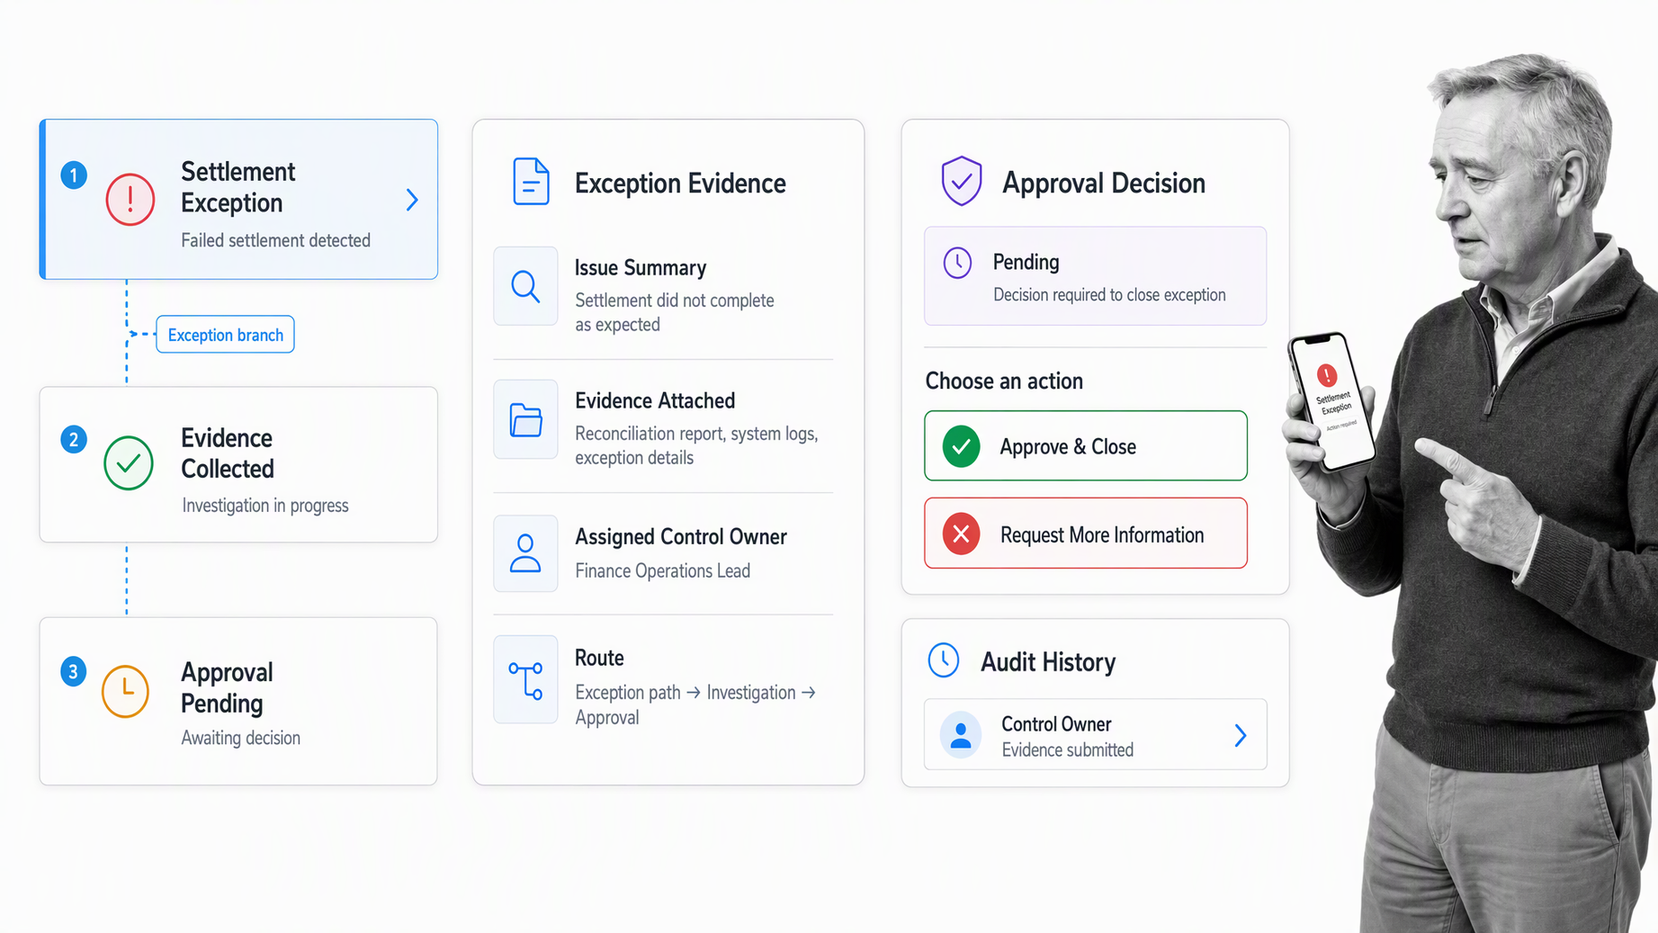
Document controls for identity, key custody, transaction approval, source data, code review, release management, privileged access, monitoring, reconciliation, exception handling, record retention, and recovery. Assign an owner and evidence requirement to each control. Connect the control to the specific risk it reduces.
Pilot one bounded workflow
Choose a process with a clear start and end, willing counterparties, representative exceptions, and a credible fallback. Test normal transactions and failure states. Include bad data, delayed validation, lost access, a disputed transaction, unavailable dependencies, and a software change. A pilot that tests only the happy path proves very little.
Measure the full operating model
Compare the pilot with the current process using cycle time, reconciliation effort, exception rate, control coverage, participant effort, resilience, and total operating cost. Include integration, governance, legal, security, training, monitoring, and vendor dependencies. Decide whether to scale, redesign, or stop based on that evidence.
How do you operationalize blockchain controls?
The ledger does not run the surrounding organization. Teams still need repeatable procedures for onboarding network participants, approving wallets or accounts, reviewing smart-contract changes, validating external data, investigating exceptions, reconciling records, responding to incidents, and producing evidence for auditors and regulators.
Process Street turns those procedures into executable workflows with assigned tasks, required form fields, conditional paths, approvals, due dates, automations, and audit history. A finance team can coordinate the controls around a blockchain network while the ledger remains the transaction infrastructure. For example, an exception can launch a structured investigation, route a code change through review, collect evidence, and require approval before production access is restored. Explore workflow automation and Process Street’s compliance workflows.
A practical control workflow should name the trigger, owner, required evidence, decision rights, time limit, escalation path, and system where the final record is retained. It should also distinguish automated evidence from human judgment. Use a repeatable business process management approach so pilots, production operations, and control improvements follow the same accountable lifecycle.
| Control workflow | Trigger | Required evidence | Decision owner |
|---|---|---|---|
| Participant onboarding | New institution or operator requests access | Identity, authority, due diligence, technical readiness | Network governance owner |
| Smart-contract change | Business rule or code needs revision | Requirements, tests, review, approvals, rollback plan | Product and control owners |
| Transaction exception | Validation, settlement, or reconciliation fails | Event logs, source records, impact assessment, resolution | Operations owner |
| Privileged access review | Scheduled review or role change | Current roles, usage, approvals, revocations | Security owner |
| Incident response | Integrity, availability, or confidentiality event | Timeline, affected records, containment, recovery, lessons | Incident commander |
The goal is not to wrap every blockchain event in manual approval. It is to make accountability explicit where the technology meets people, institutions, law, and external data. The strongest operating model automates routine controls, surfaces exceptions quickly, and preserves evidence without asking teams to reconstruct the story later.
Frequently asked questions
What is blockchain technology in financial services?
It is the use of a shared, cryptographically linked ledger to record and validate financial events across authorized participants. The design may be open or permissioned. In regulated finance, the ledger is only one part of a broader operating model that also includes identity, legal rights, controls, governance, and exception handling.
How is blockchain used by financial institutions?
Common areas include payments, clearing and settlement, trade finance, tokenized assets, collateral records, shared identity evidence, and automated contract events. The strongest candidates involve several parties maintaining the same transaction state and spending significant effort reconciling separate records.
What is the difference between blockchain and a traditional database?
A traditional database usually has one authoritative operator. A blockchain can distribute validation and recordkeeping across several participants using agreed consensus rules. That structure can reduce reconciliation in the right network, but it also introduces governance, privacy, performance, and change-management questions.
Are blockchain records completely immutable?
A blockchain is better described as tamper-evident and tamper-resistant. Cryptographic links make unauthorized changes detectable and increasingly difficult as records accumulate. Access privileges, consensus rules, administrator powers, off-chain data, and application code still need controls.
What are the main risks of blockchain in finance?
Material risks include unclear legal rights, privacy leakage, faulty smart-contract logic, weak key management, concentration among infrastructure providers, interoperability failures, settlement-asset risk, operational outages, and controls that do not cover the boundary between on-chain and off-chain activity.
When should a finance team avoid blockchain?
Avoid it when one trusted party can operate a conventional database efficiently, when participants do not need a shared state, when legal finality is unclear, or when the network cannot meet privacy, resilience, governance, and integration requirements. A specific business problem should justify the architecture.