Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Hedge Fund vs Mutual Fund Differences
Hedge fund vs mutual fund is mainly a comparison of legal structure, investor access, strategy freedom, disclosure, fees, and liquidity. A mutual fund is generally a registered open-end investment company sold broadly to the public. A hedge fund is a private pooled investment fund whose offering terms and eligibility rules limit who can participate.
Both pool capital and use professional managers, but they are not interchangeable. Mutual funds operate within a public-investor framework and usually allow redemption at the next calculated net asset value on a business day. Hedge funds can use more flexible strategies and negotiate less frequent redemption terms, which can increase both opportunity and risk.
This page is educational, not individualized investment, legal, or tax advice. A fund’s current prospectus, offering memorandum, governing documents, and audited information matter more than a category label.
In this guide:
- What is the difference between a hedge fund and a mutual fund?
- What is a mutual fund?
- What is a hedge fund?
- How do hedge funds and mutual funds compare?
- Which is better for an investor?
- What should you check before investing?
- How do fund operations differ?
- Frequently asked questions
What is the difference between a hedge fund and a mutual fund?
The defining difference is not that one is active and the other is passive. It is the structure through which the fund is offered and governed. Mutual funds may be actively managed or index based. Hedge funds may follow many different strategies, from concentrated equity to relative value, macro, event driven, or market neutral approaches.
| Dimension | Mutual fund | Hedge fund |
|---|---|---|
| Offering structure | Registered open-end investment company | Private pooled investment fund |
| Typical investor access | Broad public access, subject to the fund and account provider | Limited by the offering structure and investor qualification rules |
| Strategy range | Bound by the stated objective, policies, and registered-fund rules | Often more flexible, including leverage, short selling, derivatives, and less liquid assets |
| Liquidity | Shares generally redeem at the next calculated NAV on a business day | Redemption windows, notice periods, gates, and lockups can apply |
| Disclosure | Prospectus, shareholder reports, and other public filings | Offering and investor reporting terms are largely set by private documents and applicable law |
| Fees | Operating expenses and any shareholder fees are disclosed in a standardized prospectus table | May combine management, performance, fund, and redemption-related charges |
| Primary question | Does this registered fund fit the investor’s goal, cost, and risk needs? | Does this specific private fund justify its complexity, risk, fees, and liquidity limits? |
The table describes common U.S. structures, not every fund in every jurisdiction. Always identify the exact vehicle, manager, share class, and governing documents before drawing conclusions.
What is a mutual fund?
A mutual fund pools money from investors and invests it in a portfolio of securities or other assets. Each share represents an investor’s proportionate interest in the portfolio. The Investor.gov mutual fund guide explains that U.S. mutual funds are SEC-registered open-end investment companies and that investors buy and redeem shares through the fund or an investment professional.
A mutual fund may track an index or use active management. Its prospectus defines the objective, strategy, principal risks, fees, purchase and redemption rules, and other material information. Diversification is common, but a narrowly focused fund can still be concentrated in one sector, asset class, or theme.
How mutual funds work
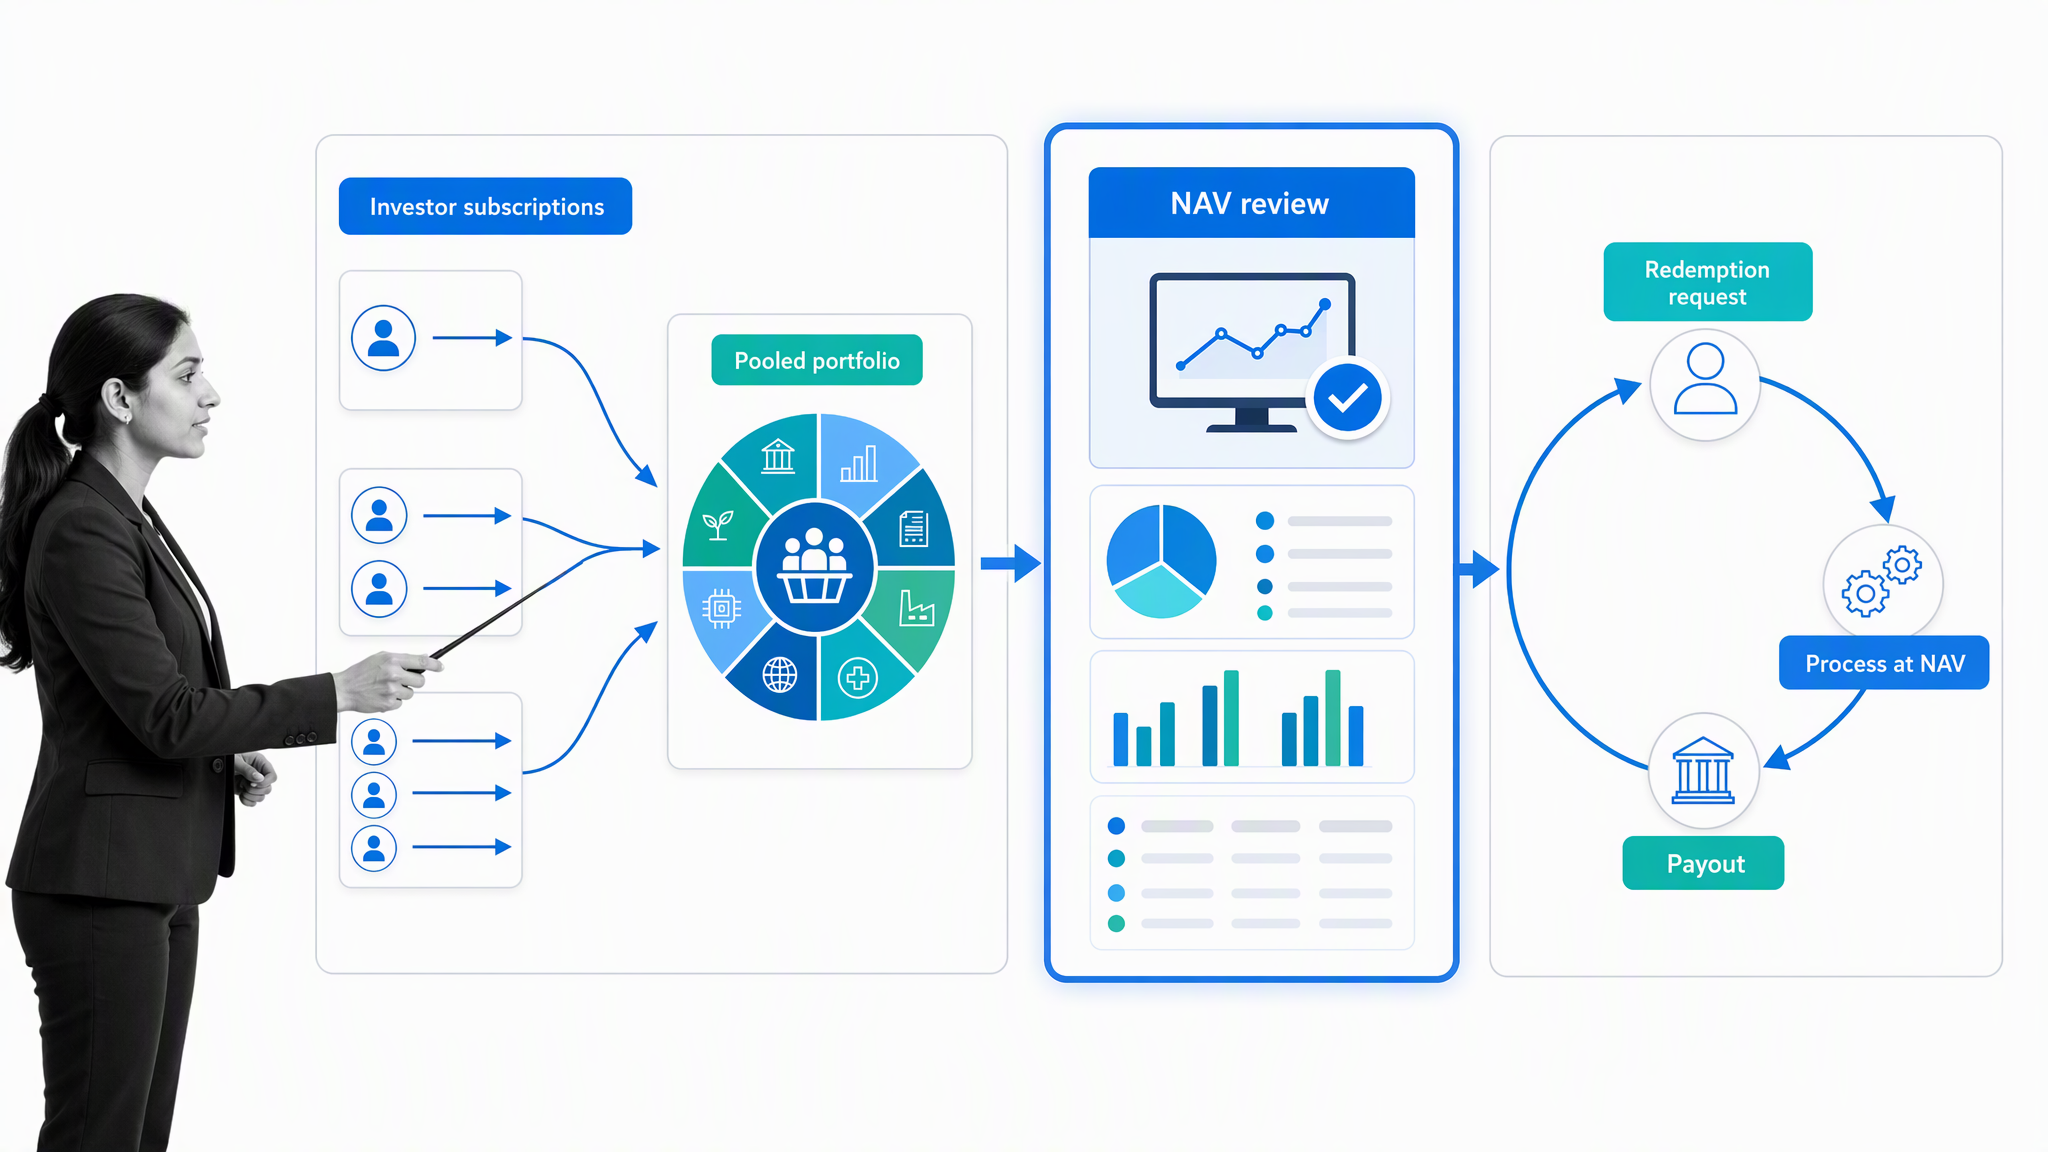
Investor money enters a shared portfolio. The adviser invests within the fund’s mandate, the fund calculates net asset value, and shareholder activity is processed under the fund’s purchase and redemption rules. Operations teams support valuation, reconciliations, compliance, shareholder records, disclosures, and reporting.
The key benefit is standardized access to a professionally managed portfolio. The tradeoff is that the investor accepts the fund’s mandate, expenses, tax consequences, and market risk. A familiar structure does not remove the need to understand what the fund owns.
What is a hedge fund?
A hedge fund is a private pooled investment fund. The name does not mean every fund is hedged or low risk. The Investor.gov hedge fund guide notes that these funds generally have more strategy flexibility than registered mutual funds and may use leverage, short selling, derivatives, and other speculative practices.
The fund’s partnership or other governing documents define the strategy, valuation process, fees, withdrawal rights, conflict terms, and manager authority. The category is broad, so two hedge funds can have very different risk, liquidity, and return profiles.
How hedge funds work
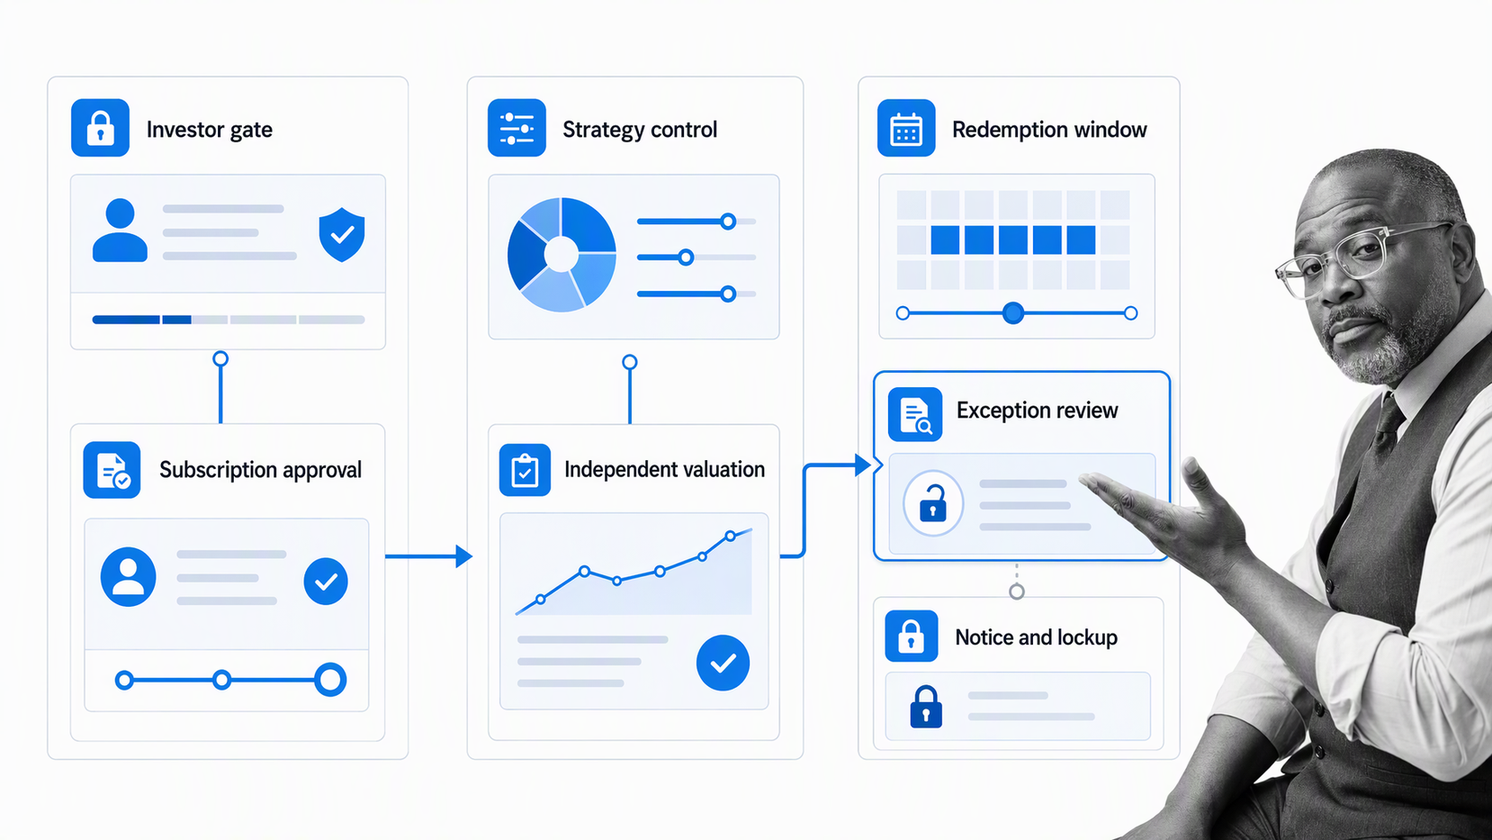
Eligible investors subscribe under private offering documents and commit capital to a strategy managed within those terms. The manager may have wider discretion over instruments, concentration, leverage, and liquidity. Fund administrators, auditors, prime brokers, custodians, legal counsel, and other service providers may support the operating model, depending on the fund.
Investor access can be limited, and withdrawals may be available only at specified intervals. Notice periods, gates, side pockets, lockups, or suspension rights can affect when capital is returned. Those terms need to be understood before subscription, not after a redemption request.
How do hedge funds and mutual funds compare?
Investor access and eligibility
Mutual funds are generally designed for broad public access. Hedge-fund eligibility depends on the offering structure and may require accredited-investor, qualified-purchaser, or other qualifications. The SEC’s accredited investor bulletin explains that certain private offerings are limited to investors who meet financial or professional criteria and may not provide the prescribed disclosures required in a registered offering.
Regulation and disclosure
It is inaccurate to say hedge funds are unregulated. They operate under a different framework from registered mutual funds. Mutual funds follow registered-investment-company rules on areas such as disclosure, valuation, liquidity, conflicts, custody, and leverage. Hedge funds rely on private-fund exemptions and remain subject to securities laws, antifraud rules, contractual duties, and rules that may apply to the manager or offering.
Strategy and risk
Mutual funds can be passive or active, but the strategy must fit the disclosed mandate and registered-fund rules. Hedge funds often have more room to use leverage, short positions, derivatives, concentrated exposures, and less liquid assets. Greater flexibility is not the same as better performance. It creates a wider range of possible outcomes and makes manager, process, valuation, liquidity, and counterparty due diligence especially important.
Fees and expenses
Mutual-fund costs vary by fund and share class. The SEC fee bulletin explains that prospectuses use a standardized table for annual operating expenses and shareholder fees. Hedge-fund terms may include management fees, performance-based compensation, fund expenses, and redemption-related charges. Compare the actual documents rather than relying on an industry slogan.
Liquidity and valuation
Mutual-fund investors generally redeem at the next calculated NAV on a business day, subject to the fund’s terms. Hedge funds may offer monthly, quarterly, or less frequent windows and may require advance notice. Less liquid holdings can also make valuation more judgment dependent. Ask who values difficult assets, how often valuations occur, and what happens when markets are stressed.
Which is better for an investor?
The better fit depends on the specific fund and the investor. Mutual funds often suit investors who value broad access, standardized disclosure, regular liquidity, and a clear public mandate. A hedge fund may suit an eligible investor who understands the strategy, can accept limited liquidity, can evaluate private documents, and believes the potential role in the portfolio justifies the costs and complexity.
Do not choose by category prestige or return targets. Compare the investment objective, holdings, downside behavior, manager incentives, concentration, leverage, liquidity, valuation, service providers, conflicts, fees, taxes, and reporting. Past performance cannot eliminate the risk of loss in either structure.
What should you check before investing?
A useful due-diligence checklist includes:
- Structure and eligibility: What legal vehicle is being offered, and are you eligible to invest?
- Objective and strategy: What is the fund trying to achieve, and what instruments or techniques can it use?
- Risk and loss scenarios: What could cause permanent loss, a margin call, forced selling, or a long recovery?
- Liquidity: When can you redeem, how much notice is required, and can withdrawals be gated or suspended?
- Valuation: Who prices difficult assets, how often, and what independent checks exist?
- Fees and incentives: Which costs are charged to the investor or fund, and how does compensation affect manager behavior?
- People and controls: Who manages the portfolio, who performs administration and custody, and what conflicts exist?
- Documents and reporting: Which prospectus, offering memorandum, audited statements, or regulatory filings should you review?
- Tax treatment: What forms and timing apply to your account and jurisdiction? Ask a qualified tax professional about your situation.
How do fund operations differ?
The investment structure changes the operating work. Mutual-fund teams manage recurring valuation, shareholder activity, reconciliations, portfolio compliance, disclosure, and reporting within a registered-fund environment. Hedge-fund teams manage private subscriptions, investor eligibility, capital activity, strategy-specific controls, valuation, administrator handoffs, side-letter obligations, and redemption terms.
Process Street can coordinate that repeatable work without replacing portfolio, accounting, transfer-agency, administration, or market systems. A process platform turns procedures into assigned workflows with required fields, conditional routes, approvals, evidence, due dates, and an audit history. The record shows who completed each step, what was reviewed, and how an exception was resolved.
Teams can apply that control layer to investor onboarding, periodic reviews, NAV close checklists, disclosure approvals, due diligence, service-provider oversight, and exception handling. See the dedicated hedge fund system and mutual fund management software guides for operational examples.
Frequently asked questions
What is the main difference between a hedge fund and a mutual fund?
A mutual fund is generally an SEC-registered open-end investment company offered broadly to investors. A hedge fund is a private pooled investment fund offered under different rules to investors who meet the fund’s eligibility requirements. That structural difference affects disclosure, strategy flexibility, fees, and redemption terms.
Can anyone invest in a hedge fund?
No. Depending on the fund and offering structure, investors may need to qualify as accredited investors, qualified purchasers, or under another applicable standard. Eligibility does not make an investment suitable, so investors still need to evaluate the strategy, fees, liquidity, conflicts, and risk of loss.
Are mutual funds safer than hedge funds?
Not automatically. Mutual funds operate under a regulatory framework designed for public investors and usually provide daily redemption at the next calculated net asset value. Their underlying investments can still lose value. Hedge-fund risk varies widely by strategy, leverage, concentration, valuation, and liquidity terms.
Do all hedge funds charge 2 and 20?
No. Hedge-fund fee arrangements vary. Some use both an asset-based management fee and a performance allocation or incentive fee, while others use different terms. Investors should read the offering documents and understand hurdles, high-water marks, expenses, and redemption charges.
Can mutual funds use active strategies?
Yes. Mutual funds can be actively managed or index based. An actively managed fund selects investments to pursue its stated objective, while an index fund seeks to track a selected benchmark before fees. The prospectus explains the fund’s objective, strategy, risks, and costs.
Which is better, a hedge fund or a mutual fund?
Neither is universally better. The answer depends on eligibility, financial goals, risk capacity, liquidity needs, time horizon, costs, tax circumstances, and the specific fund. Compare actual documents and consider qualified financial, legal, and tax advice before investing.