


Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


How to Make a Private Equity Investor Pitch Deck
A private equity investor pitch deck has one job: help an investment team decide whether your company deserves deeper diligence. It is not a startup vision deck with a few financial slides added at the end. It is a compact investment case built from operating evidence, financial performance, a credible value-creation plan, and a clear transaction objective.
The strongest deck lets an investor answer four questions quickly: What is the business today? Why is it defensible? What can improve under new ownership or with new capital? What could prevent the plan from working? This guide shows how to build that case, slide by slide, and how to connect the presentation to the diligence process that follows.
Important: This is a practical content framework, not legal, tax, accounting, or investment advice. Work with qualified advisers on offering rules, performance presentation, valuation, and transaction terms.
In this guide
- What is a private equity investor pitch deck?
- How is a private equity pitch deck different from a VC deck?
- What does a private equity investor need to believe?
- How do you build the investment case before designing slides?
- What slides should a private equity investor pitch deck include?
- How should the deck prepare investors for due diligence?
- How do you review the deck before sharing it?
- How should you present the deck?
- How can Process Street support the pitch and diligence process?
- Private equity investor pitch deck FAQs
What is a private equity investor pitch deck?
A private equity investor pitch deck is a presentation used by a company, owner, or adviser to explain an investment opportunity to a private equity firm. It usually supports a growth-equity raise, recapitalization, partial liquidity event, or control transaction. The deck introduces the business and frames the reasons an investor should spend time and resources on diligence.
The deck is not the entire transaction record. It sits at the front of a larger evidence set that may include audited or reviewed financial statements, customer and product data, a management forecast, legal records, operating metrics, and a virtual data room. The presentation should make that evidence easier to evaluate, not replace it.
That distinction matters because private investments can involve limited public disclosure and illiquidity. The SEC’s investor education guidance notes that investors need enough information to evaluate the issuer, its financial statements, management, competition, intended use of funds, and material risks. Review the Investor.gov private placements bulletin with counsel when planning what the deck and related materials should disclose.
How is a private equity pitch deck different from a VC deck?
A venture deck can lead with a large future market, a product insight, and evidence that a young company is learning quickly. A private equity deck usually begins with the business as it operates now. It must show a reliable earnings engine, a defensible market position, management depth, cash needs, risks, and specific levers that can create value.
| Question | VC-style emphasis | Private equity emphasis |
|---|---|---|
| What exists today? | Product, early traction, learning velocity | Operating model, financial history, customer quality |
| Why invest? | Potential to create a large new category | Evidence that the business can compound value |
| What changes after investment? | Hiring, product expansion, market capture | Operational improvement, growth initiatives, governance, and capital structure |
| What proof matters? | Adoption, engagement, growth signals | Earnings quality, cash flow, retention, margins, and repeatable execution |
| What follows the meeting? | More partner conversations and targeted diligence | Structured commercial, financial, legal, tax, and operational diligence |
The right emphasis depends on the deal. A minority growth investment may give more space to expansion and reinvestment. A control deal may require a stronger treatment of management continuity, working capital, debt capacity, integration opportunities, and ownership transition. State the transaction objective early so the investor can interpret every later slide in the right context.
What does a private equity investor need to believe?
Your deck should build a chain of belief rather than a collection of attractive slides. Each claim should connect to evidence, and each section should reduce a specific investment uncertainty.
The business is understandable
An investor should be able to explain what the company sells, who buys it, why customers stay, how revenue is generated, and where profit is created. If the model requires several slides of vocabulary before the economics make sense, simplify the explanation.
The performance is real
Use reconciled figures and consistent definitions. Separate reported results from management adjustments. Show what changed, why it changed, and whether the driver is repeatable. If a metric cannot be traced to a source file, do not feature it as a headline proof point.
The upside has named owners
A value-creation plan is stronger when it names the initiative, baseline, expected mechanism, dependencies, owner, timing, investment required, and leading indicator. “Expand internationally” is an ambition. “Launch the existing enterprise offer in two validated markets under the current sales leader, with localized channel partners and a staged hiring gate” is an operating plan.
The risks are known and managed
Good decks do not hide concentration, cyclicality, regulatory exposure, key-person dependency, or technical debt. They quantify material risks where possible and explain the controls, mitigations, and decisions already in motion. A balanced risk slide improves credibility because it shows that management understands the investment from the buyer’s side of the table.
How do you build the investment case before designing slides?
Define the audience and transaction
Identify the likely investor type, sector focus, check profile, ownership preference, value-creation capabilities, and decision process. Then write a one-sentence transaction objective. This prevents a broad company overview from drifting into a generic fundraising presentation.
Build an evidence ledger
Create a table with one row for every material assertion. Record the claim, definition, source file, owner, reporting period, reviewer, and deck location. This forces the team to resolve conflicting metric definitions before an investor discovers them.
Write the investment thesis in plain language
Summarize the case in a short paragraph: the quality of the current business, the reason the opportunity exists now, the most credible value levers, and the main risk. If the thesis depends on several unrelated “and” statements, the story probably needs a tighter hierarchy.
Separate base case from upside
Show what the business can deliver through current operations, then identify initiatives that could improve the outcome. Investors should not have to reverse-engineer which forecast assumptions are already proven and which require new capital, new leadership, acquisitions, or execution that has not started.
What slides should a private equity investor pitch deck include?
Use the sequence below as a decision framework, not a rigid template. Some topics need more than one slide, while a simple business may combine several. The goal is to move from “what is this?” to “why could this be a good investment?” without forcing the investor to hunt for proof.
1. Cover and transaction context
State the company name, the nature of the opportunity, the date, and appropriate confidentiality language. If the process has a code name, make the company identity and sector clear enough that the opening is still useful.
2. Executive investment thesis
Present the strongest reasons to continue, supported by a small number of verified operating and financial facts. Include the transaction objective and the most important risk or dependency. This slide should frame the rest of the deck, not summarize every slide.
3. Financial performance
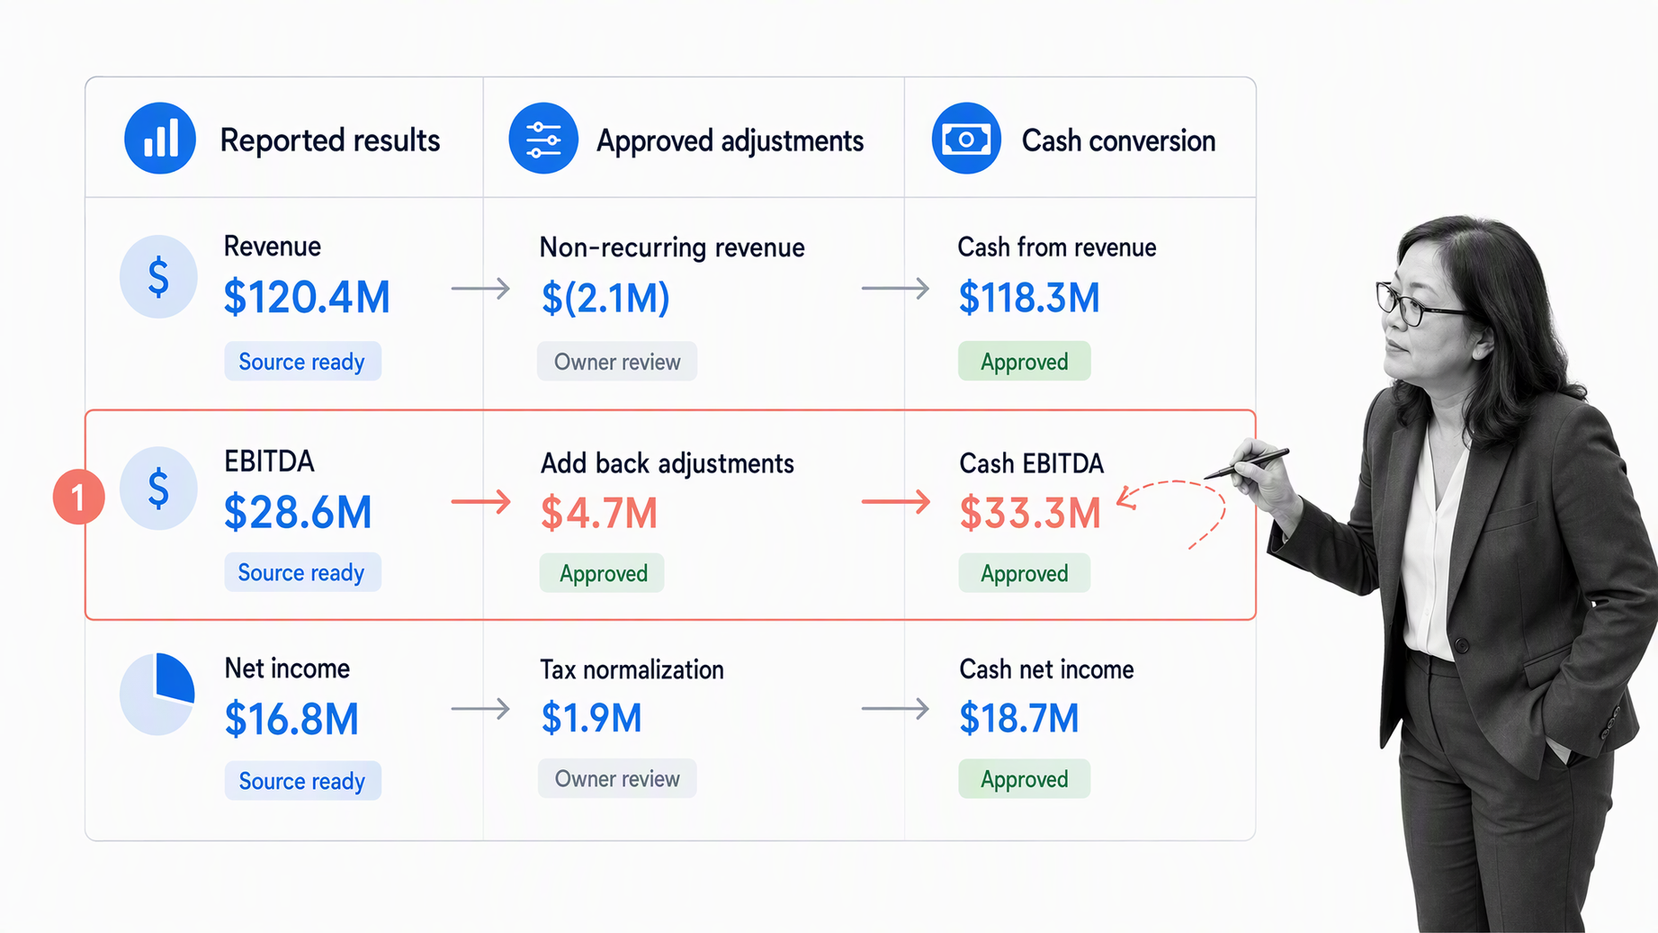
Show revenue, gross profit, operating profit or EBITDA where appropriate, cash conversion, working-capital behavior, and the drivers behind changes. Make definitions and adjustments visible. Use consistent periods and connect the headline figures to supporting schedules.
4. Business model and revenue quality
Explain pricing, contract structure, customer concentration, retention, recurring versus project revenue, sales cycle, and unit economics that matter for the model. Choose measures that describe economic quality, not metrics that merely look impressive.
5. Value-creation plan
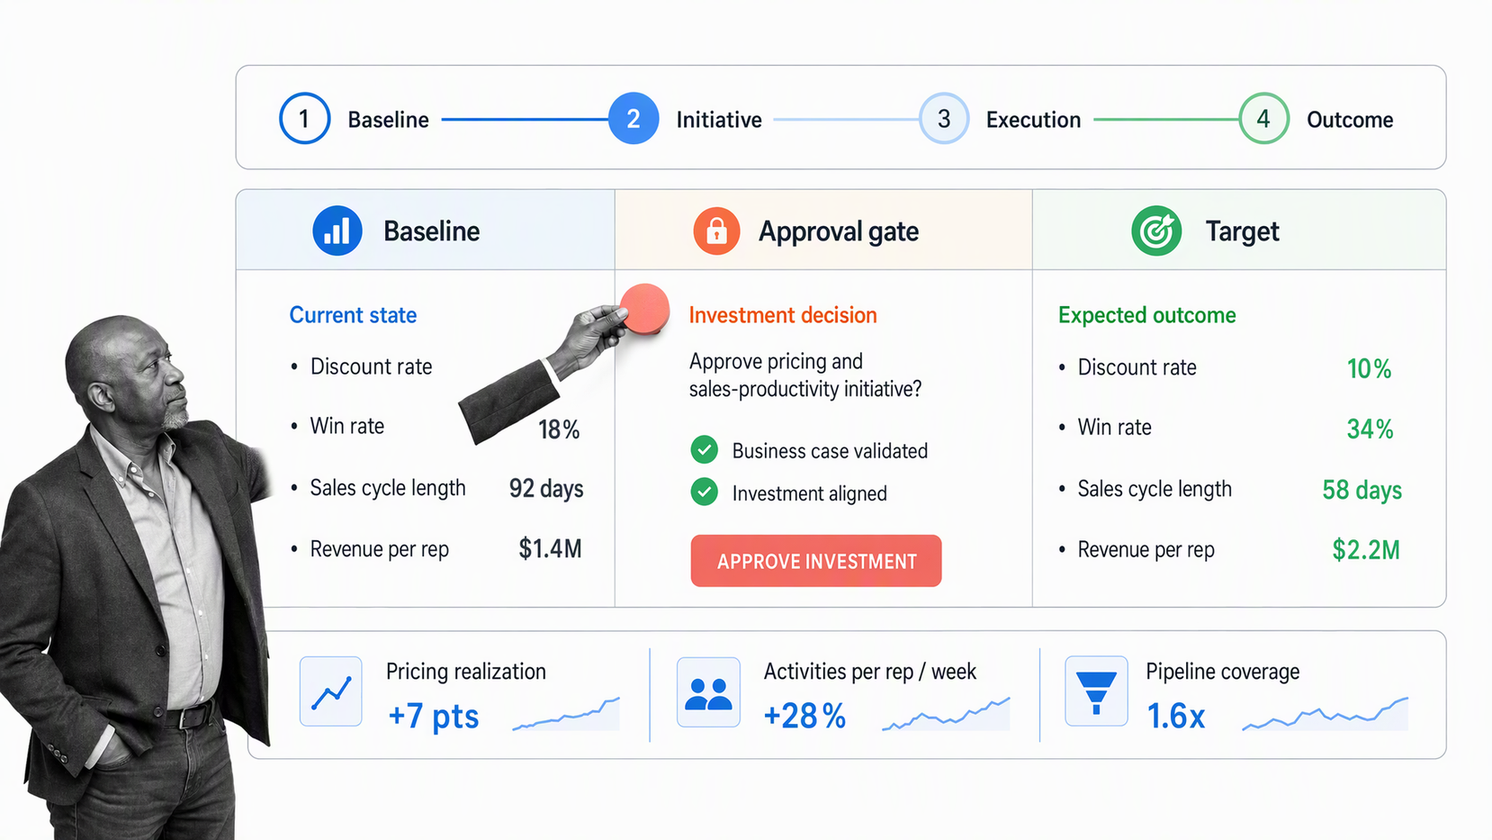
Organize the plan around a few executable levers, such as pricing discipline, sales productivity, product expansion, procurement, working capital, capacity utilization, or selected acquisitions. For each lever, show the baseline, mechanism, owner, required investment, dependency, and leading indicator.
6. Market and competitive position
Define the addressable segment in a way that matches the company’s real sales motion. Explain customer alternatives, switching behavior, differentiation, and market risks. Avoid a huge market number that cannot be linked to an achievable route to customers.
7. Transaction structure and use of proceeds
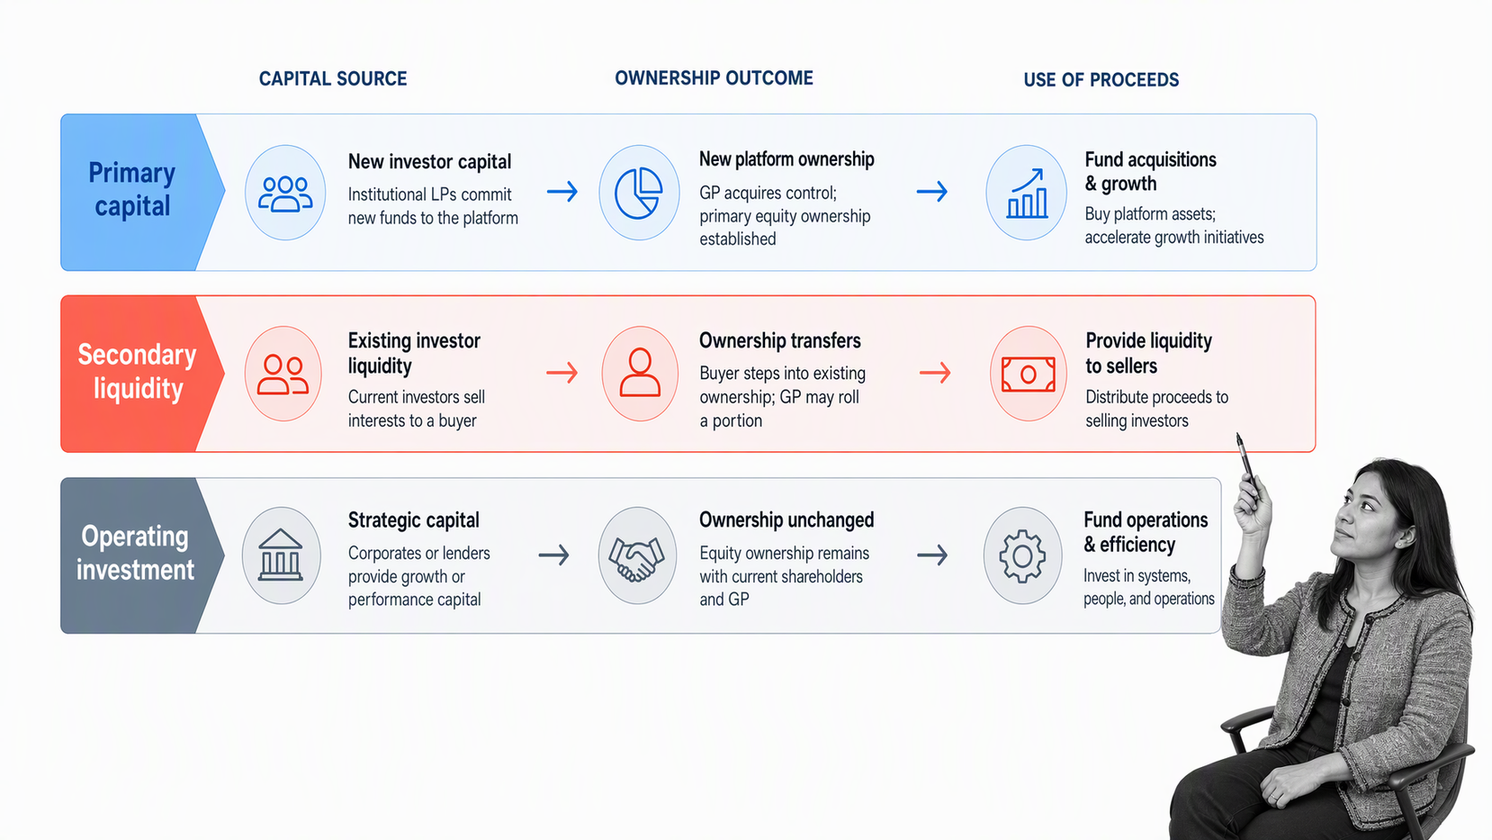
Explain whether the objective is growth capital, primary capital, secondary liquidity, a recapitalization, or a control transaction. Show how proceeds would be used, what ownership outcome management seeks, and which elements remain open for discussion. Counsel should review all offering and solicitation language.
8. Management team and operating depth
Focus on the experience most relevant to the plan. Show responsibilities, decision rights, succession depth, open leadership gaps, and the management team’s willingness to remain invested. A page of biographies is less useful than evidence that the team can execute the next phase.
9. Forecast and assumptions
Present the forecast with the operating assumptions that drive it. Show how volume, price, retention, margin, headcount, capital expenditure, and working capital affect the outcome. Include sensitivities where one assumption materially changes the case.
10. Risks and mitigations
Rank risks by materiality and connect each to an owner and response. Consider customer and supplier concentration, regulation, litigation, cybersecurity, technology, leadership dependence, debt, cyclicality, and execution risk. Do not bury known issues in an appendix.
11. Diligence readiness and next steps
Close with the process: who owns follow-up, which materials are available, what requires an NDA, how management meetings will work, and when the next decision point occurs. A clean handoff signals that the team can run a disciplined transaction process.
How should the deck prepare investors for due diligence?
The deck should act as an index to proof. Every major chart, adjustment, customer metric, and forecast assumption should map to a named source that the team can produce under the correct access controls. Build that map while writing the deck, not after an investor sends the first request list.
Run a pre-pitch evidence review
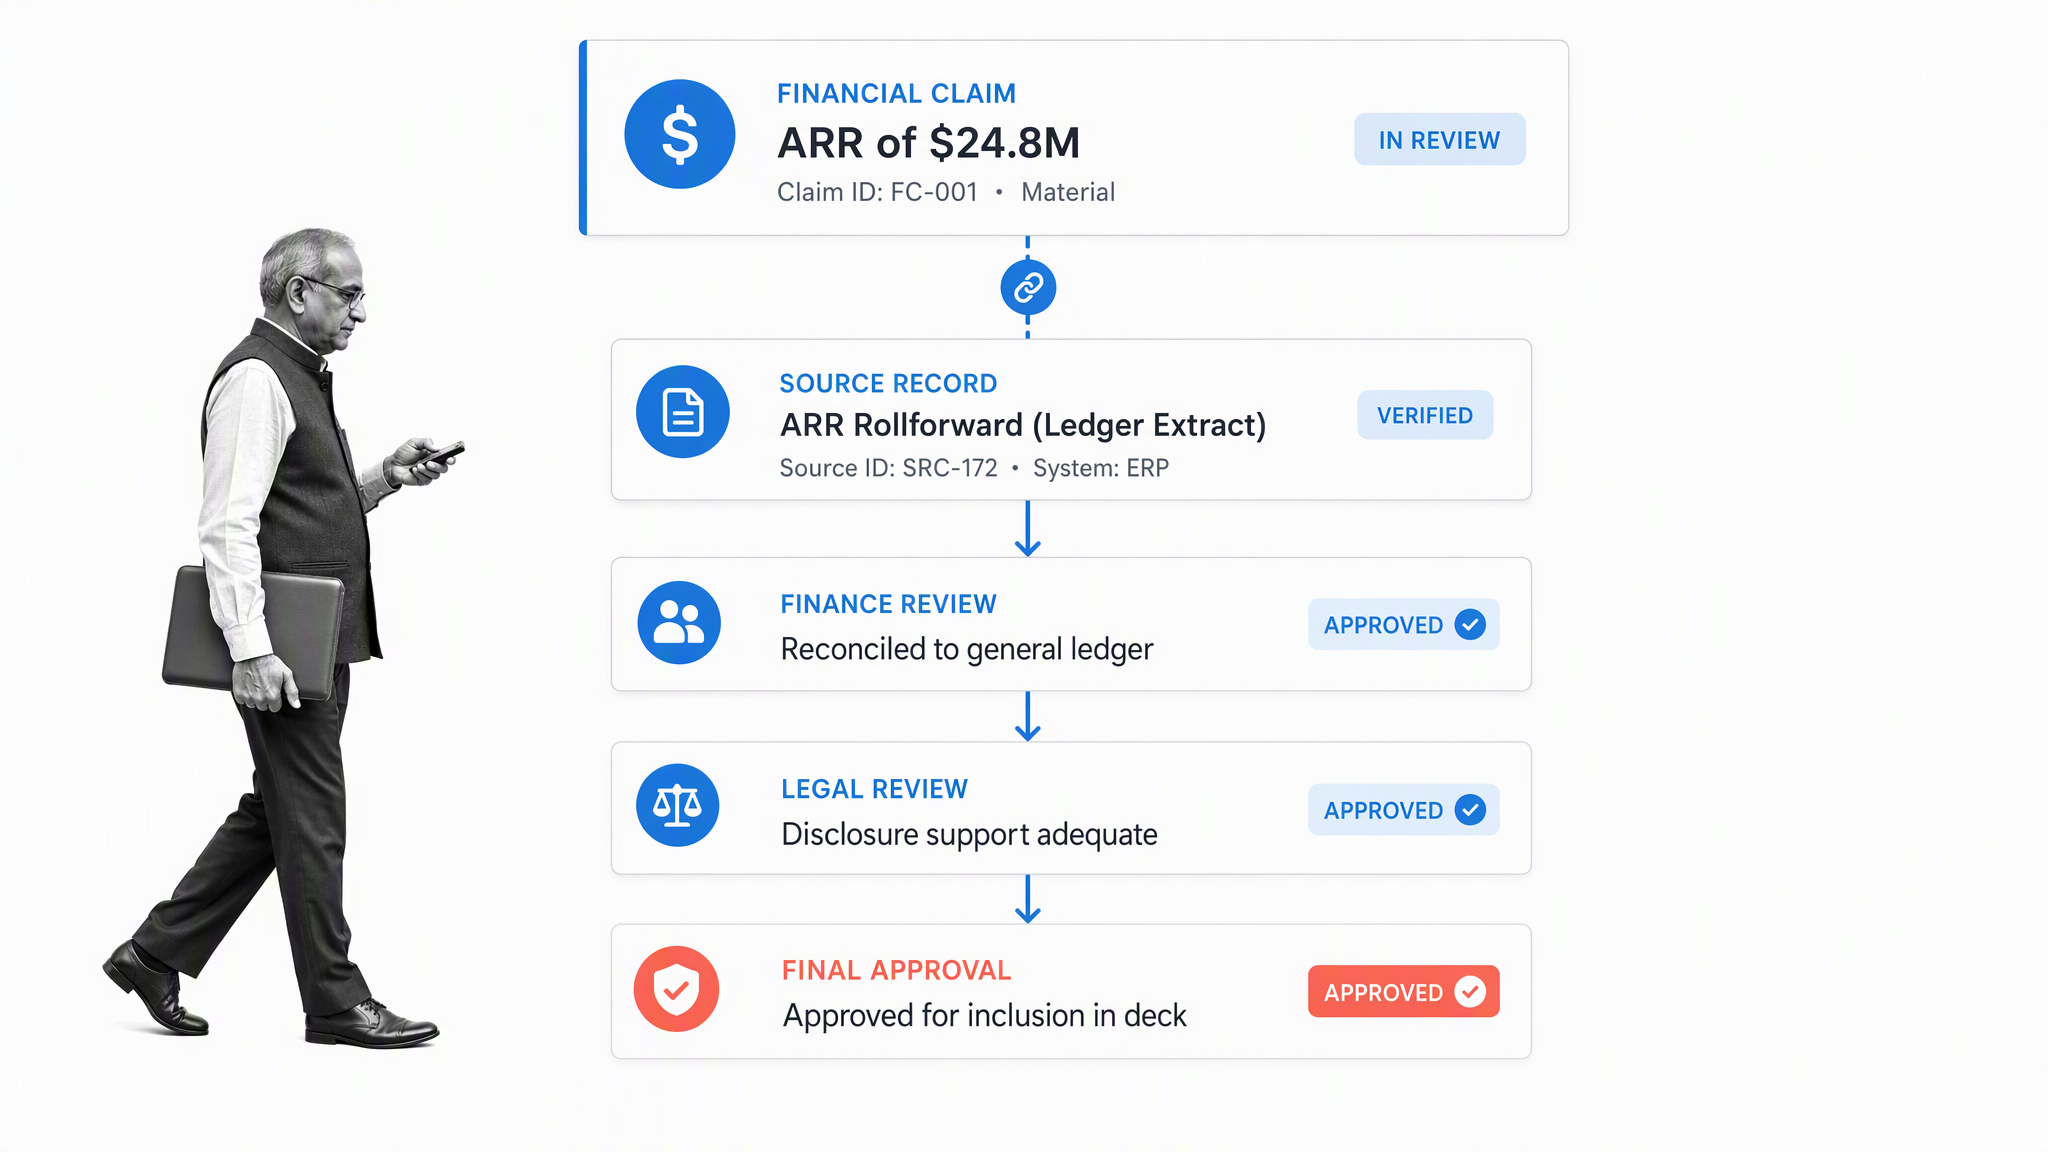
- Reconcile deck figures to financial statements and management reports.
- Define every nonstandard metric and adjustment.
- Confirm that customer, pipeline, and retention data use consistent time periods.
- Check that management biographies and ownership information are current.
- Have legal and compliance reviewers examine solicitation, confidentiality, and performance language.
- Record who approved each material claim and when.
Prepare the data room around investor questions
Organize materials by the questions an investor must answer: financial quality, commercial strength, legal ownership, tax exposure, technology resilience, people, compliance, and value-creation feasibility. A private equity due diligence checklist can help the team assign evidence owners and track missing materials before the process becomes time-sensitive.
If the pitch is for a private equity fund raising capital from limited partners, the diligence package is different from a company sale or growth-capital process. The Investor.gov private equity fund overview explains that investors generally receive offering documents and enter agreements as limited partners. Offering and solicitation rules also depend on the exemption and audience. Review the Investor.gov Rule 506 overview with counsel before distributing materials or presenting performance claims.
How do you review the deck before sharing it?
Run separate reviews for substance, consistency, and communication. The substance review asks whether the investment case is supported. The consistency review checks the deck against the operating model, financial schedules, data room, and management talking points. The communication review removes clutter and makes the decision path clear. Combining all three into one meeting usually leads to cosmetic edits while material questions remain unresolved.
Use a red-team review
Ask a reviewer who did not build the deck to challenge the thesis as an investment committee would. Which assumption is doing too much work? Which chart could be interpreted differently? Where does the story move from evidence to aspiration? What would make the deal unattractive? Record each challenge, assign an owner, and decide whether the answer belongs in the deck, appendix, data room, or live discussion.
Control the final version
Set one owner for the master file and one approval path for changes. Freeze metric definitions before final design. Confirm confidentiality markings, file permissions, links, appendix references, and contact details. Create a distribution log so the team knows which version each investor received and can keep follow-up answers consistent with that version.
How should you present the deck?
Lead with the decision, then show the proof
Do not read the deck aloud. State the investment thesis, then use each slide to answer the next likely question. Move detail into an appendix when it supports a claim but interrupts the main decision path.
Give bad news a clear owner
If performance missed plan, explain the cause, response, owner, and evidence that the response is working. Evasive answers damage confidence more than a well-understood problem with a credible corrective plan.
Rehearse the handoffs
Assign each topic to the executive who owns it. Rehearse transitions, likely challenges, and the boundary between an answer you can give in the room and a fact that needs verification. Capture unanswered questions in one follow-up queue with an owner and approval step.
How can Process Street support the pitch and diligence process?
A pitch deck is a deliverable, but investor readiness is a process. Process Street for private equity turns that process into a structured workflow with assigned owners, due dates, approvals, and a record of completed work.
Teams can route financial claims to finance, transaction language to counsel, market evidence to commercial owners, and final slides to executive approval. The same workflow can track data-room readiness, investor questions, management-meeting preparation, and follow-up. That creates one controlled path from the first evidence request to the final approved deck.
The Tribe Capital case study shows how structured workflows can connect pitch materials, financials, deal memos, approvals, and closing activities. The lesson for a fundraising team is simple: the presentation becomes more credible when the operating process behind it is equally disciplined.
Build a repeatable private equity pitch and diligence workflow with Process Street.
Private equity investor pitch deck FAQs
What should a private equity investor pitch deck include?
Include the transaction context, investment thesis, financial performance, business model, revenue quality, value-creation plan, market position, management team, transaction structure, forecast assumptions, material risks, and diligence next steps. Every major claim should map to a source that can be produced during diligence.
How is a private equity pitch deck different from a startup pitch deck?
A startup deck may emphasize vision, product discovery, and future market potential. A private equity deck usually emphasizes the operating business as it exists today, including financial quality, cash generation, management depth, risks, transaction goals, and specific levers for creating value.
How long should a private equity investor pitch deck be?
Use enough slides to present the investment case clearly, but keep the main deck focused on the decision. Put detailed schedules, cohort tables, customer analyses, and methodology notes in an appendix or controlled data room. The right length depends on the business and transaction, not a universal slide count.
What financial information belongs in a PE pitch deck?
Show the financial measures that explain economic quality: revenue and gross profit, operating profit or EBITDA where appropriate, cash conversion, working capital, customer concentration, recurring revenue quality, and forecast drivers. Define adjustments and reconcile the presentation to source records.
Should a private equity pitch deck disclose risks?
Yes. Present material risks in a balanced way and explain their likely impact, owner, mitigation, and monitoring approach. Counsel should determine what the transaction materials must disclose. Hiding a known issue can damage trust and create problems later in diligence.
How do you keep pitch deck claims consistent during due diligence?
Maintain an evidence ledger that records each claim, definition, source file, reporting period, owner, reviewer, and slide location. Route changes through approval and use the same definitions in the deck, management model, data room, and follow-up answers.
