Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Financial Process Automation: A Practical Guide
Financial process automation turns recurring finance procedures into controlled workflows. Instead of moving invoices, approvals, reconciliations, close tasks, and audit evidence through email and spreadsheets, the process defines what happens next, who owns it, which rules apply, and what proof must be retained.
The aim is not to remove finance professionals from financial decisions. It is to remove preventable coordination work, apply controls consistently, and direct human attention to exceptions. The accounting or ERP platform remains the financial system of record, while the workflow layer coordinates the work around it.
This guide explains where automation creates value, how to design it without weakening controls, where AI belongs, and how Process Street supports finance workflows from intake through evidence and review.
- What is financial process automation?
- Which financial processes can be automated?
- What are the benefits and risks?
- How do you automate a financial process?
- Where should AI fit?
- How does Process Street support finance automation?
- How should success be measured?
- How do you choose financial process automation software?
- Financial process automation FAQs
What is financial process automation?
Financial process automation is the use of workflow software, rules, integrations, and sometimes AI to coordinate repeatable finance work. A well-designed automated process accepts an input, validates required information, assigns responsibility, applies approval and exception rules, updates connected systems, and preserves a record of what happened.
This is broader than automating one task. Extracting fields from an invoice is task automation. A complete invoice workflow also checks for missing information, routes the invoice to the right cost center, applies approval thresholds, handles disputes, records the decision, prepares the item for payment, and confirms the final accounting outcome.
| Layer | What it does | Typical finance example |
|---|---|---|
| System of record | Stores authoritative transactions and balances | Accounting platform or ERP |
| Workflow layer | Coordinates people, rules, approvals, evidence, and exceptions | Invoice approval or close workflow |
| Automation layer | Moves data and triggers permitted actions between systems | Create a task when an invoice fails validation |
| Intelligence layer | Classifies, extracts, summarizes, or flags unusual cases | Identify a likely duplicate for review |
| Control layer | Restricts, verifies, and records consequential decisions | Separate preparation, approval, and release |
The layers should reinforce each other. When automation bypasses ownership, approvals, or evidence, it moves work faster but makes the process harder to trust. When the workflow is explicit, automation can make the control visible at the same moment it makes the task easier.
Which financial processes can be automated?
The strongest candidates are frequent, rules-based processes with stable inputs, repeated handoffs, and a clear finish line. Processes with judgment can still be automated, but the workflow should route judgment to an authorized person instead of pretending every case is deterministic.
Invoice intake and accounts payable
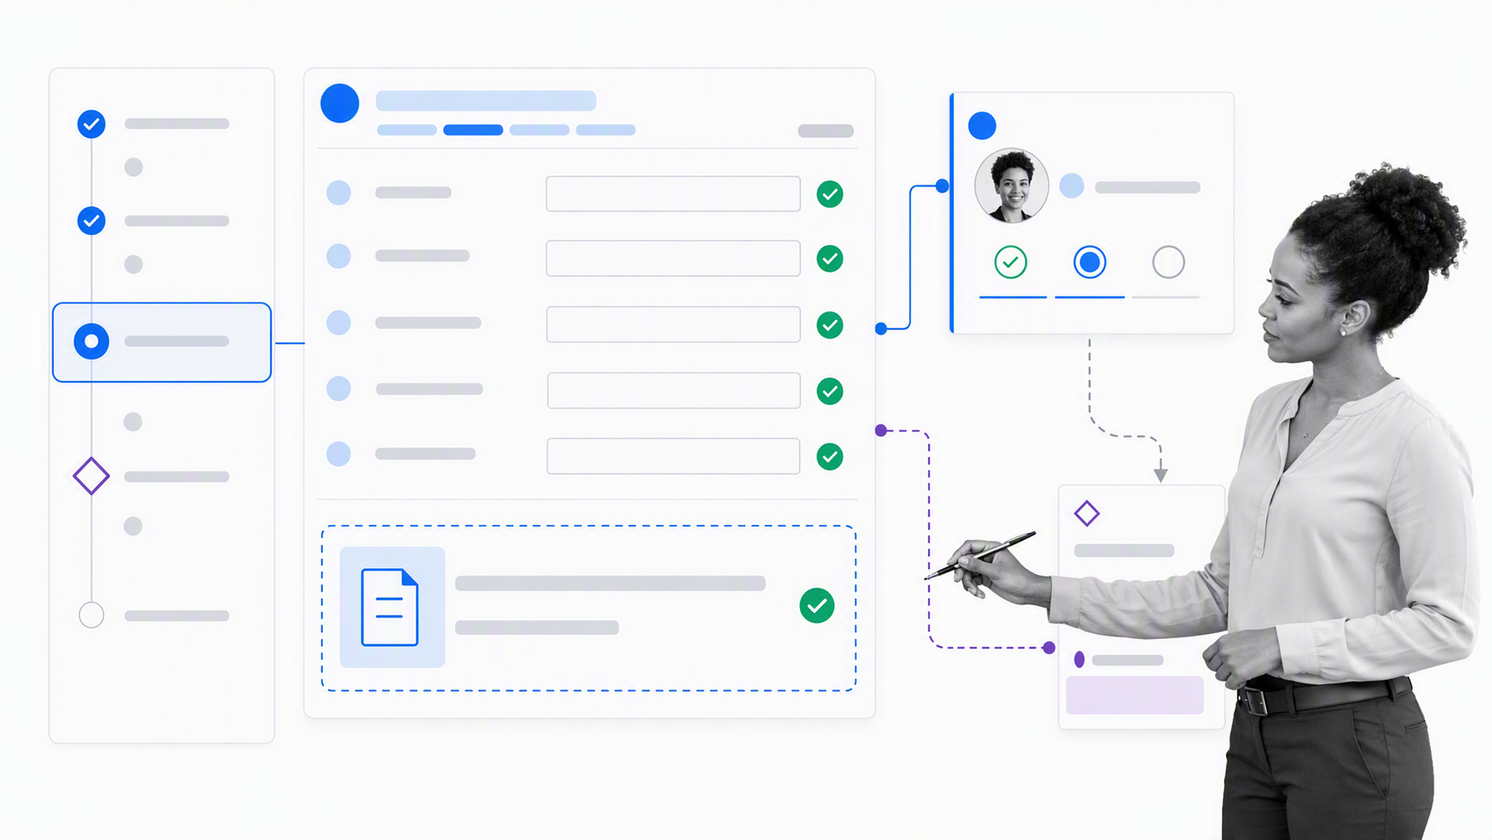
An accounts payable workflow can register an invoice, capture supplier and purchase context, check required fields, route coding, request approval, manage exceptions, prepare the item for payment, and confirm posting and reconciliation. The workflow should keep the invoice version, comments, decisions, and exception history connected.
Microsoft describes accounts payable as a business process area with direct control over each step, involving roles such as accounts payable specialists, financial analysts, controllers, and the CFO. That end-to-end view is more useful than treating invoice capture as the whole process. See the Microsoft accounts payable process overview.
- Invoice intake and duplicate checks
- Purchase order, receipt, and contract validation where applicable
- Coding and cost-center assignment
- Approval routing and escalation
- Exception, dispute, and hold management
- Payment readiness and final reconciliation
Expense and purchase approvals
Expense and purchase workflows can verify required documentation, apply policy rules, route requests by amount or category, and send unusual items to review. The important design choice is to separate a request from its authorization. A form submission should not become an approved commitment merely because every field is complete.
Use conditional paths for routine differences, such as department, entity, amount band, project, or expense type. Keep policy exceptions explicit, record who approved them, and avoid hiding overrides in chat. This gives finance a usable record without forcing every request through the same route.
Month-end close and reconciliation
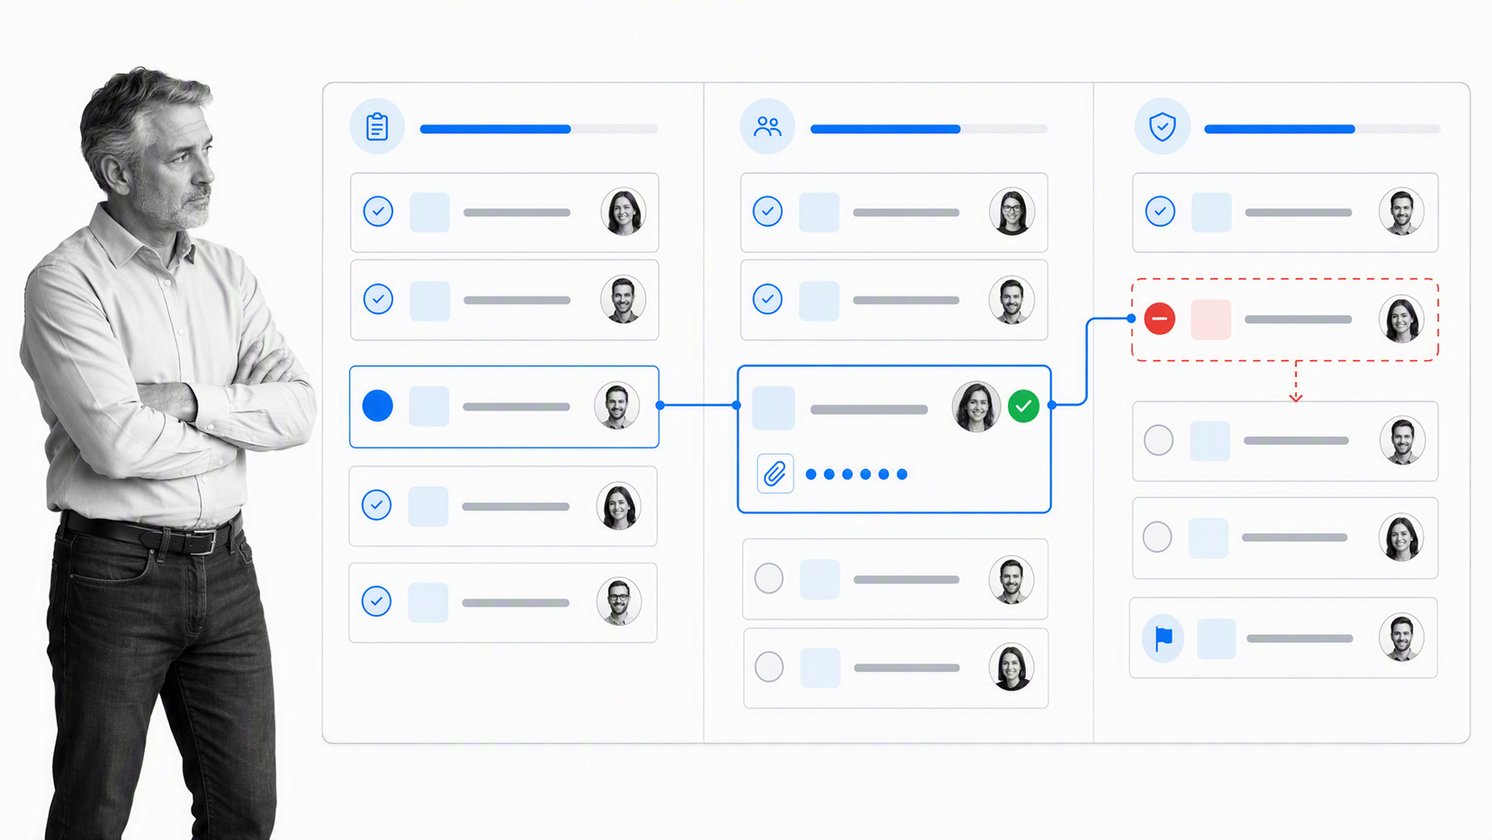
Close automation coordinates recurring tasks, dependencies, account reconciliations, journal preparation, reviews, confirmations, and variance follow-up. The workflow should show which tasks are ready, blocked, overdue, returned, or complete, and it should preserve the evidence used for each sign-off.
Reconciliation automation can prepare matches and surface differences, but the workflow still needs ownership for unexplained items, documentation for adjustments, reviewer sign-off, and confirmation that the authoritative ledger reflects the result. Closing a workflow before that confirmation creates false completion.
Controls and audit evidence
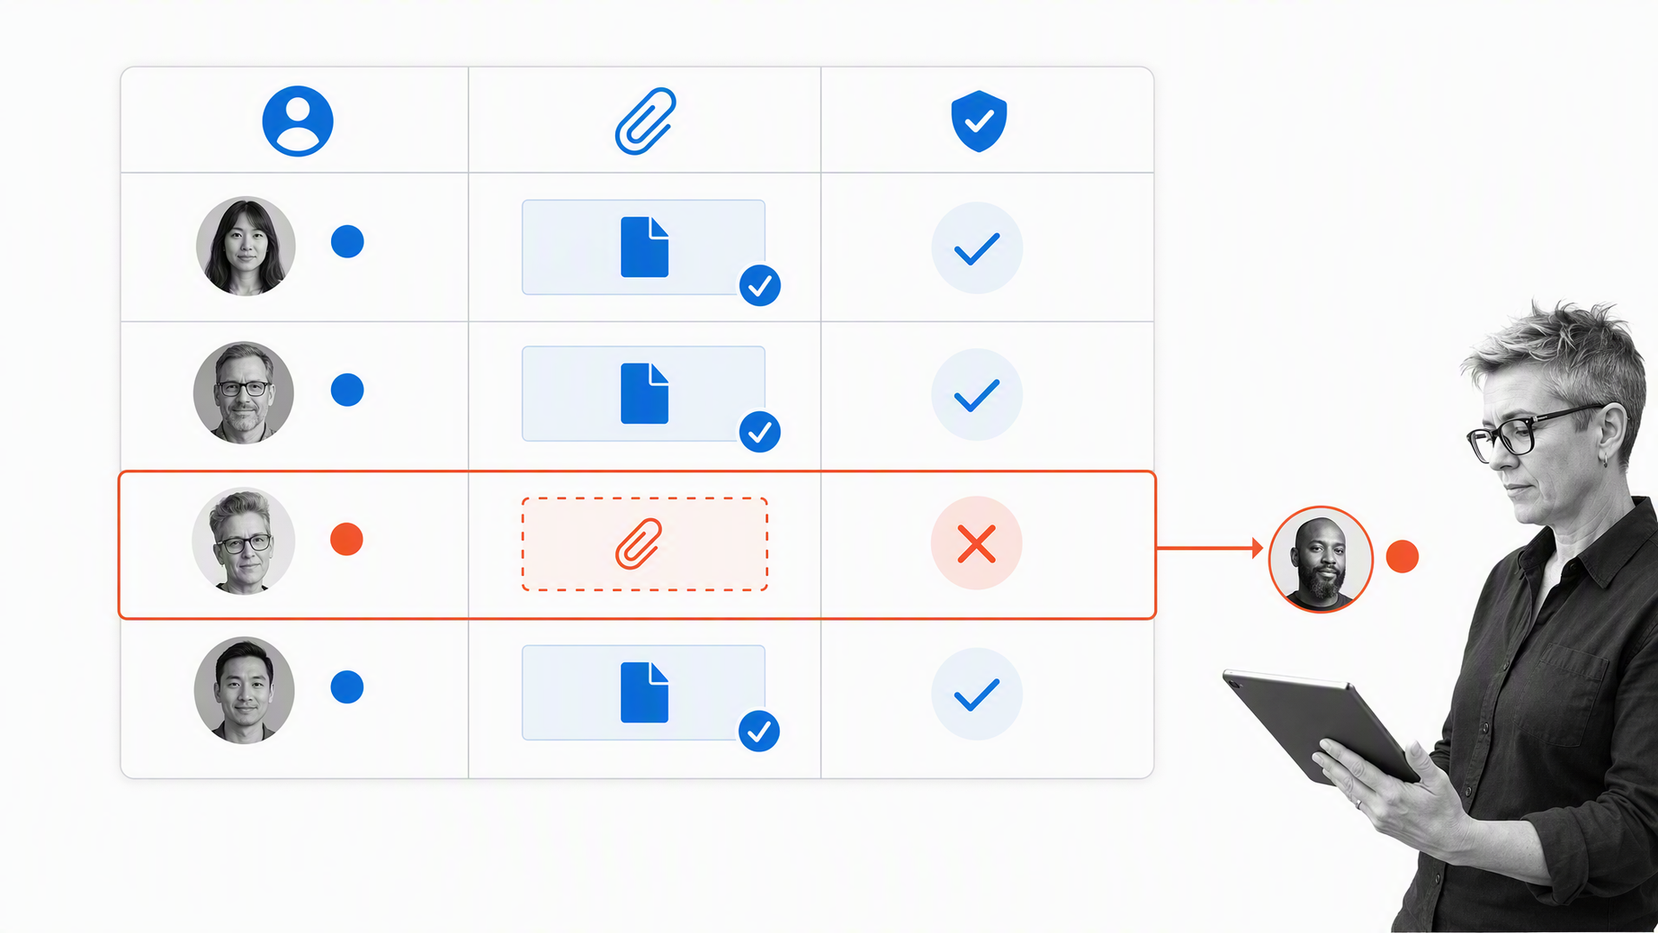
Recurring control work is a strong fit when the cadence, owner, evidence, and review criteria are defined. The workflow can schedule the control, request evidence, prevent completion when required fields are missing, route failures, and retain the execution record.
The IRS guidance for managing electronic records emphasizes documented system operations, associated controls, standardized retrieval, and protection against unauthorized change or deletion. Those principles are useful well beyond tax administration because they explain what makes digital evidence trustworthy. See the IRS electronic records guidance.
- Recurring account and control reviews
- Evidence requests and completeness checks
- Segregation-of-duties approvals
- Policy exception review
- Audit request intake and response
- Remediation verification and closure
What are the benefits and risks of financial process automation?
The practical benefits come from consistency and visibility. A workflow can reduce approval chasing, prevent work from disappearing between systems, make ownership clear, and give leaders a current view of exceptions. Standardized intake also makes downstream automation more reliable because the process starts with complete, structured information.
| Potential benefit | What creates it | Design risk to avoid |
|---|---|---|
| Faster cycle time | Automatic routing, reminders, and system actions | Rushing incomplete or disputed items |
| Fewer coordination errors | Required fields, ownership, and controlled handoffs | Assuming a completed form proves accuracy |
| Stronger visibility | Shared status, deadlines, and exception queues | Measuring task completion without the financial outcome |
| Better evidence | Decisions, attachments, timestamps, and review records | Storing copies without retention or access rules |
| More scalable operations | Reusable workflow logic and standardized execution | Automating a broken or unstable policy |
Automation can also amplify a bad rule, apply the wrong permissions at scale, or make an error harder to notice. A process owner must understand the source data, decision rights, exception path, change controls, and recovery plan before increasing the level of automation.
COSO addresses the governance challenge directly by connecting robotic process automation with the Internal Control Integrated Framework. The key lesson is that automation governance and internal control belong together. See COSO guidance on internal control over RPA.
How do you automate a financial process?
Start with the operating process, not the software. Choose one real workflow and follow it from trigger to verified outcome. Interview the people who prepare, approve, review, correct, and report the work. The visible happy path is usually simpler than the exceptions that consume the most time.
1. Map the current process and define ownership
Document the trigger, required inputs, systems, owners, decisions, controls, exceptions, evidence, and final system of record. Mark every handoff and every place where someone waits, rekeys information, asks for missing context, or reconciles two sources.
Give the process one accountable owner. Individual tasks can belong to AP, procurement, a budget owner, a controller, or IT, but someone must own the performance and integrity of the complete workflow. Without that ownership, local automations accumulate while the end-to-end process stays fragmented.
2. Choose the right level of automation
Classify each step as manual judgment, deterministic rule, system action, or AI-assisted interpretation. Automate deterministic work first. Use human review where policy, materiality, or uncertainty requires judgment. Use AI to prepare a decision, not to quietly take an action that needs authorization.
- Fully automate stable, reversible, low-risk system actions
- Route high-value or policy-sensitive decisions to authorized approvers
- Require review when data is incomplete, contradictory, or low confidence
- Keep a recovery path for failed integrations and incorrect routing
- Record overrides as explicit events with an owner and reason
3. Design controls and exceptions into the workflow
Controls are not a final checklist added after the automation is built. They shape the workflow. Decide who can prepare, approve, release, change rules, and close an exception. Define required evidence and prevent the workflow from advancing when a critical control is incomplete.
Design the exception path with the same care as the normal path. Name the owner, required context, response deadline, escalation rule, permitted resolution, and proof needed for closure. An exception queue without ownership is simply a new inbox.
4. Build the workflow in Process Street
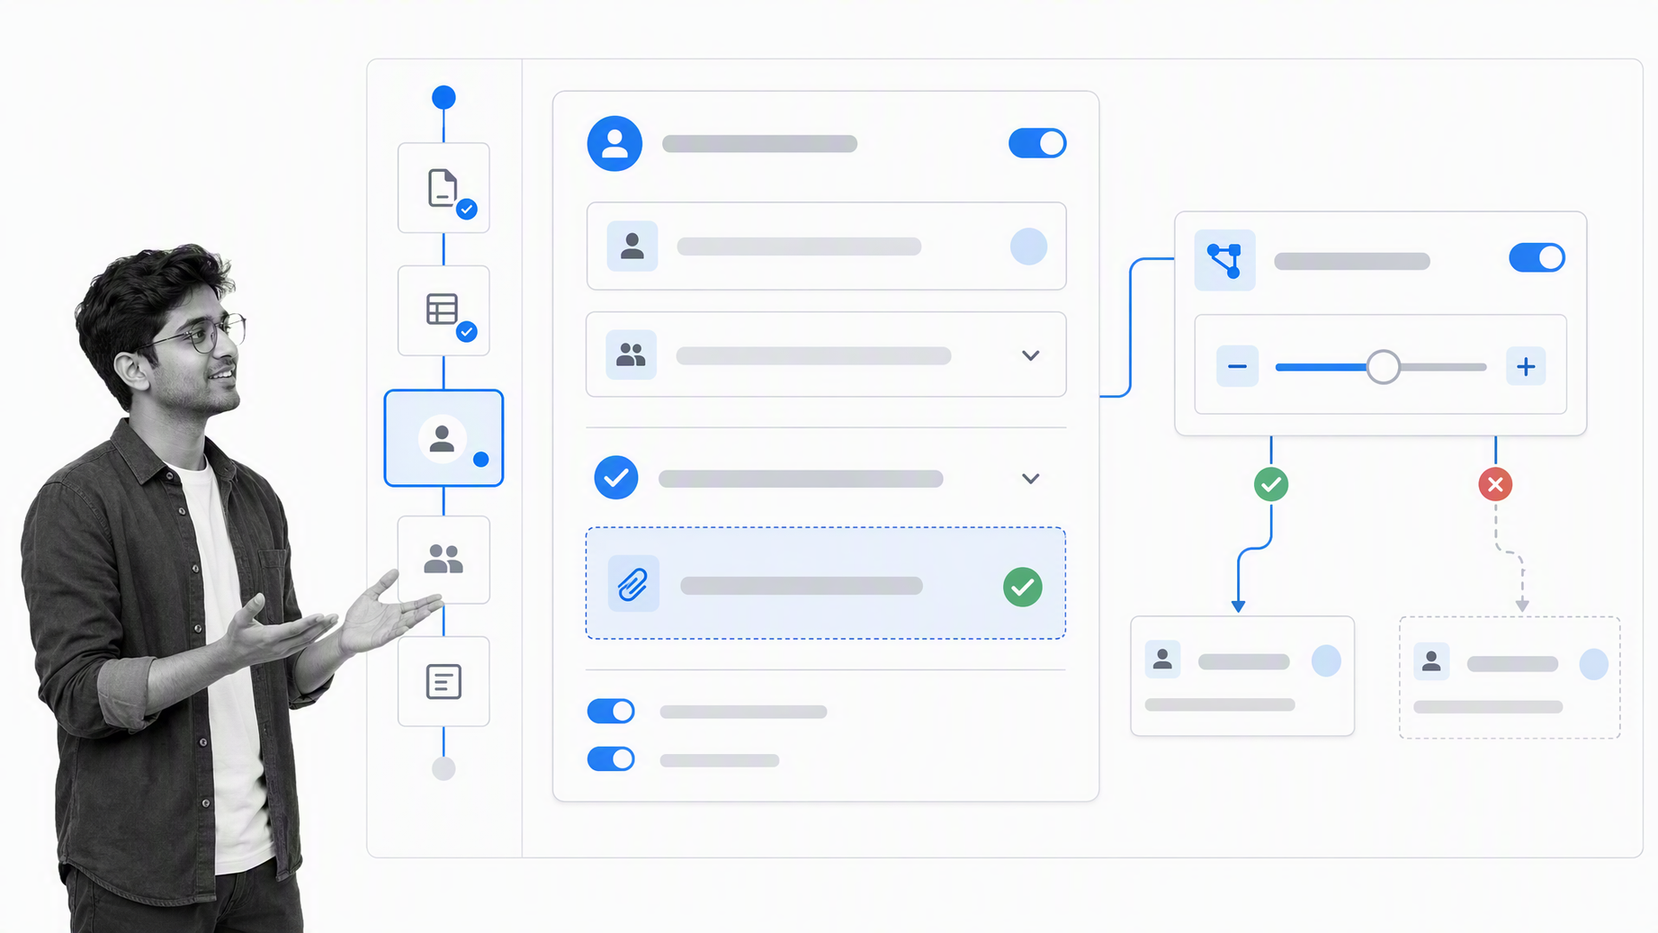
Process Street can turn the mapped procedure into an executable workflow with forms, assignments, deadlines, conditional logic, and approvals. The process can show the right work for the case, collect evidence, pause for a decision, and preserve the execution record.
Connect the workflow to systems of record through the available integration options. Test the exact trigger, authentication, field mapping, retry behavior, permissions, and write-back. A connector is useful only when the complete business event reaches the correct destination and can be verified.
5. Test with normal, exception, and failure cases
Run the workflow with representative data before expanding it. Test the normal case, missing information, duplicate input, rejected approval, changed amount, unavailable integration, unauthorized user, late task, and corrected resubmission. Confirm both the user experience and the final accounting outcome.
Ask a reviewer who did not build the workflow to trace one completed case. They should be able to explain what happened, which rules applied, who decided, what changed in connected systems, and why the case is considered complete.
6. Launch narrowly, measure, and improve
Begin with one process, entity, team, or transaction type. Keep a clear manual recovery route during the initial rollout. Review exceptions frequently, distinguish process defects from training issues, and improve the policy or workflow before expanding volume.
Treat every automation change like a process change. Record what changed, test affected paths, communicate the new behavior, and monitor the first runs. A reliable workflow earns expansion through evidence, not optimism.
Where should AI fit in financial process automation?
AI is useful where finance work contains unstructured information or ambiguous patterns. It can extract fields from documents, classify requests, summarize supporting material, suggest coding, identify likely duplicates, draft follow-up, or rank exceptions for review.
The workflow should constrain what happens after the AI output. Capture confidence or uncertainty, verify critical fields against source records, and route unusual cases to a person. Consequential actions such as payments, ledger postings, access changes, or policy exceptions should remain governed by deterministic rules and authorized decisions.
| Use AI for | Keep deterministic | Require human judgment for |
|---|---|---|
| Document extraction and classification | Required-field checks and routing rules | Ambiguous or conflicting source documents |
| Summaries and draft explanations | Approval thresholds and permissions | Material exceptions and overrides |
| Anomaly triage and prioritization | System-of-record validation | Release of funds or final sign-off |
| Suggested coding or next actions | Audit logging and retention behavior | Policy interpretation and unusual cases |
AI output should be observable. Store the source material, the generated result, the reviewer decision where one is required, and the final action. If the model or prompt changes, retest the affected process just as you would retest a rules engine.
How does Process Street support financial process automation?
Process Street provides a workflow layer for recurring finance operations. Teams can design financial workflows that combine instructions, structured data, ownership, conditional paths, approvals, deadlines, evidence, and connected actions.
That makes it useful when a finance process spans people and systems. An invoice, close task, reconciliation difference, control failure, or audit request can enter a defined route instead of becoming an email thread. The workflow keeps the case context together while the accounting system remains authoritative for balances and transactions.
- Standardize recurring procedures without relying on memory
- Assign work and make responsibility visible
- Apply different paths for routine cases and exceptions
- Pause for approval before consequential steps
- Collect supporting evidence inside the execution record
- Connect workflow events to the systems finance already uses
A strong implementation starts with one process whose pain is visible and whose outcome can be verified. Once the team trusts the workflow, the same design principles can extend to additional entities, controls, and finance cycles.
How should financial process automation success be measured?
Measure both flow and control. Speed alone can hide poor-quality outcomes, while perfect documentation can hide a process that takes too long. Establish a baseline before launch and compare the same process after the workflow has stabilized.
- End-to-end cycle time from trigger to verified outcome
- Waiting time at each handoff or approval
- First-pass completion and return-for-correction rate
- Exception volume, age, cause, and resolution time
- Overdue work and escalation frequency
- Evidence completeness and review rework
- Integration failure and manual recovery rate
- Outcome confirmation in the system of record
Review the distribution, not only the average. A process may look healthy while a small group of high-risk exceptions remains open for too long. Segment results by entity, process type, amount band, exception category, and owner where that helps identify the real constraint.
How do you choose financial process automation software?
Evaluate software against a real process. A feature checklist can confirm that a product has forms, approvals, integrations, or reporting, but it cannot show whether the complete workflow works for your people, controls, and systems.
- Choose one representative process with at least one normal path and one important exception.
- Map the trigger, inputs, owners, decisions, controls, systems, evidence, and outcome.
- Build or prototype the process using realistic roles and permissions.
- Test approvals, exception routing, integration retries, and system-of-record confirmation.
- Ask an independent reviewer to trace a completed case and its evidence.
- Compare administration effort, change control, reporting, security, support, and total operating cost.
Look for a platform that makes process ownership easy to maintain. Finance policies, approval limits, systems, and teams change. If every workflow update requires a long technical project, the automation will drift away from the way work should run.
Security evaluation should follow the actual data and actions in scope. Review identity, permissions, audit logs, encryption, retention, exports, administrative changes, integration credentials, and incident handling. Confirm which controls apply to the deployment and plan you are evaluating.
Financial process automation FAQs
What is financial process automation?
Financial process automation uses workflow rules, integrations, and software to move finance work through intake, validation, approval, exception handling, posting, reconciliation, and evidence capture with less manual coordination. The goal is controlled execution, not simply faster data entry.
Which financial processes should be automated first?
Start with a frequent, rules-based process that has clear inputs, repeated handoffs, measurable delays, and manageable risk. Invoice approval, expense review, account reconciliation, close checklists, and recurring control testing are common starting points. Avoid beginning with a rare process whose policy is still unsettled.
Does financial process automation replace an ERP or accounting system?
Usually not. The accounting or ERP platform should remain the system of record for financial transactions. A workflow platform coordinates the people, approvals, exceptions, evidence, and connected actions around that record so work follows a consistent path.
How do you automate finance without weakening internal controls?
Map each control before automating it, separate preparation from approval where required, limit permissions, route exceptions to named owners, preserve evidence, test changes, and monitor overrides. Automation should make the control more visible and repeatable, not remove human judgment where it matters.
Where should AI be used in financial process automation?
AI is useful for classification, document extraction, summarization, anomaly triage, and drafting. Deterministic rules and authorized systems should control postings, payments, access changes, and other consequential actions. Low-confidence or unusual cases should move to human review.
How can Process Street support financial process automation?
Process Street can turn a finance procedure into an executable workflow with forms, assignments, conditional paths, approvals, deadlines, evidence, and integrations. Finance teams can coordinate recurring work while keeping the accounting system as the authoritative financial record.