Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Financial Process Management: A Complete Guide
Financial process management turns recurring finance work into a controlled operating system. It defines how budgeting, payments, collections, reconciliations, reporting, controls, and evidence move from one accountable owner to the next.
The goal is not automation for its own sake. A strong financial process produces accurate information, protects assets, makes exceptions visible, and leaves enough evidence to explain what happened. This guide shows how to design that system, choose the right processes to automate, govern AI, and improve performance over time.
On this page:
- What is financial process management?
- Which financial processes belong in the operating model?
- What makes a financial process reliable?
- How do you build a financial management process?
- Which financial processes should you automate first?
- How should AI be used in finance workflows?
- What usually goes wrong with financial process management?
- How can Process Street support financial process management?
- How should you measure and improve financial processes?
- Financial process management FAQs
What is financial process management?
Financial process management is the systematic design, execution, control, measurement, and continuous improvement of an organization’s financial activities. It joins process design, financial controls, systems, data, and people so that finance work is completed consistently and can be reviewed later.
A financial process is more than a checklist. It has a trigger, required inputs, a sequence of tasks, named owners, decision rules, approval points, exception paths, an output, and a record of completion. The process may cross accounting software, banking systems, procurement tools, spreadsheets, email, and workflow software, but it still needs one clear operating model.
The Association for Financial Professionals describes financial operations around activities such as accounts payable, accounts receivable, payments, compliance, reporting, and analysis. Financial process management provides the method for coordinating those activities across teams and systems.
It is also broader than accounting software. An accounting or enterprise resource planning system records transactions and maintains financial data. Financial process management governs the work around those records: who supplies information, who reviews it, which rules apply, what happens when something is wrong, and what evidence proves the decision.
Which financial processes belong in the operating model?
The operating model should cover the processes that move money, create financial records, support planning, or prove compliance. The exact scope depends on the business, but the following process families form a practical baseline.
Budgeting and forecasting
Budgeting converts strategic priorities into approved financial plans. Forecasting updates those expectations as revenue, costs, cash, hiring, and operating conditions change. A managed process defines submission deadlines, planning assumptions, version ownership, review thresholds, approval rights, and the handoff from an approved plan to reporting.
Procure-to-pay and accounts payable
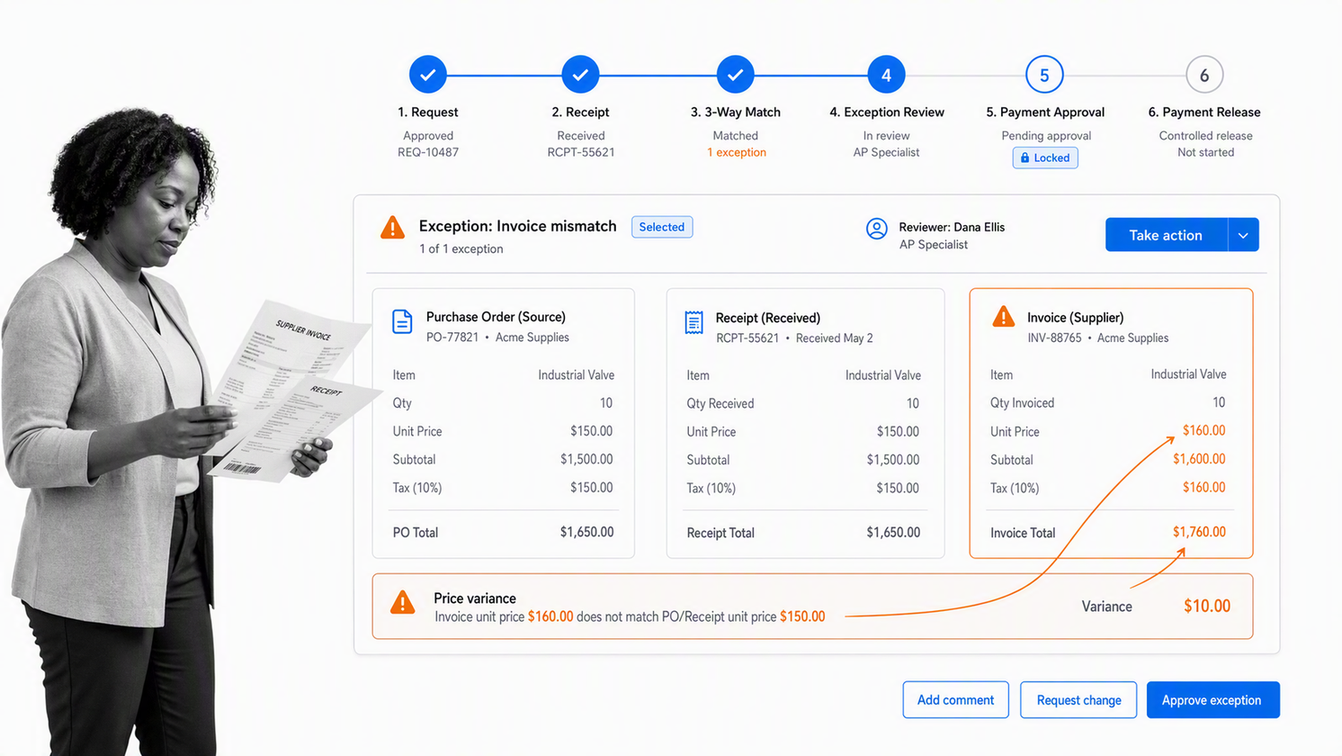
Procure-to-pay connects a business need to purchase approval, supplier setup, order creation, receipt confirmation, invoice matching, exception handling, payment authorization, and recording. Controls should make duplicate invoices, missing purchase orders, unusual payment instructions, and approval conflicts visible before money leaves the business.
Order-to-cash and accounts receivable
Order-to-cash covers customer setup, credit decisions, order acceptance, invoicing, collection, cash application, disputes, and account reconciliation. Process management keeps commercial promises, invoice data, customer communication, and accounting records aligned while making overdue items and disputes easy to assign.
Expense and payroll controls
Expense and payroll processes handle high-volume transactions that affect employees directly. Strong workflows standardize required documentation, policy checks, approvals, change verification, cutoff dates, exception review, and access. Sensitive changes should not depend on an informal message or a single person’s memory.
Month-end close and financial reporting
The close coordinates journal entries, reconciliations, accruals, consolidations, variance review, sign-off, and reporting. The workflow should show which tasks are ready, blocked, late, or reopened. It should also distinguish the person preparing an item from the person reviewing it where the risk requires separation.
Cash management and treasury
Cash management covers bank access, cash positioning, payment release, transfers, liquidity forecasting, debt obligations, and counterparty coordination. The process needs explicit authority levels, verification steps, escalation paths, and evidence because speed without control can increase financial risk.
Tax, audit, and compliance evidence
Tax and audit work depends on complete, accessible records. The IRS notes that electronic record systems must provide a complete and accurate record that remains accessible. A managed evidence process defines what must be retained, who owns it, where it lives, and how reviewers can trace it to the underlying transaction or control.
What makes a financial process reliable?
Reliability comes from the design of the process, not from the number of steps. Each control should address a real risk, each handoff should have an owner, and each exception should lead to an explicit decision.
| Design layer | Question to answer | Evidence of a working process |
|---|---|---|
| Trigger and input | What starts the process, and what information is required? | A complete request with validated source data |
| Ownership | Who prepares, reviews, approves, and escalates? | Named assignments, due dates, and recorded decisions |
| Control | Which risk is prevented or detected? | A required check at the point where the risk occurs |
| Exception | What happens when the normal path fails? | A routed issue with an owner, reason, and resolution |
| System handoff | Which system owns each record and status? | Traceable updates without conflicting versions |
| Completion | What output proves the work is done? | Approved result, supporting evidence, and audit history |
Clear ownership and approval authority
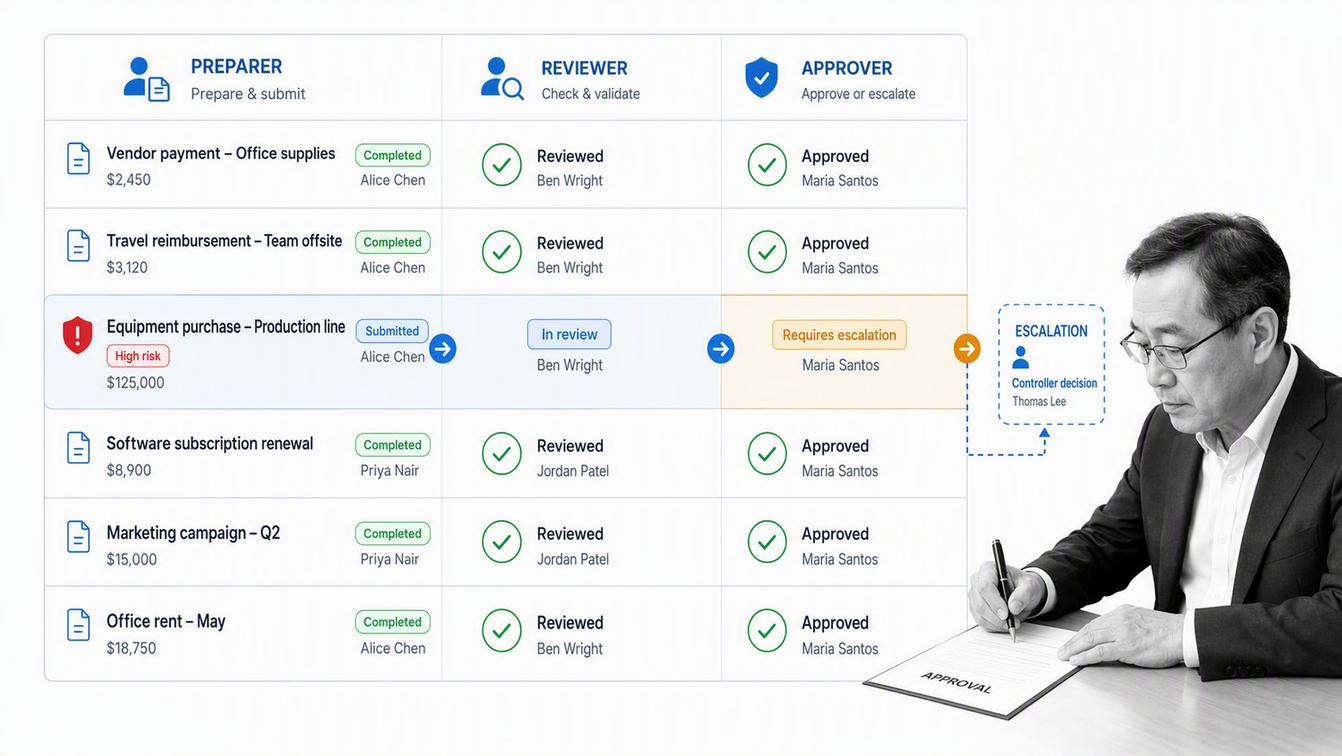
Every financial task needs an accountable owner, and every approval needs a defined authority. The preparer, reviewer, approver, escalation owner, and long-term process owner are different roles, even when a small team assigns several roles to the same person. Where risk is material, separation of duties should prevent one person from initiating, approving, and recording the same transaction.
The University of California, Santa Cruz financial-control guidance emphasizes placing controls where they address the most risk and documenting accountability for the control activity. That principle keeps a workflow focused on meaningful checks instead of administrative ceremony.
Risk-based controls
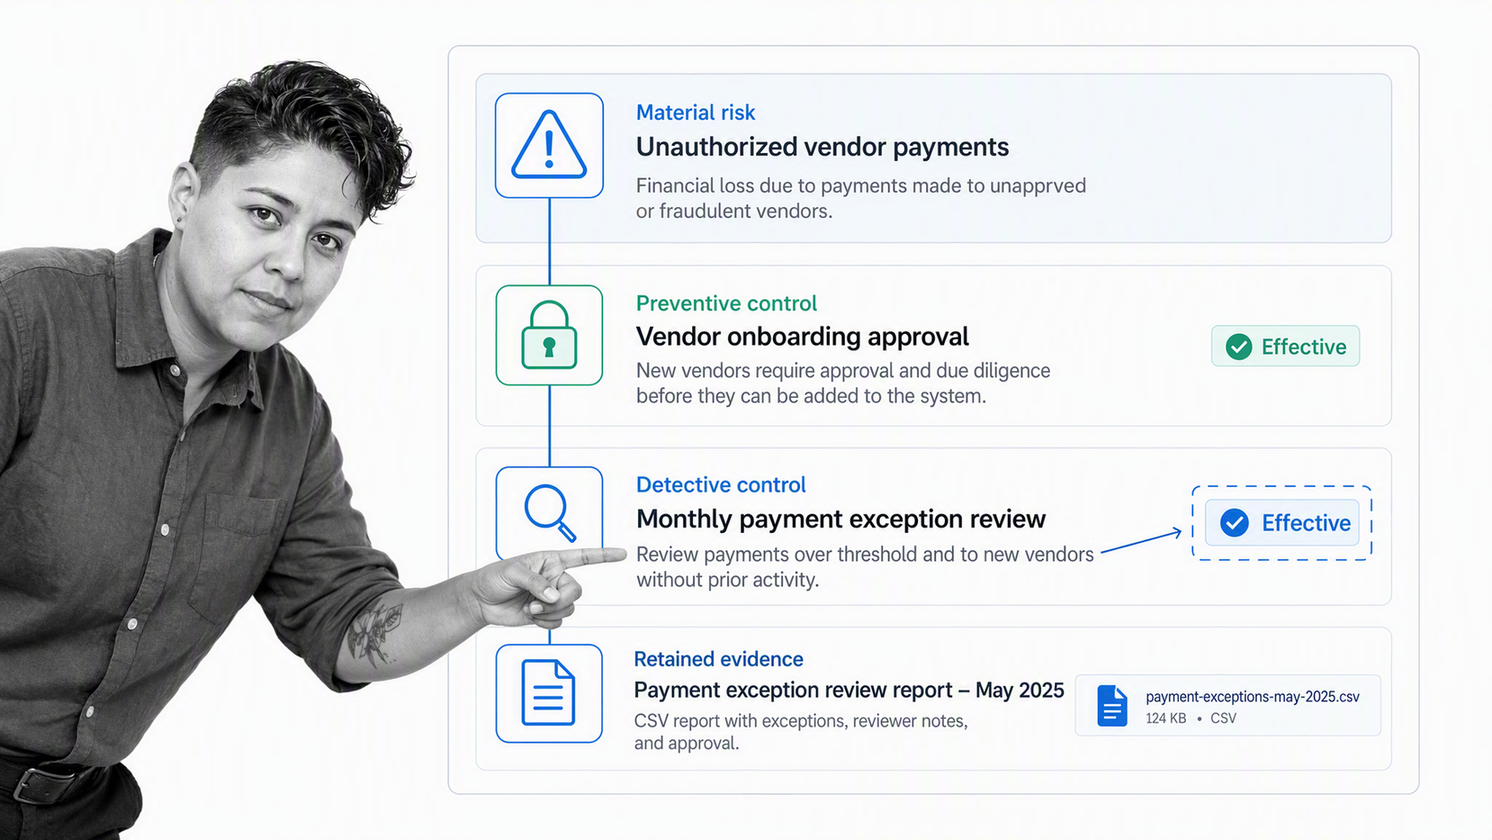
Controls should match the size and nature of the risk. Start with the outcomes that could create a material error, unauthorized transaction, reporting failure, or loss. Identify the controls that prevent or detect those failures, then focus testing and evidence on the controls that matter most.
Connected data and system boundaries
Data fragmentation creates manual copying, conflicting versions, and delayed decisions. Define which system is the source of record for the transaction, supplier, employee, account balance, forecast, approval, and evidence. Then define how the workflow reads from or writes to those systems, who can correct data, and how failed transfers are detected.
Exceptions, evidence, and auditability
The normal path is rarely the hard part. Reliability depends on what happens when an invoice does not match, a forecast changes after approval, a reviewer rejects a journal entry, or evidence is missing. The workflow should capture the reason, route the issue, preserve the decision, and prevent silent completion.
How do you build a financial management process?
Build from the outcome and risk backward. A workflow is ready only when it handles both the normal path and realistic exceptions.
- Define the outcome. State what the process must produce, who uses the result, when it is due, and what quality means.
- Map the current process. Capture the real trigger, inputs, tasks, owners, approvals, systems, waiting points, workarounds, exceptions, and outputs.
- Identify financial and operational risks. Look for unauthorized activity, inaccurate data, duplicate work, missing evidence, late action, access conflicts, and failed handoffs.
- Design the future process. Remove unnecessary steps, standardize intake, assign ownership, place controls at the relevant risk point, and define every exception path.
- Choose the system boundaries. Decide where data is recorded, where work is coordinated, where approvals live, and which system preserves the final evidence.
- Pilot with real cases. Include a normal case, a rejection, missing information, an urgent request, and a system failure so the process is tested beyond the happy path.
- Measure and review. Compare cycle time, accuracy, rework, exception frequency, overdue work, and control performance with the baseline, then assign a recurring review owner.
Standardization does not mean forcing every transaction through one identical path. It means the decision rules are explicit. A routine low-risk item may follow a short path, while a higher-value, unusual, or sensitive item receives additional review.
A broader workflow management model helps when finance processes depend on procurement, sales, operations, legal, HR, or compliance. Shared conventions for ownership, change control, evidence, and reporting reduce the number of disconnected team-level systems.
Which financial processes should you automate first?
Prioritize processes with high repetition, clear rules, structured inputs, visible delays, and measurable outcomes. Do not start with a process that nobody understands. Automation scales the design it receives, including its gaps.
Invoice intake and accounts payable routing
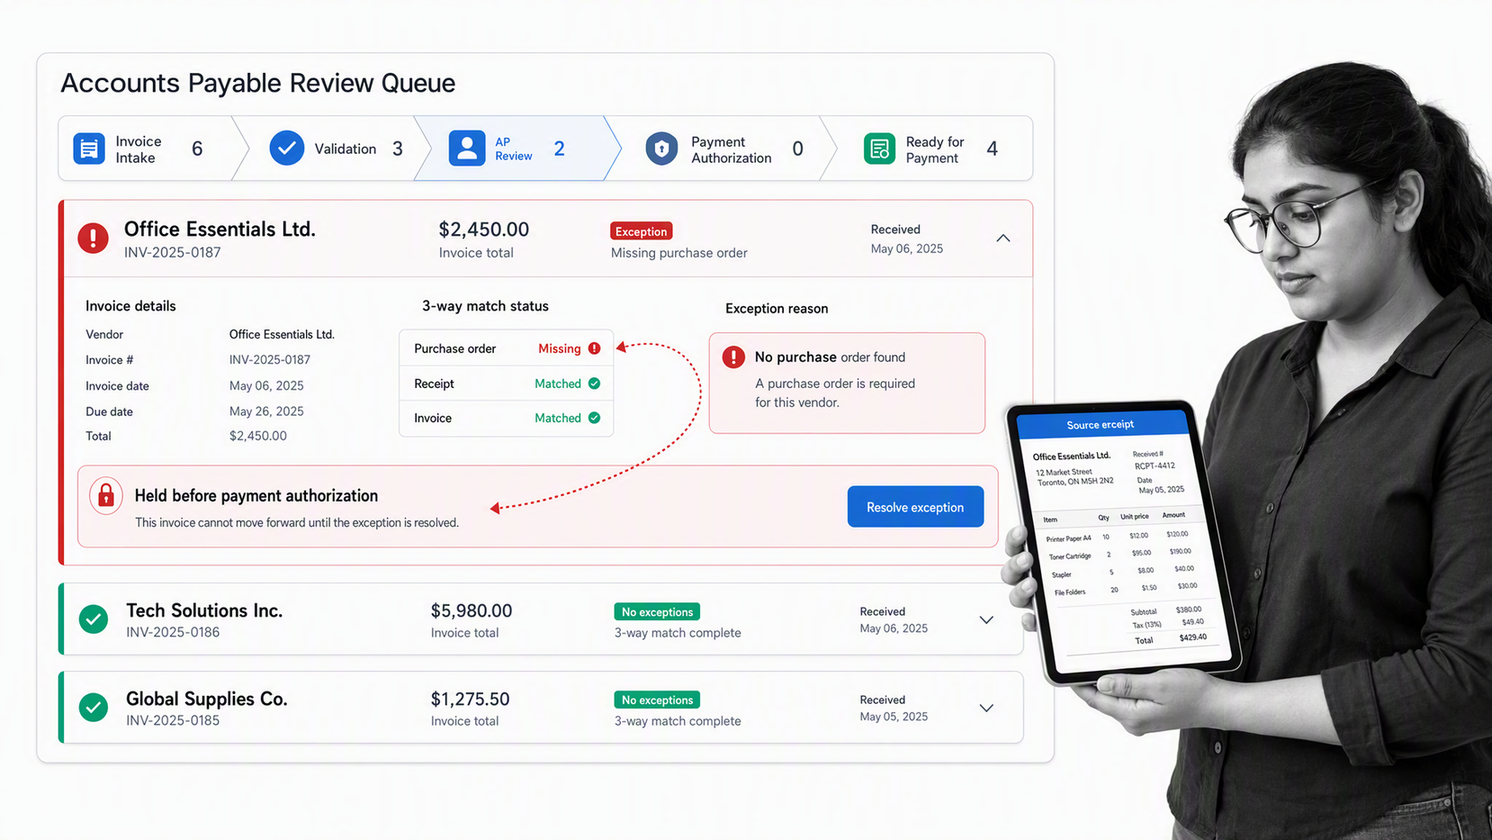
Automate the collection of invoice data, request validation, owner assignment, matching checks, approval routing, reminders, and exception escalation. Keep payment authorization and unusual changes under the appropriate human control.
Expense review and policy checks
Standardize the request, required receipt or evidence, cost center, policy questions, manager approval, finance review, and exception reason. The workflow should make incomplete or out-of-policy expenses visible before reimbursement.
Account reconciliation and close coordination
Schedule recurring reconciliations, assign preparers and reviewers, require supporting evidence, route variances, and track sign-off. Automation is especially useful for reminders, dependency visibility, recurring assignments, and escalation when a close task is blocked.
Budget requests and forecast changes
Use a standard request with assumptions, amount, timing, owner, business rationale, and supporting data. Route the request based on policy and preserve the decision so the approved change can be reflected in planning and reporting systems.
Financial reporting and evidence collection
Automate recurring report preparation tasks, data-request assignments, evidence reminders, review steps, distribution, and retention. Keep analytical conclusions and material judgments with accountable finance leaders.
Cash forecasting and control monitoring
Automate the collection of inputs, update reminders, threshold alerts, and review assignments. Forecasting still requires judgment about timing, uncertainty, and business conditions, so the workflow should distinguish machine-produced signals from approved assumptions.
How should AI be used in finance workflows?
AI can help classify requests, extract invoice or contract fields, match records, summarize exceptions, draft explanations, and prioritize anomalies. These are useful assistive tasks because they reduce manual handling while leaving a clear point for validation.
The NIST AI Risk Management Framework provides a voluntary structure for governing, mapping, measuring, and managing AI risk. In a financial process, that translates into named accountability, documented use cases, tested limitations, access controls, monitoring, and human review matched to the consequence of an error.
Use bounded AI tasks
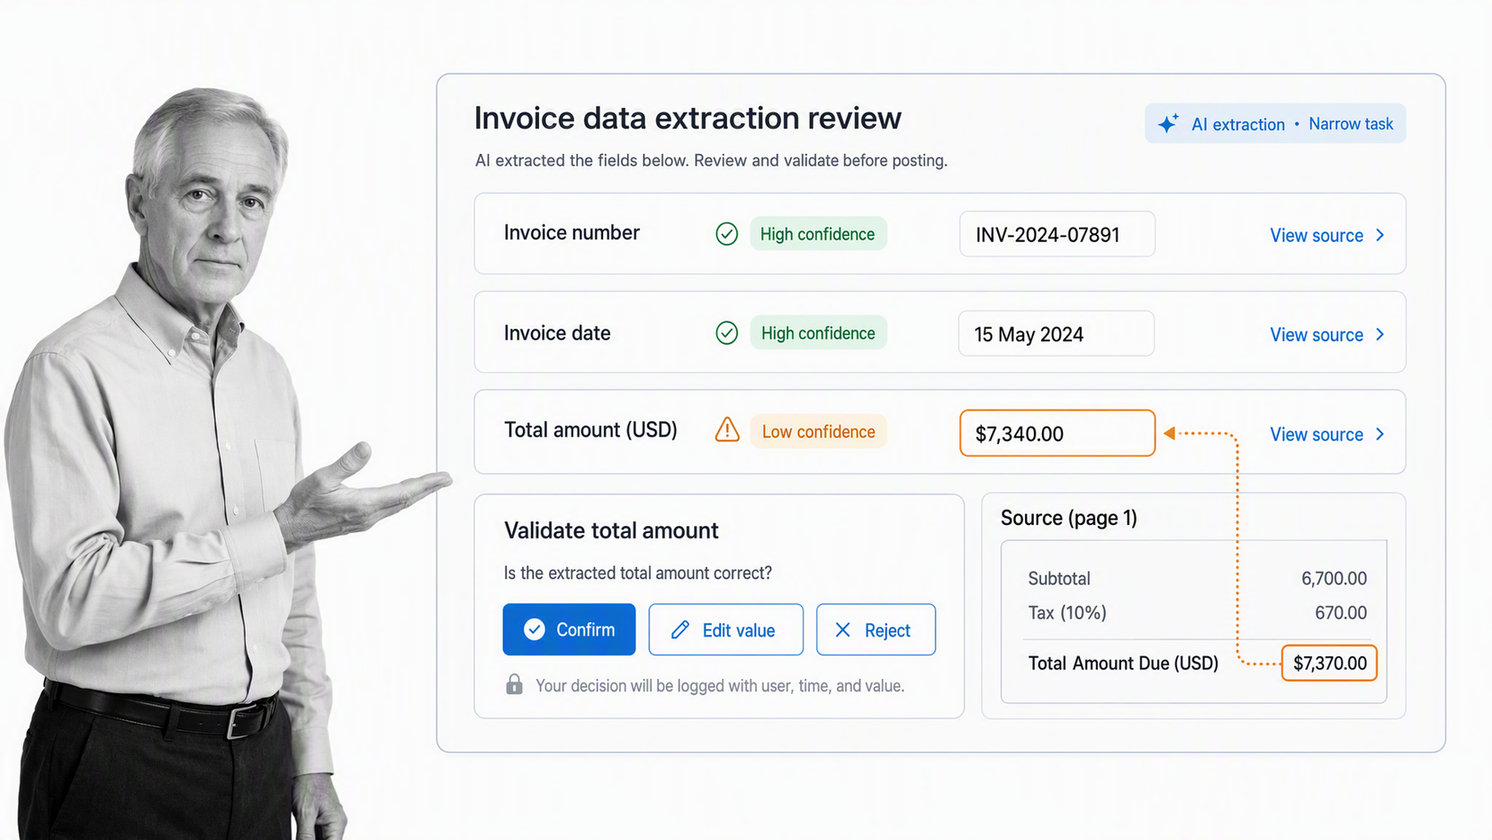
Give the model a narrow job with a defined input, output, confidence rule, and fallback. Classification, extraction, comparison, summarization, and draft preparation are easier to test than an open-ended instruction to manage a financial decision.
Keep judgment and authorization accountable
AI can prepare information for a decision, but the workflow should identify who validates the output and who has authority to approve the result. Payment release, accounting conclusions, control exceptions, access changes, and material forecasts need review appropriate to their risk.
Preserve traceability
Record the source data, model-assisted output, validation, corrections, decision, and exception. If a finance leader cannot explain what information was used and who accepted the result, the workflow is not ready for sensitive use.
What usually goes wrong with financial process management?
Lack of standardized processes
Teams often inherit different forms, approval paths, naming conventions, and spreadsheet structures. The same type of transaction may receive different treatment depending on who handles it. Standardize the decision rules, required information, ownership, and evidence before optimizing the technology.
Reliance on manual processes
Manual work is not automatically bad, but repeated copying, chasing, scheduling, and status reporting consume attention without adding financial judgment. Automate the handoff and evidence mechanics so people can focus on exceptions, analysis, and decisions.
Data fragmentation
Finance data may be spread across accounting systems, banking portals, payroll tools, procurement platforms, spreadsheets, email, and shared drives. Without defined sources of record and reconciliation rules, teams spend time debating which number or document is current.
Weak integration and hidden failures
An integration can move data quickly and still fail silently. Every automated handoff needs an owner, a success signal, an error state, retry behavior, and a way to reconcile the destination with the source.
Inadequate financial controls and governance
Controls fail when authority is vague, access is too broad, evidence is collected after the fact, or exceptions happen outside the system. Governance should define process ownership, change approval, permissions, control testing, retention, and escalation.
Training without process ownership
Financial training matters, especially when policies, systems, or reporting requirements change. Training is not a substitute for a well-designed process. Give people clear instructions at the point of work, then assign someone to maintain the workflow as the business changes.
How can Process Street support financial process management?
Process Street provides an execution layer for recurring finance work. Teams can build financial workflows with assigned tasks, due dates, required fields, files, approvals, conditional routing, evidence capture, automations, and run history.
That makes it useful when an accounting, enterprise resource planning, banking, procurement, payroll, or reporting system remains the source of record but the work around that system needs clearer ownership and control. The workflow can coordinate invoice approvals, expense reviews, close tasks, reconciliations, budget changes, audit requests, and recurring control activities without pretending to replace the underlying financial ledger.
Turn policies into executable finance workflows
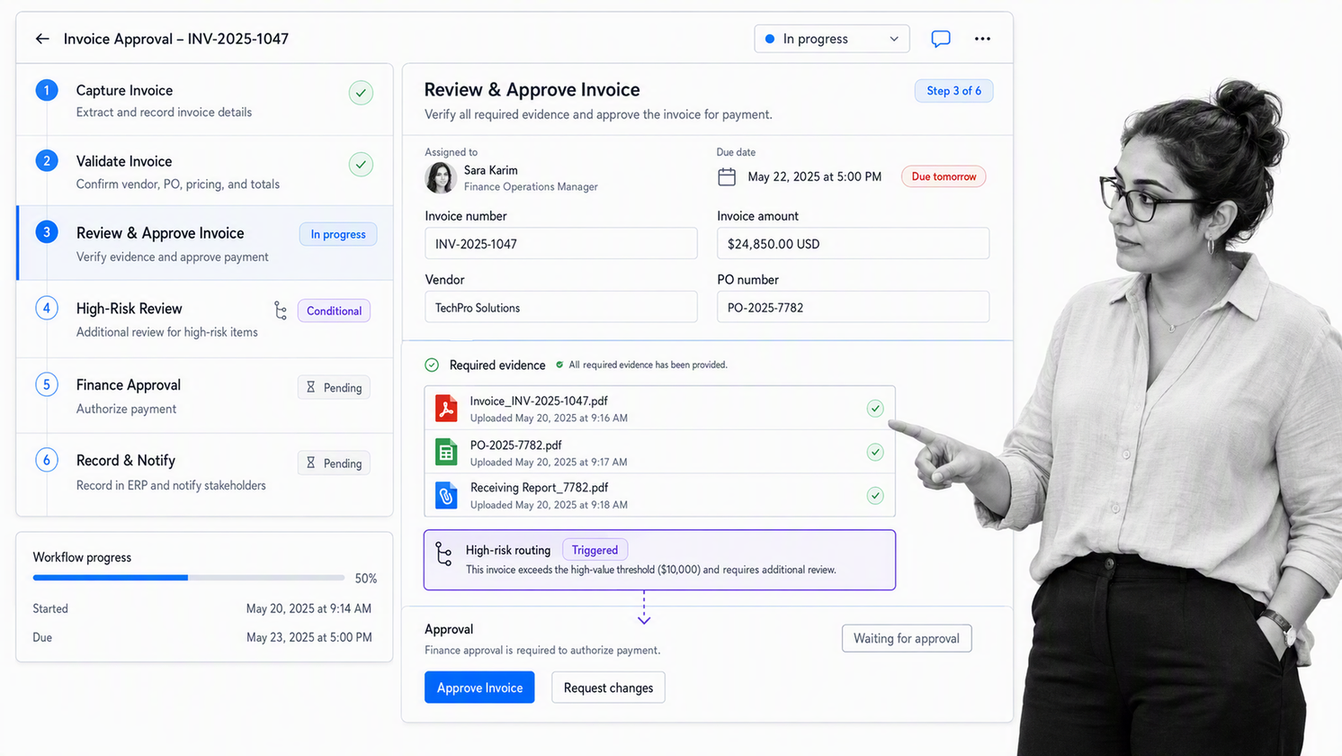
A policy explains what should happen. An executable workflow assigns the task, requires the information, applies the rule, routes the decision, and keeps the evidence. For more on that control model, see workflow automation compliance.
Make approvals and exceptions visible
Conditional paths can direct an item to the appropriate reviewer based on the information supplied. Rejections and exceptions remain connected to the work instead of disappearing into private inboxes or chat threads.
Keep evidence with execution
Required fields, uploaded files, completion records, reviewer decisions, and workflow history keep proof close to the task that created it. That reduces the effort required to reconstruct a financial process later.
How should you measure and improve financial processes?
Measure the outcome, the flow of work, and the control. A faster process is not better if it creates more errors or weakens review. A heavily controlled process is not better if low-risk work waits unnecessarily.
- Cycle time from trigger to approved output
- Active work time compared with waiting time
- Percentage of requests complete at intake
- Exception, rejection, and rework rates
- Overdue tasks and escalation frequency
- Reconciliation breaks and unresolved differences
- Control completion and evidence completeness
- Manual touches, duplicate entry, and handoff failures
- Forecast accuracy and reporting timeliness where applicable
- User effort and recurring support issues
Conduct regular reviews
Review the process on a recurring schedule and after material changes in systems, policy, organization, risk, or volume. Look at recurring exceptions rather than only average completion time. A repeated exception is usually a design signal, not an individual performance issue.
Improve the bottleneck, then test the control
Identify the step creating the most delay, error, or control exposure. Change one part of the process, compare results with the baseline, and confirm the control still operates as intended. Continuous improvement works best when the process owner can see current work, exceptions, evidence, and performance in one review loop.
If you want to apply this model to a real finance workflow, request a Process Street demo and bring one process with its current steps, exceptions, approvals, and evidence requirements.
Financial process management FAQs
What is financial process management?
Financial process management is the discipline of designing, running, controlling, measuring, and improving repeatable finance work. It connects people, policies, data, systems, approvals, exceptions, and evidence so financial tasks produce reliable outcomes.
What are examples of financial processes?
Common examples include budgeting, forecasting, procure-to-pay, accounts receivable, expense review, payroll controls, cash management, account reconciliation, month-end close, financial reporting, tax documentation, and audit evidence collection.
What is the difference between financial process management and accounting software?
Accounting software records transactions and maintains financial data. Financial process management coordinates the work around those records, including requests, assignments, approvals, deadlines, exceptions, evidence, and handoffs between people and systems.
Which financial process should a business improve first?
Start with a repeated process that has meaningful risk or delay, a clear owner, frequent exceptions, and an outcome you can measure. Invoice approval, account reconciliation, expense review, and close coordination are common starting points.
How can financial process automation improve control?
Automation can enforce required fields, route approvals, schedule recurring work, issue reminders, flag exceptions, and preserve evidence. It improves control only when roles, thresholds, escalation paths, and human review points are designed into the workflow.
How should AI be governed in financial processes?
Use AI for bounded assistance such as classification, extraction, drafting, matching, and anomaly triage. Define accountable owners, validation rules, access controls, confidence thresholds, human review, exception handling, and an audit record before relying on its output.