Turn every policy into automated workflows with built-in enforcement and audit-ready proof.


Sell-Side M&A Process
The sell-side M&A process is the structured path a company follows to prepare for sale, approach qualified buyers, compare offers, complete due diligence, negotiate definitive terms, and close the transaction. The seller and its advisors control the process, the information flow, and the timetable.
A strong process does more than find a buyer. It creates credible competition, protects confidential information, gives decision-makers a common view of value and risk, and keeps the business operating while the deal advances. Finance, legal, tax, operations, executives, and outside advisors must deliver decision-ready evidence at the right stage, not merely complete a long checklist.
This guide explains the complete sell side M&A process, from readiness through transition, with practical controls for owners and deal teams.
In this guide:
- What is the sell-side M&A process?
- How does the sell-side M&A process work?
- Why preparation determines deal quality
- Who is involved in a sell-side M&A transaction?
- The nine stages of the sell-side M&A process
- How should sellers manage diligence and negotiation?
- What can derail a sell-side M&A process?
- How Process Street helps coordinate deal execution
- Sell-side M&A process checklist
- Frequently asked questions
What is the sell-side M&A process?
Sell-side M&A is the seller-led process for marketing and transferring a business, a controlling interest, or a group of assets to a buyer. The seller may be a founder, family, corporate parent, private equity sponsor, or group of shareholders. The buyer may be a strategic acquirer, financial sponsor, management team, or another qualified investor.
The sell-side team normally begins by clarifying shareholder objectives, preparing the company and its records, valuing the business, and deciding how broad or targeted the buyer outreach should be. It then controls access to information as buyers move from initial interest to indications of interest, management meetings, letters of intent, diligence, definitive agreements, and closing.
This differs from a buy-side mandate. A buy-side team searches for and evaluates targets on behalf of an acquirer. A sell-side team prepares one company for the market and creates a disciplined process around potential buyers. Both sides conduct analysis, but their objectives, information rights, and negotiating leverage differ.
How does the sell-side M&A process work?
The process works as a gated funnel. A broad set of possible buyers receives limited information first. Buyers that fit the strategy and accept confidentiality terms receive deeper materials. Serious bidders advance through management access and diligence. Each gate should require evidence of commitment, such as a complete proposal, identified decision-makers, credible financing, or acceptance of the process timetable. A preferred bidder usually receives exclusivity only after the seller is satisfied with value, structure, certainty, and key terms.
Build a transaction readiness workstream
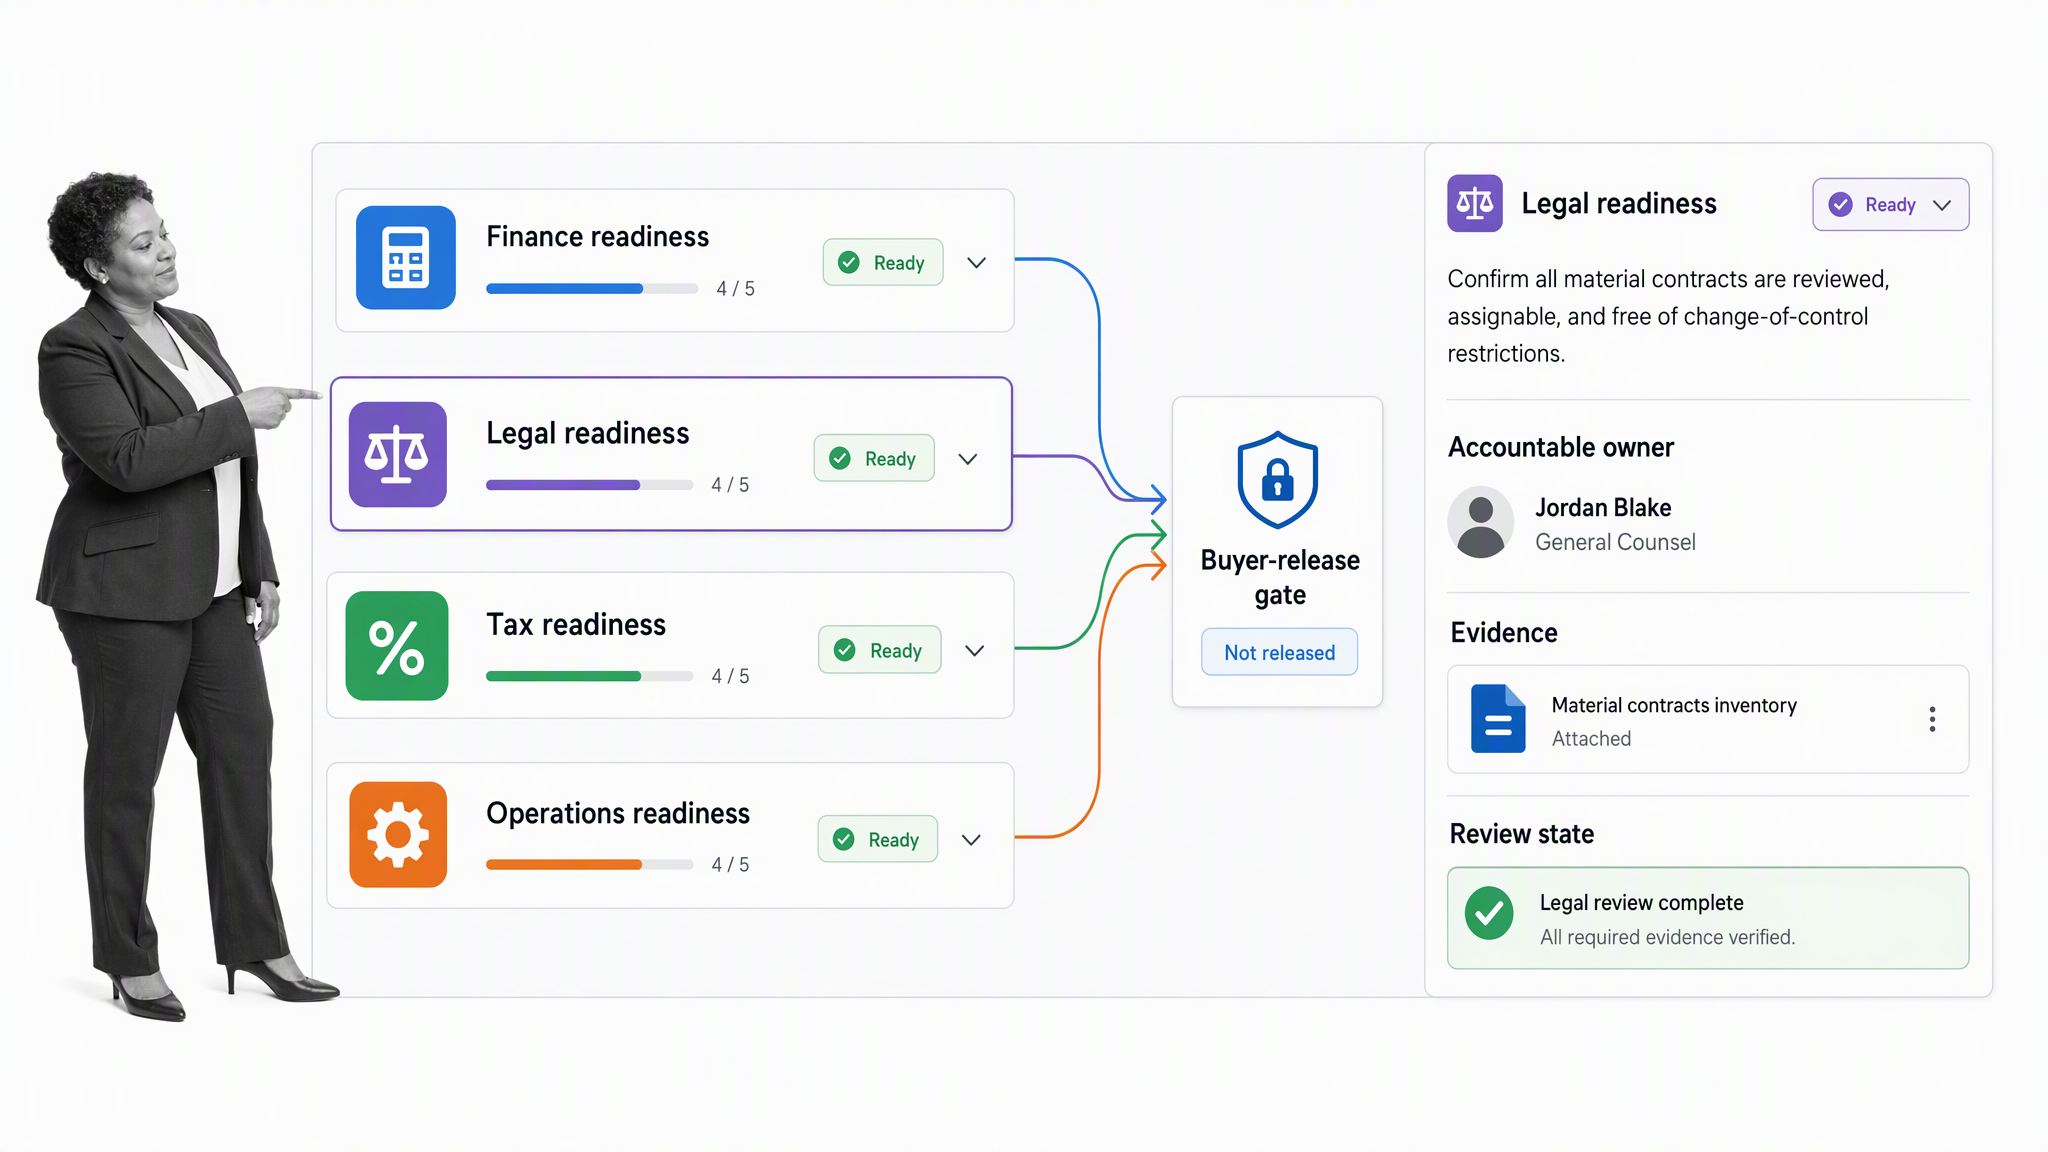
Before outreach begins, the team should build a work plan that covers financial cleanup, commercial analysis, legal records, tax questions, customer and supplier dependencies, intellectual property, people matters, cybersecurity, and regulatory issues. A clear process map helps show which outputs feed the next decision and where delays are likely to occur.
The seller also decides who may know about the transaction, how questions will be answered, and how normal business operations will continue. Confidentiality is not a single agreement. It is a system of access levels, approved communications, document controls, and escalation rules.
Control information as buyer commitment increases
A teaser may describe the opportunity without identifying the company. After a buyer signs a nondisclosure agreement, the seller can share a confidential information memorandum, selected financial data, and process instructions. More sensitive material belongs in the data room and should be released in stages. This protects the company while giving credible buyers enough evidence to underwrite an offer.
Compare more than headline price
A high offer can still be weak if it depends on uncertain financing, aggressive working-capital assumptions, extensive holdbacks, a large earnout, or conditions the seller cannot meet. The board and shareholders should compare value, form of consideration, financing, regulatory risk, employee treatment, post-closing obligations, and the probability of reaching closing.
Use one bid-comparison scorecard for every serious proposal. Record headline value, cash at closing, rollover or contingent consideration, financing evidence, diligence conditions, requested exclusivity, regulatory exposure, transition requirements, and unresolved assumptions. A shared scorecard makes tradeoffs visible before momentum or bidder familiarity distorts the decision.
Why preparation determines deal quality
Preparation affects both leverage and speed. Buyers discount uncertainty. If financial statements do not reconcile, contracts are missing, customer concentration is unexplained, or ownership of intellectual property is unclear, buyers may reduce price, demand protection, slow the process, or leave.
A readiness review should identify issues while the seller still has time to fix them or explain them. The finance team can normalize earnings and prepare a reliable financial-statement package. Legal counsel can organize material contracts and corporate records. Operations leaders can document recurring processes, dependencies, and the management structure. Tax advisors can test transaction structures before a term sheet narrows the options.
Preparation also improves the company narrative. Buyers need to understand what creates durable value, which risks are manageable, why the market opportunity is credible, and how the business can perform under new ownership. The strongest narrative is supported by evidence, not optimism.
Choose the right sale process design
The seller and its advisors should choose the process shape deliberately. A broad auction may create more competitive tension, but it increases the number of contacts, confidentiality risks, and management demands. A limited auction concentrates effort on a smaller group of qualified buyers. A bilateral process can move quickly when one buyer has a compelling strategic fit, but the seller has less market evidence against which to test price and terms.
The right design depends on the owners’ priorities, the sensitivity of the business, the depth of the buyer universe, regulatory considerations, and the cost of distracting management. Whatever the design, the rules should be clear before outreach begins: who can be contacted, what information each stage unlocks, how bids will be evaluated, when management becomes involved, and who can authorize a change in strategy. Process design is a governance choice, not just a marketing choice.
Who is involved in a sell-side M&A transaction?
A sell-side process is cross-functional by design. The exact team depends on the company and transaction, but the core roles are consistent:
- Board, owners, and executive sponsor: Set objectives, approve major decisions, and define acceptable tradeoffs.
- Investment banker or M&A advisor: Helps position the business, identify buyers, manage outreach, coordinate bids, and support negotiation.
- Legal counsel: Manages confidentiality, disclosure, transaction structure, definitive agreements, approvals, and closing mechanics.
- Finance and accounting: Prepare historical results, forecasts, working-capital analysis, quality-of-earnings support, and responses to buyer questions.
- Tax advisors: Analyze asset, stock, and merger structures and their consequences for the seller and buyer.
- Management team: Explain the business, support diligence, maintain performance, and prepare for transition.
- Specialists: Address areas such as antitrust, benefits, cybersecurity, environmental exposure, intellectual property, insurance, or industry regulation.
One person should own the integrated deal plan, even when advisors lead individual workstreams. Without a single source of ownership, buyer requests duplicate, deadlines conflict, and decisions disappear into email threads.
The nine stages of the sell-side M&A process
1. Define objectives and readiness
Clarify why the owners are considering a sale, what outcome matters most, what must remain confidential, and which constraints are nonnegotiable. Assess whether the company, management team, records, and performance are ready for buyer scrutiny.
2. Select advisors and establish governance
Choose advisors based on relevant transaction experience, buyer access, execution capacity, and fit with the owners. Establish decision rights, communication rules, review gates, and a cadence for the core team. A formal decision-making process prevents avoidable confusion when bids arrive.
3. Prepare valuation and marketing materials
Analyze valuation using methods appropriate to the business, such as comparable companies, precedent transactions, and discounted cash flow. Prepare the teaser, confidential information memorandum, management presentation, financial model, and supporting evidence. Use an ROI analysis only where it reflects defensible buyer economics rather than a promotional estimate.
4. Build and qualify the buyer universe
Create a buyer list based on strategic fit, financial capacity, transaction history, regulatory constraints, and confidentiality risk. Segment buyers so the outreach plan matches the seller’s priorities. A broad auction can increase competition, while a targeted process may better protect confidentiality.
5. Launch outreach and manage indications of interest
Contact approved buyers, distribute the teaser, execute nondisclosure agreements, and provide the information memorandum. Set clear instructions for nonbinding indications of interest so proposals can be compared on the same dimensions.
Manage the buyer pipeline
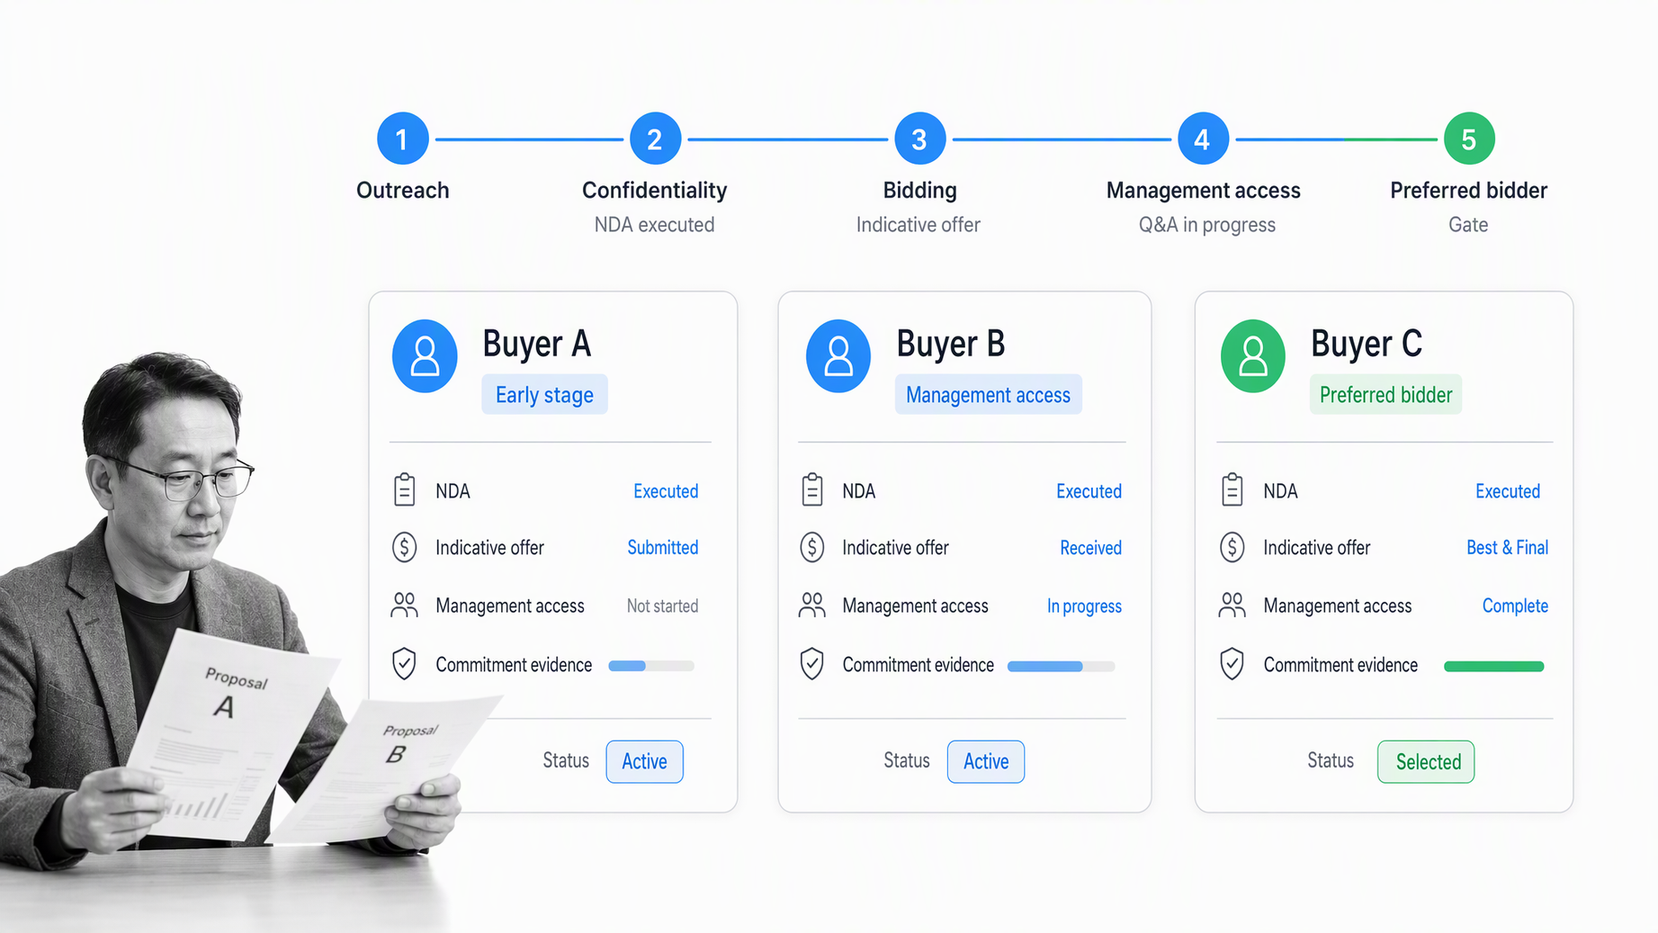
Track each buyer’s status, questions, access level, management interactions, proposal terms, financing confidence, decision-makers, and next action. The pipeline should distinguish interest from evidence of commitment. A buyer that has reviewed the materials, assembled its approval team, and submitted a complete proposal is more credible than one that offers enthusiasm without process discipline. Apply the same release and response rules to buyers at the same stage so the process remains defensible.
6. Hold management meetings and solicit letters of intent
Invite the strongest parties to meet management and test the investment thesis. Share deeper information in a controlled way, answer material questions consistently, and request letters of intent or final-round proposals. Use a structured negotiation strategy before bidders attempt to change the frame.
7. Select a preferred bidder and negotiate the LOI
Compare total value, consideration, financing, conditions, regulatory risk, diligence scope, timing, escrow or holdback expectations, management treatment, and closing confidence. The LOI should capture the principal commercial terms and define any exclusivity period carefully. Counsel should identify which provisions are binding.
8. Complete due diligence and definitive agreements
The preferred buyer validates financial, legal, commercial, tax, operational, technology, people, and regulatory matters. The seller should run a disciplined M&A due diligence checklist and maintain a complete due diligence process so requests, responses, evidence, owners, and open issues remain connected.
The parties negotiate the purchase agreement and related documents in parallel. A sales purchase agreement template can help organize the issues, but transaction counsel must tailor the definitive agreement to the deal.
9. Obtain approvals, sign, close, and transition
Complete board, shareholder, lender, contractual, and regulatory approvals, satisfy closing conditions, sign the definitive documents, transfer consideration, and execute the closing checklist. Certain transactions require premerger notification and a waiting period under the Hart-Scott-Rodino framework, as described by the Federal Trade Commission’s merger review process. The Department of Justice merger guidelines describe factors and frameworks the agencies use when reviewing transactions.
For applicable asset acquisitions, the seller and purchaser may have reporting obligations involving purchase-price allocation. The IRS instructions for Form 8594 explain when the form is used. Deal teams should confirm the current requirements with qualified legal and tax advisors rather than relying on a generic checklist.
Closing is not the end of execution. The seller must manage communications, employee changes, customer and supplier commitments, transition services, records, retained liabilities, and post-closing adjustments.
How should sellers manage diligence and negotiation?
Run due diligence from a controlled request list
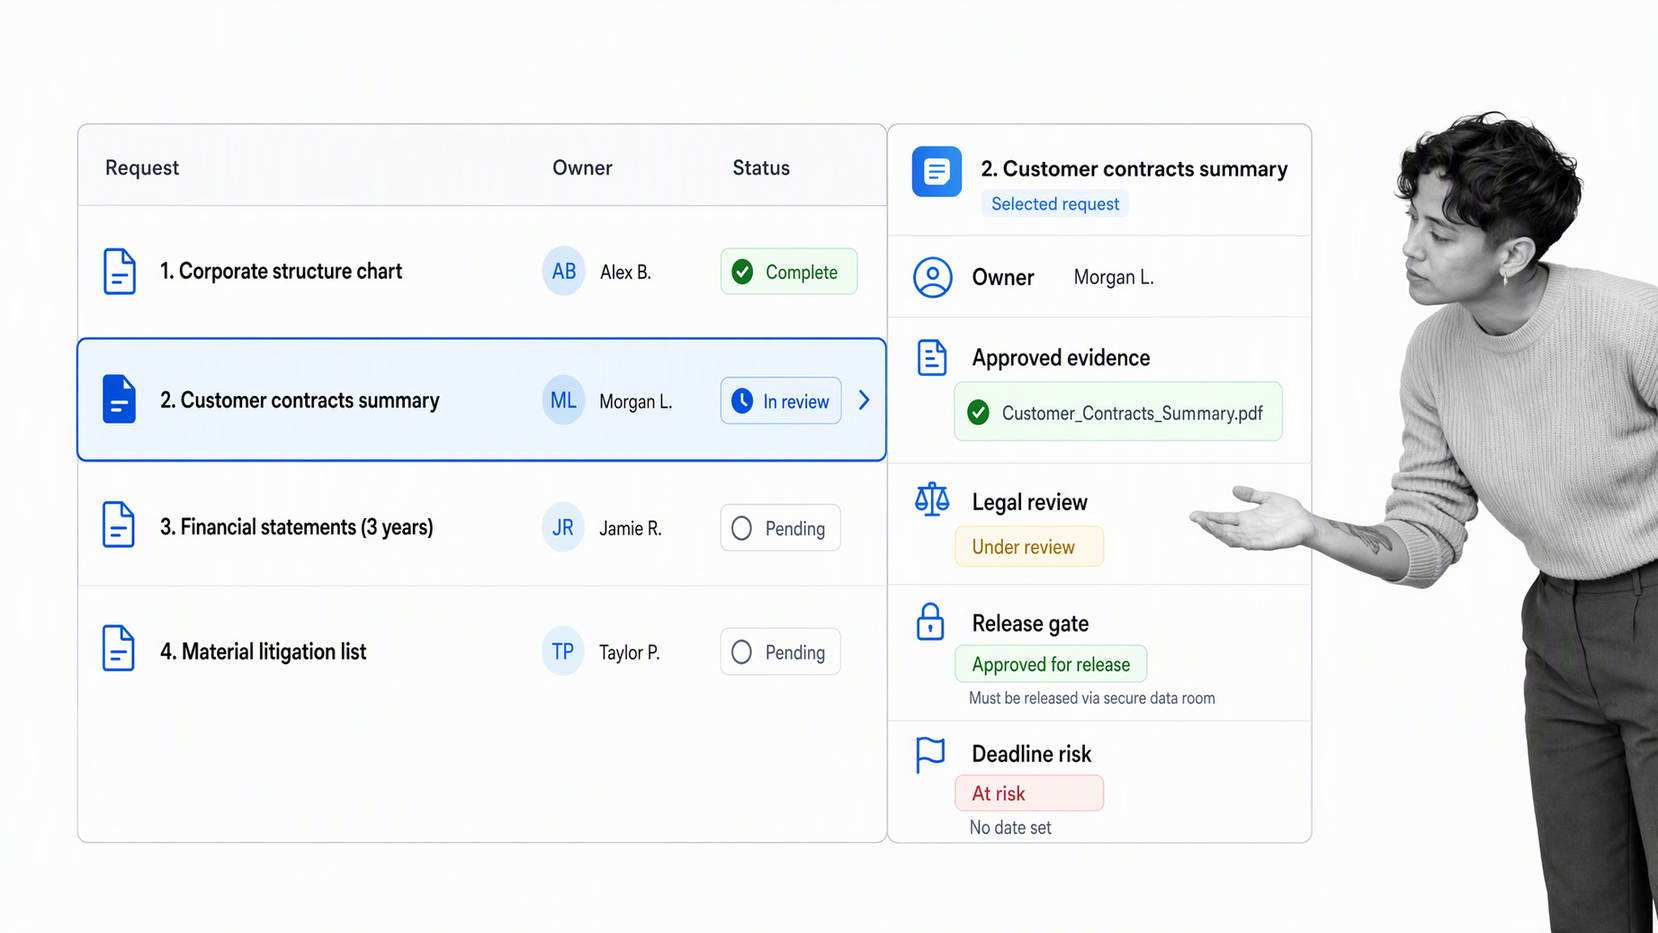
Every request should have an owner, priority, due date, reviewer, source file, response status, and record of what was shared. Similar requests should be consolidated, and each response should point back to an approved source rather than create a second version of the truth. Sensitive documents should follow approved access rules. The team should track issues that could affect price, structure, representations, indemnities, closing conditions, or timing.
The current HSR rules and guidance should be reviewed when a transaction may trigger premerger requirements. Regulatory work needs its own owners and dependencies because it can change the path to closing.
Negotiation should continue across the whole package, not just price. The seller may trade certainty against value, cash against rollover equity, a clean exit against an earnout, or speed against broader diligence. Before granting exclusivity, the seller should understand which leverage will disappear once competing bidders are paused.
What can derail a sell-side M&A process?
- Unreliable financial information: Reconciliation problems or unexplained adjustments weaken buyer confidence.
- Operational deterioration: Missed targets during the process can reduce value and leverage.
- Poor confidentiality controls: Leaks can disrupt employees, customers, suppliers, and buyer competition.
- Incomplete records: Missing contracts, ownership documents, approvals, or compliance evidence extend diligence.
- Single-buyer dependence: A narrow process may leave the seller with limited leverage if that buyer retrades.
- Unmanaged decision rights: Owners, executives, and advisors can send conflicting instructions or delay approvals.
- Weak issue escalation: Problems remain hidden until they threaten signing or closing.
- Closing treated as the finish line: Transition obligations and post-closing adjustments are left without owners.
A sell-side process is also vulnerable to coordination failure. The right answer can still arrive too late if work is scattered across spreadsheets, inboxes, chat, and disconnected folders. Good process management keeps work visible at the level of decisions, evidence, and dependencies.
How Process Street helps coordinate deal execution
Turn the deal plan into an executable workflow
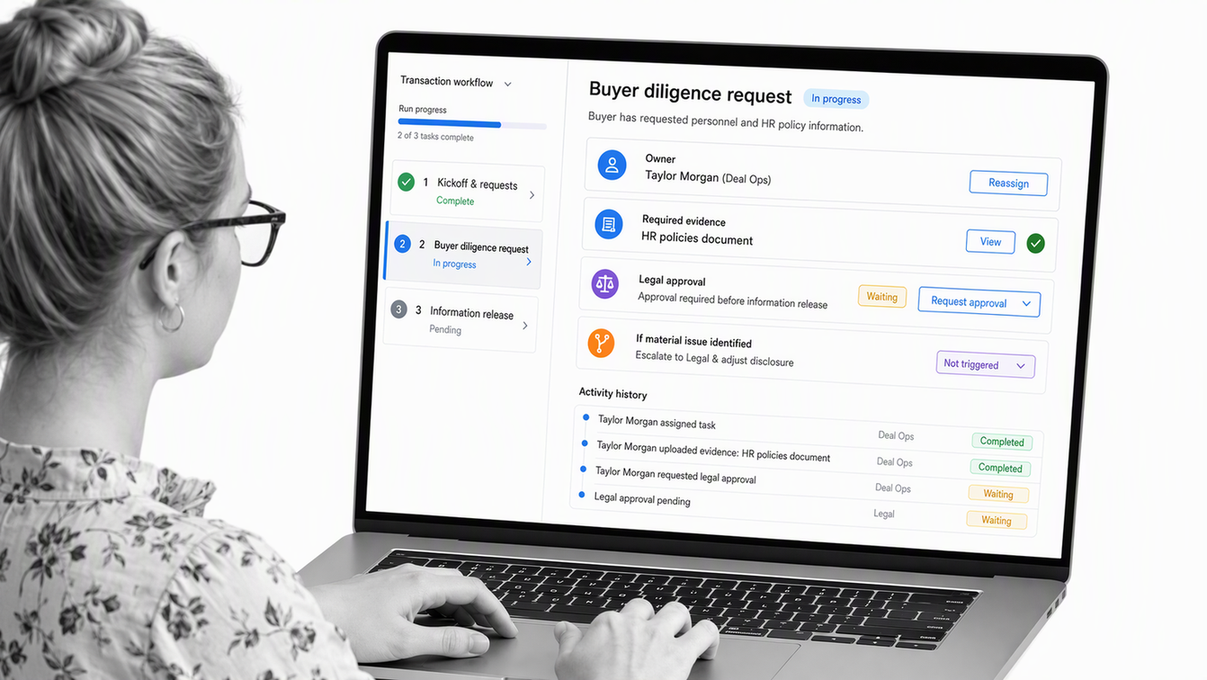
Process Street is an agentic process automation platform for high-stakes operations. A deal team can turn the transaction plan into a controlled workflow with assignments, required fields, due dates, approval gates, conditional routes, and a history of activity. That gives finance, legal, tax, operations, and advisors one operating record while source documents remain in the systems approved for the transaction.
For example, a buyer request can enter a workflow, route to the responsible owner, require legal review before release, record the approval, and escalate when the deadline is at risk. A material issue can follow a separate path for executive review. The platform supports the coordination layer around the deal without replacing the judgment of investment bankers, lawyers, accountants, tax advisors, or the board.
Teams can start with a focused workflow automation for diligence requests, then extend the same control pattern through Process Street workflows for buyer access, approvals, issues, signing, and transition.
Sell-side M&A process checklist
- Define shareholder objectives, acceptable outcomes, and confidentiality boundaries.
- Assess readiness across finance, legal, tax, commercial, operations, people, technology, and regulation.
- Select advisors and establish decision rights, review gates, and meeting cadence.
- Prepare valuation work, marketing materials, management materials, and a controlled data room.
- Build, qualify, and approve the buyer universe.
- Launch outreach under a staged information-release plan.
- Compare indications of interest using common criteria.
- Run management meetings and solicit letters of intent.
- Select a preferred bidder based on value, structure, certainty, and fit.
- Manage diligence requests, issues, evidence, and approvals from one controlled plan.
- Negotiate definitive agreements and satisfy closing conditions.
- Execute closing, communications, transition, and post-closing obligations.
Sell-side M&A process FAQs
How long does a sell-side M&A process take?
The timetable varies with company readiness, buyer interest, deal structure, diligence findings, financing, and regulatory review. Sellers should manage the process through milestones and dependencies rather than assume one universal duration.
What is a CIM in sell-side M&A?
A confidential information memorandum, or CIM, is a detailed marketing document provided to qualified buyers after confidentiality protections are in place. It typically explains the business, market, strategy, operations, management, financial performance, outlook, and investment rationale.
What is the difference between an IOI and an LOI?
An indication of interest, or IOI, is usually an early nonbinding proposal used to narrow the buyer field. A letter of intent, or LOI, is a later proposal that sets out principal terms and may include binding provisions such as confidentiality or exclusivity.
When should a seller grant exclusivity?
Exclusivity is usually considered after the seller has selected a preferred bidder and aligned on the principal commercial terms. Before granting it, the seller should evaluate financing, diligence readiness, regulatory risk, closing conditions, and the leverage that will be lost when other bidders are paused.
What belongs in a sell-side M&A data room?
A data room commonly includes corporate records, financial statements, tax materials, customer and supplier contracts, employment information, intellectual property, insurance, compliance evidence, litigation records, technology and cybersecurity materials, and other documents relevant to the business and transaction.
How can a seller reduce the risk of a buyer retrade?
Prepare reliable information, disclose material issues in a controlled way, maintain buyer competition until the preferred bidder is selected, define assumptions clearly, track diligence questions, and resolve major commercial terms before granting exclusivity.